

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Educational and Training Software Market: Why 15.12% CAGR Reshapes Strategy

Navigating the EdTech Inflection Point: Strategic Trends in the Educational and Training Software Market
Market Landscape and Core Challenges
The global educational and training software market has firmly entered a phase of accelerated expansion. Revenue climbed from approximately 175.4 billion USD in 2020 to 355.6 billion USD by 2025, reflecting sustained institutional adoption and shifting learning paradigms. Projections indicate the market will continue compounding at a 15.12 percent CAGR through 2032, reaching an estimated 952.84 billion USD. This trajectory is not merely a post-pandemic normalization but a structural reallocation of how organizations invest in knowledge delivery, skill development, and academic infrastructure.
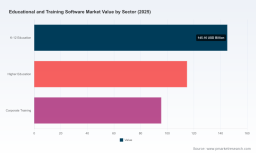
Cloud-based deployment has become the dominant architecture, reflecting broader enterprise preferences for scalability, remote accessibility, and reduced on-premise maintenance overhead. The sector is broadly distributed across K-12 education, higher education, and corporate training, with each segment driving distinct procurement cycles, compliance requirements, and user experience expectations. In terms of application, learning management systems, student information systems, assessment and testing software, and content creation and simulation tools occupy significant portions of the value chain. Geographic adoption remains led by North America, followed by Europe and Asia Pacific, while Latin America and the Middle East and Africa represent faster-growing but still earlier-stage commercialization environments.
Despite this momentum, the market faces three structural challenges that will shape competitive outcomes over the next decade. First, integration fragmentation continues to burden end users. Institutions and enterprises frequently operate disjointed platforms for administration, instruction, assessment, and corporate skill tracking. Without interoperable data standards, organizations struggle to create unified learner profiles, measure continuous competency development, or automate cross-platform workflows. This friction raises total cost of ownership and slows the realization of analytics-driven decision making.
Second, data privacy and AI governance are becoming decisive procurement filters. Educational software now routinely processes sensitive demographic, performance, and behavioral data. Simultaneously, generative AI capabilities are embedded into tutoring, assessment design, content summarization, and administrative automation. Buyers are increasingly scrutinizing model transparency, data retention practices, bias mitigation, and compliance with emerging regulatory frameworks. Vendors that cannot articulate clear governance positions risk exclusion from RFPs, particularly in public sector and higher education procurement.
Third, the market is reaching a saturation inflection in mature segments. Base-level learning management and content delivery tools are becoming table stakes, pressuring vendors to differentiate through outcomes rather than feature lists. Buyers are asking harder questions about whether platforms demonstrably improve completion rates, skill transfer, instructor efficiency, or workforce readiness. This shift rewards vendors that can connect software deployment to measurable organizational impact, while exposing those that rely on perception-based marketing or fragmented point solutions.
For executives and investors, the implication is clear. Growth alone will not guarantee durable advantage. The winners will be organizations that navigate interoperability demands, embed responsible AI into product design, and prove value through outcome metrics rather than platform breadth alone.
Key Drivers Reshaping Demand and Value Creation
Four interconnected forces are driving the market’s next phase of expansion, each reshaping how software is designed, sold, and valued.
Technology Innovation and AI-Infused Learning Workflows
Generative AI has moved from experimental feature to core product architecture. Platforms are now integrating AI-assisted lesson planning, adaptive tutoring, automated rubric generation, multilingual content localization, and intelligent summarization of dense learning materials. These capabilities reduce the manual workload of educators and corporate trainers while enabling more personalized learning paths at scale. The shift is most visible in tools that support test preparation, workplace compliance training, and skills-based upskilling, where rapid content iteration and individualized pacing create tangible efficiency gains.
Equally important is the move toward AI-supported instruction rather than AI replacement. Educational institutions and employers are exploring tools that augment human facilitation, provide real-time feedback, and help managers identify skill gaps earlier in the learning journey. This balanced positioning is becoming a design principle for platforms seeking wide adoption across risk-averse and pedagogy-sensitive environments.
Policy, Regulation, and Institutional Standardization
Regulatory and policy environments are increasingly shaping procurement behavior. Public agencies and multilateral organizations are publishing guidance on responsible AI use in education, emphasizing transparency, age-appropriate design, and safeguards around student data. In parallel, regional frameworks are beginning to classify certain AI applications as higher-risk, particularly where biometric or emotion-recognition technologies intersect with learning environments. These developments do not slow adoption outright, but they do raise the bar for compliance, documentation, and vendor accountability.
At the same time, policy-driven workforce initiatives are expanding demand for accessible training tools. Government-backed literacy and AI readiness programs are surfacing as new adoption channels, especially when delivered through lightweight, mobile-friendly, or text-based formats that can reach workers outside traditional classroom settings. Such initiatives create downstream demand for content authoring, assessment, and tracking capabilities that can plug into broader skills infrastructure.
Demand-Side Shifts in Learning Behavior and Workforce Expectations
Learner expectations are changing faster than many legacy platforms can accommodate. Students, professionals, and managers increasingly expect seamless mobile experiences, modular microlearning, and visible connections between training and career progression. In corporate environments, learning is no longer treated as a separate HR function but as part of continuous performance enablement. This is driving demand for platforms that connect learning activity to role readiness, internal mobility, and compliance tracking.
In academic settings, there is growing emphasis on hybrid instruction models, credit-bearing digital credentials, and tools that reduce administrative load without compromising instructional quality. The line between formal education and professional training is blurring, encouraging platforms that can serve both contexts with consistent identity, assessment, and reporting experiences.
Education Software Market
Cost Structure and Deployment Economics
Economic pressures are reinforcing cloud-first adoption while also changing how organizations justify software spend. Budget holders want platforms that lower IT maintenance burdens, scale across campuses or enterprise units, and reduce content production costs through reusable templates, automated localization, and AI-assisted authoring. The economics of content creation are especially relevant in fast-moving technical fields where courseware can become outdated quickly. Vendors that shorten content update cycles and enable non-specialist staff to maintain materials are gaining an operational advantage.
At the same time, the cost of switching is rising as programs deepen their dependency on integrated ecosystems. Once a platform becomes the system of record for enrollment, assessment, or compliance, migration becomes politically and operationally difficult. This dynamic is strengthening retention for incumbents with broad deployment footprints, while making it harder for new entrants to displace established workflows without a clearly superior value proposition.
Competitive Landscape and Leading Strategies
The market remains comparatively fragmented at the top, with no single vendor holding dominant share. Industry concentration is moderate, with the top three players accounting for roughly 19.45 percent of revenue and the top five reaching about 29.8 percent. This structure leaves substantial room for differentiation, niche specialization, and regional expansion, but it also intensifies pressure on vendors to define a sharp strategic position rather than compete across every segment simultaneously.
Customer Support Training Software Market
Several strategic archetypes are emerging among leading players. Broad online learning platforms continue to scale by pairing content breadth with credentialing and professional signaling. Their advantage lies in audience reach, employer partnerships, and the ability to connect learning to career outcomes. Gamified and mobile-first learning apps occupy a different position, using engagement mechanics to lower barriers to entry and expand into adjacent subjects beyond their original focus. Their growth increasingly depends on converting casual users into sustained learning habits and leveraging platform ecosystems for cross-subject expansion.
Learning management system providers remain central to institutional adoption, competing on usability, integration depth, and support for diverse teaching and training models. Their differentiation often comes from how well they serve blended environments, simplify instructor workflows, and connect with student information or assessment systems. In parallel, corporate and skills-focused platforms compete on personalized learning paths, compliance coverage, leadership development, and technology skills curricula. These vendors are positioning learning as an operational capability rather than a one-off training event.
Large technology providers are layering educational capabilities onto existing productivity and cloud ecosystems. Their strategy typically emphasizes AI-enabled tools, identity and collaboration infrastructure, and low-friction adoption through familiar interfaces. By embedding learning assistance, content summarization, and classroom or workforce support tools into broader software environments, they aim to reduce switching costs and increase platform stickiness. Eu-based and multi-regional regulatory considerations are also shaping how these providers design data handling and AI features for education use cases.
Recent product and program activity illustrates how quickly the landscape is evolving. Major providers have launched educator-focused programs that bundle AI-supported teaching tools, content creation features, and improved access controls for instructional workflows. Other vendors have expanded personalized learning journeys and acquired AI content capabilities to speed creation and adaptation of training materials. In parallel, public-sector workforce initiatives are pairing free AI literacy resources with accessible delivery formats, expanding the reach of digital training beyond traditional buyers. The OECD’s recent exploration of generative AI design principles in education further underscores the growing expectation that learning tools should be effective, transparent, and context-aware.
The competitive trend points toward both consolidation and specialization. Larger platforms are likely to pursue integrations that cover identity, content, assessment, analytics, and administrative workflows in a more unified stack. At the same time, specialized providers will continue to thrive by solving narrow problems exceptionally well, such as high-stakes assessment, simulation-based training, language acquisition, or compliance-heavy corporate programs. New entrants are most likely to succeed where they can address underserved segments, offer superior UX for specific user groups, or provide interoperable tools that reduce integration burdens for existing ecosystems.
Future Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to define where value concentrates. First, AI will become a standard layer across learning workflows, but differentiation will shift from “having AI” to “using AI responsibly and effectively.” Platforms that demonstrate measurable improvements in instructor efficiency, learner completion, and assessment quality will command stronger positioning than those that merely showcase automation features. Commercial opportunities will arise for vendors that can package AI capabilities as trustworthy, auditable, and aligned with institutional governance requirements.
Second, interoperability and unified learner data will become strategic purchasing criteria. Buyers will increasingly favor solutions that can exchange data cleanly across administrative, instructional, and workforce systems. This creates openings for middleware, analytics layers, and platforms designed with open integration as a core architectural choice. Companies that reduce the integration tax for schools, universities, and enterprises will be better placed to expand within accounts and cross-sell adjacent modules.
Third, the boundary between education and workforce training will keep eroding, especially in skills-based hiring and internal mobility programs. Organizations will look for tools that support continuous credentialing, competency mapping, and scenario-based simulation. This trend favors platforms that can serve both academic and corporate audiences with adaptable content models and reporting frameworks. There is also opportunity in lightweight, high-reach training formats that support large-scale literacy and upskilling initiatives, especially where accessibility and low friction matter more than feature density.
Risks remain significant. Regulatory uncertainty around AI in education could alter procurement requirements or limit certain use cases, particularly where sensitive data or high-stakes decisions are involved. Overreliance on automation may trigger pushback if learners or instructors perceive quality degradation or excessive surveillance. Macroeconomic pressure could also compress discretionary budgets, making outcome proof and total cost of ownership more important than novelty. Vendors and buyers alike will need to balance innovation with governance, integration, and measurable impact.
Strategic Actions for Decision-Makers
For platform builders and product leaders, the priority is to design for interoperability and governance from the start. Products should make it easy to exchange learner data, support modular content creation, and provide transparent controls for AI-assisted features. Differentiation should be anchored in workflows that reduce instructor or administrator burden while improving learning outcomes, not simply in the presence of advanced features.
For investors, due diligence should focus on retention economics, integration depth, and evidence of outcome-based value. The most durable opportunities are likely to sit in segments where software becomes embedded in daily operations, compliance, or credentialing, rather than in discretionary point tools. It is also important to assess how prepared portfolio companies are for evolving AI regulation and data-handling expectations, since these factors will increasingly influence procurement velocity.
For procurement and strategy teams, selection criteria should expand beyond feature checklists. Evaluations should include data portability, integration effort, AI governance documentation, and the vendor’s ability to demonstrate measurable improvements in efficiency or learner performance. Pilots should be structured to test whether a platform can reduce administrative load, support personalized learning or training paths, and fit within broader systems already in use.
Given the speed of product launches, regulatory updates, and adoption shifts across regions and sectors, high-level market narratives are no longer sufficient for planning. Decision-makers benefit from detailed segmentation data, company-level benchmarking, and scenario analysis that connects technology roadmaps with procurement realities. Those seeking a fuller view of segmentation dynamics, regional demand patterns, and vendor positioning can use the complete PW Consulting market research report to inform investment, product, and procurement decisions with greater precision.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Educational and Training Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com