

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: IGBT Market Poised for 6.88% CAGR to USD 12.97B by 2032
By pmarketresearch, 2026-07-13
IGBT Market 2026 Strategic Preview: Essential Insights for Executive Decision-Making
As Pw Consulting’s Chief Industry Analyst, I present a focused strategic preview of our IGBT Market research—designed to inform capital allocation, product strategy, supply-chain posture, and M&A prioritization for 2026. This preview synthesizes the most consequential findings from our full study (base year 2025) and lays out how the market trajectory and near-term industry dynamics translate into practical, boardroom-ready choices. To preserve the value of our proprietary segmentation and model, this article deliberately omits granular regional and application breakdowns; the full report contains the detailed tables, scenario outputs, and downloadable model that underpin the guidance below.
IGBT Market
Market Trajectory: A Data-Driven Snapshot
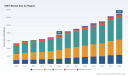
The IGBT market has entered a sustained growth phase. Our market model tracks a recovery and accelerated adoption curve from 2020 through the forecast horizon. In aggregate terms (USD, revenue in Million), the industry grew from approximately 5.3 billion in 2020 to 7.56 billion in 2025. Under our base forecast, the market expands to roughly 8.43 billion in 2026 and continues on a compound annual growth path to reach an estimated 12.97 billion by 2032. The compound annual growth rate embedded in the forecast period is 6.88%.
IGBT Market
Two implications are immediate for 2026 planning: first, absolute demand for higher-performance power modules and smart IGBT solutions is rising; second, the growth profile creates incentives for both incumbents and new entrants to accelerate product roadmaps and supply-chain commitments now, rather than waiting for fully realized end-market pull.
IGBT Market
Why 2026 Is a Strategic Inflection Point
- Momentum meets scarcity: Rising end-demand is colliding with supply constraints in critical upstream inputs. Notably, Si wafer availability has tightened—pushing lead times for intelligent power modules beyond 16 weeks in many cases. For manufacturers and OEMs, this means lead-time risk must be managed proactively through dual-sourcing, priority agreements, and localized safety-stock strategies.
- Technology transition windows: Product launches and sampling activity from major suppliers (e.g., new 400 V / 800 V chips for EV platforms, and next‑generation 1.2 kV modules for industrial and renewable segments) indicate a narrowing window to validate and adopt next‑gen IGBT architectures. OEMs who defer migration risk being locked into longer lifecycles of legacy parts or facing retrofit costs.
- Regulatory and policy drivers: Export control regimes and accelerated renewables deployment are reshaping both supply and demand. Export controls adopted since 2024 add geopolitical complexity to sourcing advanced device-process technologies, while substantial additions to wind and solar capacity in 2025 reinforce long-term demand for inverter-grade IGBT solutions.
Practical Strategic Actions for 2026
Our analysis converts market dynamics into actionable decision levers. For leadership teams preparing budgets and product plans for 2026, prioritize the following:
- Prioritize qualification pipelines: Accelerate qualification cycles for new IGBT families and modules that align to your product roadmap. Given sampling programs and commercial announcements already underway among key suppliers, early engagement will secure engineering slots and mitigate time-to-market risk.
- Secure upstream capacity: Negotiate wafer and packaging capacity commitments with tier-1 suppliers, and evaluate inventory-financing options. Short-term increases in safety stock can be value-accretive when lead times exceed 16 weeks for critical module families.
- Match product tiers to margin pools: Layer your portfolio decisions—reserve R&D and high-cost packaging investments for segments where differentiation yields durable margin advantage (e.g., electric powertrains and industrial motion control). For high-volume, lower-margin applications, optimize cost through standardized module architectures and contract manufacturing partnerships.
- Scenario-proof procurement: Build flexible buying strategies with triggers tied to observed wafer-price and lead-time shocks. Contingency contracts that can be activated based on objective thresholds protect production without permanently inflating working capital.
- Reassess M&A and JV priorities: The market concentration metrics indicate meaningful scale advantages. Strategic acquisitions that add complementary module capabilities, local manufacturing footprint, or access to vertically integrated wafer capacity can rapidly move an acquirer up the curve. Target prioritization should weight technology fit, shortening of qualification timelines, and access to regulated or constrained supply chains.
Competitive Landscape: Who’s Doing What—and What That Means
The industry remains led by established power-electronics players that combine device physics, packaging, and system know-how. Market concentration is material: the combined share of the three largest firms is approaching half the market, while the top five firms together control a clear majority—underscoring scale economies in R&D, production, and channel access.
- Infineon Technologies AG — A global leader with deep product families spanning CoolSiC and hybrid drive modules. Their recent announcements targeting EV electric drive trains signal continued prioritization of automotive and high-efficiency drivetrain platforms. For customers, Infineon represents a strategic partner for high-voltage and silicon-carbide transitions.
- ON Semiconductor Corporation — Focused on flexible portfolios of standard and custom IGBTs across EV and industrial segments. Their strength lies in delivering tailored solutions at scale—a model attractive to OEMs needing differentiated electrical or packaging requirements without starting from silicon design.
- Mitsubishi Electric Corporation — Long-standing traction and industrial module supplier; recent sampling of new 1.2 kV LV100 and NX-type modules underscores their push into higher-efficiency industrial and renewable applications. Mitsubishi’s cadence of sample-to-production timelines is an important signal for OEM roadmaps in 2026.
- Fuji Electric & ROHM Semiconductor — Both combine aggressive device iterations (e.g., RC-IGBT and field-stop trench technologies) with targeted compact packaging—well suited to xEV and inverter segments where thermal and size trade-offs are critical.
- Magnachip, STMicroelectronics & Toshiba — Each leverages niche strengths: Magnachip’s recently launched 650 V/1200 V discrete series for solar and storage (late 2025) expands options for inverter OEMs; ST’s packaging and automotive focus play to high-efficiency conversion trends; Toshiba’s traction modules keep it relevant in rail and heavy industrial sectors.
For corporate strategists, the takeaway is clear: supplier selection in 2026 is not a binary technical choice—it is a strategic decision that shapes supply‑chain resilience, product differentiation, and total lifecycle costs.
Supply-Chain & Policy Risks That Will Drive Boardroom Decisions
- Upstream material constraints: Si wafer scarcity has moved from a tactical headache to a strategic lever. Where possible, secure capacity via multi-year agreements, explore wafer-substitute roadmaps if applicable to your designs, and prioritize product architectures that tolerate alternate supply routes.
- Export controls and technology access: Post-2024 export-control regimes add friction to acquiring advanced process technologies and certain control electronics. Firms pursuing aggressive silicon or packaging roadmaps must embed geopolitical risk assessments into engineering-sourcing trade-offs and consider local development or licensing strategies where necessary.
- Demand-policy coupling: Rapid renewables deployment and energy-policy incentives materially alter end-market sizing for inverters and storage. Expect policy-driven procurement cycles (e.g., utility tenders) to periodically amplify demand—requiring flexible manufacturing response plans.
What the Full Report Contains (Practical, Executable Deliverables)
The complete PW Consulting IGBT Market study provides a suite of deliverables structured for rapid operationalization by commercial, engineering, and corporate development teams. Highlights include:
- A transparent, downloadable market model (historical 2020–2025; forecast 2026–2032) with scenario toggles for adoption pace, wafer-price shocks, and policy-driven demand surges.
- A supplier risk matrix quantifying lead-time exposure, technology maturity, and geopolitical sensitivity—mapped to suggested mitigation actions and contract structures.
- Segment-level pricing curves and margin waterfall diagnostics to guide product architecture trade-offs and target profitability by application class (note: detailed segment tables are reserved for the full report).
- Competitive profiles and a 12–24 month battle plan for customer engagements with the key vendors discussed above, including procurement playbooks and engineering-qualification checklists.
- M&A screening framework: prioritized acquisition themes, indicative valuation ranges, and integration scorecards tailored to IGBT value chains.
How Executives Should Use This Preview in 2026 Planning
- Investment committees: Use the macro trajectory and concentration metrics to set capital allocation thresholds for capacity expansion, R&D, and inorganic growth. Prioritize investments that close product gaps faster than competitors.
- Product management: Align release calendars to supplier sample windows and prioritize modules that unlock adjacent revenue streams (e.g., electrified mobility and utility-scale inverters).
- Procurement: Convert lead-time intelligence into contracting actions—multi-sourced frameworks, capacity carve-outs, and performance-based penalties to stabilize supply assumptions reflected in 2026 budgets.
- Corporate development: Target small to mid-size acquisitions that provide immediate supply resilience, niche module IP, or local manufacturing footprints—especially where regulatory controls complicate cross-border technology transfer.
Closing: The Strategic Opportunity Ahead
The IGBT market’s projected expansion to roughly 13 billion USD by 2032, coupled with a mid-single-digit CAGR, represents both opportunity and a test of strategic agility. Firms that translate lead-time intelligence, supplier roadmaps, and regulatory shifts into decisive 2026 actions will capture outsized share and margin. Conversely, organizations that treat the market as a steady-state electronics category risk being outmaneuvered by suppliers and competitors better aligned to the next wave of EV, industrial automation, and renewable-power requirements.
For readers seeking the full empirical foundation—detailed regional and application splits, the scenario-ready model, supplier scorecards, and transaction-level M&A screening—please consult the full Pw Consulting IGBT Market report and model on our website. The comprehensive materials provide the granular inputs you need to convert the strategic priorities outlined here into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: IGBT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intra Oral Scanners Market to Grow at 9.2% CAGR Through 2032
By pmarketresearch, 2026-07-13
Intraoral Scanners 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a strategic preview of our comprehensive Intra Oral Scanners market research — a briefing built for corporate leaders, investors, and clinical operations executives preparing critical decisions in 2026. This article highlights why the intraoral scanner (IOS) market is a high-conviction investment area, summarizes the macro trajectory, and outlines the executable insights you will find in the full report. In keeping with our “trailer” approach, we demonstrate analytical depth while intentionally withholding core sub-segment tables and granular share-breakdowns to encourage consultation of the source report for transaction-grade intelligence.
Intra Oral Scanners Market
Market at a Glance — Why 2026 is a Pivot Year
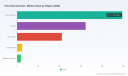
The IOS market has moved from an early-adopter niche to a mainstream digital dentistry infrastructure. After accelerating through 2020–2025, the global market grew from roughly USD 350 million in 2020 to about USD 535 million in 2025. Under our baseline model, the market enters the forecast window (2026–2032) with a compound annual growth rate of 9.2%, approaching roughly double the 2025 size by 2032. This trajectory is driven by converging forces: clinical validation, software-enabled diagnostic expansion, falling per-scan costs, and structural reimbursement updates that embed scanning into standard workflows.
Intra Oral Scanners Market
Why this report matters for 2026 decisions
- Capital allocation: whether you are a device OEM deciding R&D and platform investments, or a multi-site dental group evaluating fleet economics, our analysis quantifies the investment horizon for scanner replacement cycles and complementary consumables, enabling build-vs.-buy decision rules.
- Go-to-market and channel strategy: our markets maps and buyer-journey segmentation reveal where service partners, labs, and dental chains will prioritize bundled hardware–software offerings versus open-platform strategies.
- Regulatory and reimbursement risk-adjustment: the report integrates recent regulatory milestones and coding changes to show how near-term approvals and CDT updates change payback timelines for clinics and lab partners.
What the full report delivers — practical, transaction-ready outputs
- Proven methodology: an auditable framework combining primary interviews, device benchmarking, clinical validation studies, and bottom-up revenue modeling (base year 2025; historical 2020–2025; forecast 2026–2032).
- Deployment economics: clinic-level TCO models with sensitivity analysis for utilization rates, sterilization cycles, consumables and maintenance that convert scanner metrics into per-procedure costs and ROI tables.
- Commercial playbooks: differentiated GTM options for OEMs (direct, distributor, OEM+lab), pricing levers (hardware subsidies, SaaS imaging fees, data licensing), and a mapping of channel margins for prioritized markets.
- Technology roadmaps: maturity assessment for key enablers — AI diagnostic overlays, hyperspectral imaging, photogrammetry for full-arch accuracy, and cloud-native vs. on-premises workflows.
- Regulatory and reimbursement tracker: impact analysis of recent rulings and code updates on adoption velocity, plus scenario planning for tightened regulatory controls or expedited clinical clearances.
- Competitive risk matrix: differentiated strategic options for incumbents and challengers, including vertical integration scenarios with labs, orthodontic workflows, and implant ecosystems.
Competitive Dynamics — what to watch in 2026
The IOS competitive landscape is concentrated around several global leaders and a broadening field of regional and value-oriented challengers. Our concentration analysis shows a market where the top three players collectively command a dominant share of industry revenue, and the top five extend that dominance further — a structure that favors scale advantages in software ecosystems, clinical validation, and regulatory investment.
Intra Oral Scanners Market
Key players we analyze in depth include long-established dental device manufacturers and fast-moving software-integrated challengers. Representative company profiles and recent milestones covered in the report:
- Dentsply Sirona — continued focus on high-accuracy restorative and chairside solutions; recent regulatory clearance expanded clinical claims that change the competitive baseline for diagnostic features.
- 3Shape — aggressive software play with TRIOS 6 and diagnostic modules; firmware-level innovation (e.g., hyperspectral packages) moves the vendor from scanner supplier to diagnostic platform provider.
- Align Technology — strong orthodontic workflows and visual ergonomics; device roadmap emphasizes integration with clear aligner ecosystems and visualization tools for clinicians and patients.
- Straumann — ecosystem play linking scanning with implant and prosthetic solutions, with an emphasis on sterilizable tip economics and clinical reliability.
- Leading Chinese OEMs and new entrants — competitive price-performance instruments and targeted full-arch photogrammetry solutions that pressure mid-range pricing and expand addressable markets.
Recent industry developments illustrate the pace of competitive evolution: a major FDA 510(k) clearance in 2025 expanded clinical diagnostic claims for a flagship scanner, a 2025 product launch at IDS repositioned a leading software vendor with AI-driven diagnostic apps, and 2026 updates include firmware-enabled hyperspectral imaging and independent product recognitions that alter buyer perceptions. The full report provides an event calendar and impact scoring to translate these announcements into market share scenarios.
Regulatory, clinical and reimbursement inflection points
- Regulatory: ISO 13485 remains a gating requirement in major markets; recent device clearances that allow specific diagnostic claims materially increase device value and buyer willingness to pay.
- Reimbursement: CDT code changes effective in 2026 formally recognize digital workflows (including duplicate denture fabrication via scanning and 3D printing), accelerating scanner adoption in restorative and prosthetic clinics where reimbursement alignment reduces payback periods.
- Clinical workflow costs: autoclave-compatible tips and consumables introduce recurring costs — typical sterilization cycles per tip are a practical operating constraint, and we show how tip lifecycle economics affect per-procedure pricing models.
Technology and operational drivers — what changes unit economics
Three technology trends will shape unit economics through 2026 and beyond: (1) the maturation of AI-powered diagnostic overlays that expand use cases beyond impressions; (2) improvements in full-arch photogrammetry and hyperspectral imaging that reduce retake rates and lab rework; and (3) the shift to cloud-native scanning platforms that enable subscription revenue and centralized analytics. Operationally, the net savings from reduced impression materials and shipping must be balanced against capital expenditure and integration costs. Our clinic-level models allow users to test multiple depreciation schedules and utilization assumptions to derive practical acquisition thresholds.
Strategic playbooks for 2026 stakeholders
- OEMs: prioritize platform extensibility and validated diagnostic claims. Invest selectively in hyperspectral and AI integrations that create defensible software moats; use financing and subscription models to accelerate penetration in small-group practices.
- Dental chains and DSOs: standardize on a primary platform that maximizes cross-site workflow consistency; leverage volume procurement for bundled software services and prioritize systems with open-architecture compatibility to avoid vendor lock-in risks.
- Dental labs and service bureaus: partner early with photogrammetry-capable vendors to offer validated full-arch services; create margin-rich “scan-to-model” capabilities and data-driven QA packages for high-value implant and prosthetic cases.
- Private equity and investors: focus diligence on software monetization, installed-base service revenue, and regulatory claim breadth. Use our scenario outputs to stress-test exit multiples under multiple adoption curves.
How to use the report in 60–90 days
- Week 1–2: run the clinic-level TCO model with your utilization and financing inputs to establish a buy/sell threshold for equipment procurement cycles.
- Week 3–6: perform a vendor short-list using our competitive scorecards and validated feature-differentiation maps; field-test two devices against retention and sterilization workflows.
- Week 7–12: negotiate commercial pilots with preferred vendors, leveraging our subscription and channel margin benchmarks to structure trial economics and performance clauses.
Conclusion — the strategic take
Intraoral scanners are transitioning from a device purchase into a platform decision with long-lived implications for clinical workflows, data ownership, and recurring revenue streams. The market’s double-digit growth trajectory through the next seven years creates multiple entry points for value creation, but success depends on integrating device capabilities with software, regulatory strategy, and channel economics. Our full report provides the granular, transaction-grade intelligence you need to convert these market dynamics into defensible corporate actions in 2026.
Next step
For the complete data tables, sub-segment forecasts, and executable models referenced here — including the drilldowns that support acquisition valuation, product roadmaps, and go-to-market playbooks — please consult the full PW Consulting Intra Oral Scanners market report. The report contains the confidential sub-segment outputs and scenario analyses required for procurement, M&A, and capital allocation decisions.
For detailed analysis of this topic, please visit the official page: Intra Oral Scanners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LED Drivers Market to Reach USD 72.61 Million by 2032 at 10.1% CAGR
By pmarketresearch, 2026-07-13
LED Drivers Market — Strategic Preview for 2026 Decision-Makers
Executive summary
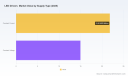
As LED-based lighting and solid-state applications move from niche to pervasive, LED drivers have transitioned from a commodity adjunct to a strategic component that shapes product economics, system reliability, and energy outcomes. Our synthesis of historical performance (2020–2025) and forward-looking scenarios (2026–2032) shows a market on a sustained expansion path, underpinned by product electrification, regulatory tightness on energy performance, and rapid IC innovation. The market is growing at a robust compound annual growth rate (CAGR) of 10.1% through the forecast window, with the overall market more than doubling from the mid-2020s to the end of the decade under our central case.
LED Drivers Market
For executive teams planning 2026 investments — whether in procurement, R&D, manufacturing footprint or M&A — the findings in our full LED Drivers Market study translate into actionable strategic priorities and direct ROI implications. This preview highlights the high-level drivers, competitive positioning signals, and the practical decision levers that organizations should prioritize this year. Detailed subsegment metrics, supplier-level scorecards and downloadable financial models are intentionally reserved for the full report to preserve actionable differentiation; the summary below is designed to demonstrate analytical depth and decision relevance.
LED Drivers Market
Why this research matters for 2026 decisions
-
Procurement optimization: Component lead times and raw-material concentration have become primary determinants of product launch timelines and margin realization. 2026 procurement cycles must account for both price volatility and supply-security clauses to protect gross margins.
LED Drivers Market -
Product roadmap prioritization: Choices around GaN adoption, DALI/D4i interoperability, dimming sophistication, and IP-rated form factors directly affect product premium and compliance windows as energy-efficiency rules tighten.
-
M&A and partnership timing: With a moderately consolidated supplier landscape and a handful of scale players controlling a meaningful portion of capacity, bolt-on acquisitions or licensing deals can be decisive for market entrants and tier-2 OEMs seeking fast capability expansion.
-
Manufacturing and localization: Tariff scenarios, component sourcing risk, and regional policy incentives will make 2026 the year to finalize or accelerate reshoring and assembly footprint strategies.
What the full report delivers (practical, operational outputs)
-
Proprietary market-sizing and forecast models (2020–2032) with downloadable spreadsheets and scenario toggles for alternative macro and raw-material trajectories.
-
Supplier scorecards and a five-step procurement playbook that maps supplier capabilities to product specifications (dimming, flicker, IP rating, thermal design) and procurement levers (MOQ, consignment, hedging).
-
Technology adoption pathways comparing incumbent silicon drivers with GaN-on-Si options, including ROI windows, component-level BOM sensitivity, and thresholds where GaN delivers net TCO gains.
-
Regulatory and standards matrix tying global policy developments to product certification roadmaps (including energy-efficiency requirements and smart-lighting interoperability standards).
-
Supply-risk index that quantifies exposure to raw-material concentration, geopolitical policy moves, and single-source suppliers; includes recommended mitigation tiers.
-
Commercial playbooks for brand licensing, OEM/ODM partnerships, and white-label strategies, with model clauses and example term-sheets calibrated to current market conditions.
-
Primary interview insights from manufacturers, lighting OEMs and IC suppliers, plus transaction comps and a short-list of acquisition targets based on strategic fit and integration risk.
Market dynamics to incorporate into your 2026 planning
The LED drivers market operates at the intersection of semiconductor trends, raw-material concentration, and energy policy. Several dynamics are central to near-term outcomes:
-
Raw-material concentration: Refined supplies for critical inputs used in driver ICs remain highly geographically concentrated. That concentration creates acute price and availability sensitivity when export controls or production shocks occur.
-
Regulatory tightening: Regional energy-efficiency directives are accelerating demand for higher-efficiency drivers and certified smart functionality. Compliance timelines are compressing product roadmaps and creating a premium for certified offerings.
-
IC innovation and cost curves: Rapid declines in the cost of GaN-on-Si driver ICs are moving what was once a niche performance upgrade into mass-adoption economics; the tipping point varies by application complexity and scale.
-
Trade and tariff risks: Proposed tariff adjustments on semiconductor inputs and components create incremental fabrication cost risk; manufacturers must model tariff pass-through scenarios and adjust sourcing strategy accordingly.
-
Supply-chain shocks and short-term dislocations: Policy actions affecting rare earths and analog semiconductor inputs have already produced intermittent supply disruptions and price spikes; resilient design-for-supply and multi-sourcing are now operational imperatives.
Competitive landscape — signals, not exhaustive rankings
The competitive map combines established power-supply specialists, IC innovators, and lighting-system incumbents. The market exhibits moderate concentration (three-firm and five-firm concentration ratios indicate a material presence of scale manufacturers) which influences pricing power and channel dynamics.
-
Mianwei Electronics (New Taipei City, Taiwan): A global leader known for reliable, standard power supplies and a wide LED driver portfolio including dimmable and ingress-protected models. Their breadth makes them a steady supply anchor for general lighting OEMs.
-
Tridonic GmbH & Co. KG (Austria): Focused on high-efficiency, smart drivers with strong DALI and professional lighting credentials. Their sustainability orientation and controls expertise position them well in high-end and commercial segments.
-
Inventronics Inc. (Hangzhou, China): Specializes in robust drivers for sports and large-format lighting with certified wireless/DALI+ offerings. Recent leadership changes and product expansions underscore a strategic push into premium lifecycle services.
-
Eaglerise (China): High-performance general lighting drivers; notable for recent licensing moves that extend brand reach via partnerships with established luminaire brands.
-
ERGLighting (USA): US-based designer focusing on UL-listed, low-flicker products — attractive to customers requiring domestic-supply credentials and tight compliance assurances.
-
SOSEN Electronics, Lifud Technology, Macroblock, Delta Electronics, Philips/Signify and others: These players populate a spectrum from IC level innovation to branded system suppliers. Each brings differentiated strengths — from highest-efficiency constant-current platforms to intelligent ICs and global go-to-market reach.
Recent industry moves are instructive: brand-licensing partnerships, executive transitions at major suppliers, and targeted product launches in non-isolated drivers and sports-lighting applications signal accelerating product specialization and go-to-market complexity. These developments create both opportunity and integration risk for OEMs and distributors planning 2026 product introductions.
Strategic playbook — recommended priorities for 2026
-
Hedge critical-input exposure: Implement multi-tiered contracts for gallium-dependent components and evaluate strategic stockpiles sized to 3–6 months of critical input needs under high-stress scenarios.
-
Accelerate GaN migration where economics support it: Identify two pilot product lines where GaN-on-Si yields unit-cost or performance advantages and create cross-functional sprints to shorten time-to-production.
-
Certify early, sell longer: Invest in compliance and smart-driver certification ahead of expected regulation enforcement windows to capture premium shelf space and avoid last-minute redesign costs.
-
Design for multi-sourcing: Standardize driver interfaces and modularize power subsystems so that multiple suppliers can be qualified with minimal rework.
-
Negotiate flexible commercial terms: Include price-indexed clauses, call-off arrangements, and options for capacity ramp-down to balance cost control against supply reliability.
-
Explore licensing/brand partnerships selectively: For OEMs seeking rapid channel entry, licensing established lighting brands or co-branding premium driver modules can compress commercialization timelines.
-
Monitor consolidation signals: Use our scenario triggers to identify when to pursue acquisitions versus strategic alliances based on supplier valuation spreads and capacity availability.
Why PW Consulting’s full study is essential for executable plans in 2026
This preview outlines the high-level forces reshaping the LED drivers market, but the execution advantage comes from granular, validated inputs: supplier-specific performance benchmarking, subsegment demand elasticities, BOM-level sensitivity models, and contractual templates that translate strategy into procurement and engineering actions. Our full report packages those assets with a supply-risk index, scenario-adjustable financial models, and an annotated short-list of strategic targets — tools designed to move teams from planning to measurable outcomes within a single fiscal cycle.
Conclusion
The LED drivers market is in the midst of a structural upcycle driven by electrification, regulatory pressure for efficiency, and semiconductor-driven performance gains. The 10.1% CAGR through the forecast horizon encapsulates both the growth opportunity and the implicit complexity every executive must manage in 2026. Success will belong to organizations that combine rapid technical adoption, disciplined supply resilience, and commercially savvy partnerships. PW Consulting’s full market intelligence is built to accelerate those capabilities — the high-resolution segmentation, supplier dossiers and modeling workbooks that underpin confident, defensible decisions are included in the full report available from our research portal.
For detailed analysis of this topic, please visit the official page: LED Drivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Graphite Heat Exchanger Market to Hit USD 456.11M by 2032 at 9% CAGR
By pmarketresearch, 2026-07-13
Graphite Heat Exchanger Market — Strategic Outlook for 2026 Decision-Making
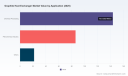
PW Consulting’s latest Graphite Heat Exchanger Market study (base year 2025; historical 2020–2025; forecast 2026–2032) is designed to be the operative intelligence pack that senior executives, procurement leads, and product strategists will use to shape decisions in 2026. The market is on a robust growth trajectory — our top-line modelling shows a compound annual growth rate (CAGR) of 9.0% over the 2026–2032 forecast window, with the total market expanding from USD 251.38 Million (base year 2025) toward USD 456.11 Million by 2032. This report translates that macro momentum into executable options: where to invest, which partners to prioritise, and how to de-risk projects in ultra-corrosive process environments.
Graphite Heat Exchanger Market
Why this study matters for 2026
-
Timing: 2026 is a hinge year for buyers and suppliers. Accelerating chemical production volumes and renewed capital expenditures across refining and specialty chemicals are creating near-term demand spikes while long-term technical requirements are shifting.
Graphite Heat Exchanger Market -
Margin pressure and supply-side risk: Raw material dynamics and selective industry consolidation are already influencing supplier economics and lead times; procurement strategies formed in 2026 will determine coefficient of variability in 2027–2030 performance.
Graphite Heat Exchanger Market -
Regulatory and technical compliance: Graphite heat exchangers must comply with international pressure and manufacturing codes and are routinely validated by independent authorities; this elevates the importance of certified supply chains and validated installation practices in 2026 procurements.
Top-line market context (concise)
Our market model integrates historical revenue flows (2020–2025) and forward-looking demand drivers to produce a consistent, auditable series of annual market values in USD Million. The market demonstrates steady expansion through the forecast horizon, with accelerating adoption in corrosive-service applications and an increasing value placed on engineered solutions that balance durability with serviceability. Market concentration is moderate: the combined revenue share of the top three suppliers is in the high 30s (CR3 ≈ 38%), and the top five reach just over half the market (CR5 ≈ 52%), indicating room for both competitive differentiation and targeted consolidation plays.
What the report delivers — practical content for executives
-
Integrated demand and revenue forecasts (2026–2032) with scenario-mode outputs for Base / Upside / Downside planning.
-
Supply-side intelligence: validated supplier profiles, capability matrices, and production capacity assessments — including plant certifications and testing accreditations where applicable.
-
Commercial playbooks: procurement scorecards, contract terms to mitigate price volatility, and lifecycle cost models for retrofit versus replacement decisions.
-
Technical dossiers: comparative heat-transfer performance briefs, corrosion-resistance benchmarks, and installation/maintenance best practices aligned to international pressure codes and third-party testing protocols.
-
Risk and opportunity maps: raw-material sensitivity analysis, regulatory risk heatmaps, and an M&A/opportunity shortlist framework (deal prioritisation, typical value multiples, integration risk pointers).
-
Case studies and worked examples: project-level capital and operating expense (CapEx / OpEx) modelling, commissioning timelines, and warranty / aftermarket frameworks to align supplier incentives.
Market dynamics shaping decisions in 2026
-
Upstream demand push: Global chemical production volumes rose materially in recent periods, creating incremental need for corrosion-resistant heat transfer equipment. This underlying demand is a primary driver of the market’s near-term growth profile.
-
Raw material volatility: Graphite pricing exhibits regional spreads that matter for procurement and landed cost. Recent price points show meaningful divergence across geographies, affecting supplier margins and, by extension, lead times and availability for engineered graphite components.
-
Standards and independent validation: Products are increasingly expected to meet international pressure codes and to be independently tested and certified. For buyers, this raises the bar for supplier selection and creates commercial value for vendors with documented third‑party validation and traceable process controls.
-
Technological differentiation: Manufacturers compete on multiple vectors — block architectures, shell & tube adaptations, plate designs, impregnation techniques, and sealing systems. The winners will be those that convert performance advantages (thermal efficiency, corrosion life) into reduced total cost of ownership.
Competitive landscape — who matters and why
The market is populated by specialist engineering houses and materials groups. The profiles below indicate strategic positions and implications rather than exhaustive vendor scorecards (full supplier benchmarking is included in the report).
-
CG Thermal LLC (Houston, USA) — Known for Impervite® advanced graphite heat exchangers and multiple design variants targeted at ultra-corrosive acids and chemical processing. Strategic implication: strong North American engineering presence and product portfolio oriented at high-value corrosive-service projects; relevant for partnerships on turnkey deployments and co‑development of site‑specific solutions.
-
Mersen (Paris, France) — Offers a breadth of engineered graphite heat-exchange platforms. Strategic implication: breadth and scale make them a natural partner for multinational buyers seeking uniform specifications across regions.
-
Graphite India Limited (Kolkata, India) — Focused on impervious graphite exchangers for phosphoric acid and other chemical processes. Strategic implication: strong regional manufacturing cost advantage for projects in South Asia and adjacent corridors; attractive for cost optimisation in greenfield projects.
-
SGL Carbon SE (Wiesbaden, Germany) — Supplies DIABON® graphite heat exchanger products and is reorganising parts of its carbon business to sharpen focus on core competencies. Strategic implication: restructuring may create near-term supply opportunities or acquisitive behaviour; buyers should monitor announcements and evaluate continuity plans.
-
Toyo Tanso Co., Ltd. (Osaka, Japan) — Specialist in isotropic graphite and advanced components. Strategic implication: high-spec material capability that supports performance-sensitive applications (high temperature, specialty chemistries).
-
Nantong Sunshine Graphite Equipment Technology (Nantong, China) — Offers block and shell & tube solutions with full-service compliance to international standards. Strategic implication: attractive for cost-competitive procurement with focus on meeting export certifications.
Recent vendor moves are instructive: CG Thermal’s exhibition presence in late 2025 reaffirms market-facing product launches and application advocacy; SGL Carbon’s announced restructuring in November 2025 underscores potential supplier-side consolidation and the need for contingency sourcing plans.
Strategic imperatives for executives in 2026
-
Hedge raw‑material exposure: lock in graphite supply contracts where possible, build pricing collars, and evaluate strategic inventory buffers for critical projects.
-
Prioritise certified suppliers: require documented compliance with international pressure codes and independent testing as a minimum commercial prerequisite to reduce downstream commissioning risk.
-
Adopt lifecycle procurement KPIs: move beyond purchase price to metrics tied to plant uptime, cycle‑life, servicing intervals, and total cost of ownership — revise supplier SLAs accordingly.
-
Design modularity and retrofit pathways: favour graphite exchanger designs that enable staged installations and simplified maintenance to accelerate payback and reduce operational disruption.
-
Monitor consolidation and M&A windows: with the top five vendors controlling a significant portion of market revenue, there will be tactical opportunities to acquire technology or capacity at attractive multiples during restructuring waves.
-
Invest in after‑sales capability: service, spare stocking, and certified refurbishment deliver outsized margin protection and customer lock-in in corrosive-service markets.
How PW Consulting’s research supports 2026 execution
This study is built to be operational: it includes downloadable cost build-ups, contract templates, an independent supplier maturity matrix, installation and commissioning checklists, and scenario-ready demand models that you can plug into capital planning tools. Importantly — and deliberately — the public executive brief that you are reading now highlights strategic direction and the market’s growth path while withholding the granular regional, product-type, and application-level splits that underpin our recommendations. Those detailed tables and client-ready slide decks are accessible through the report landing page, where you can obtain the full dataset, primary interview transcripts, and bespoke advisory options.
Final note — a 2026 playbook in motion
Entering 2026, buyers and suppliers in the graphite heat exchanger market face a choice: treat the next 18 months as a short-term procurement cycle, or reconfigure supply chains and product strategies to capture durable value across the forecast horizon. With a projected market expansion at a 9.0% CAGR through 2032, the upside from early, well-constructed moves is significant. PW Consulting’s Graphite Heat Exchanger Market study is intended to be the actionable reference for those moves — combining vetted market sizing, supplier intelligence, technical deep dives, and executable playbooks that convert insight into outcomes. For the full dataset, segmentation tables, and supplier scorecards referenced here, please consult the full report available on our website.
For detailed analysis of this topic, please visit the official page: Graphite Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hyperimmune Globulins Market — USD 1,798M in 2025; 6.7% CAGR to 2032
By pmarketresearch, 2026-07-13
Hyperimmune Globulins Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented preview of our forthcoming Hyperimmune Globulins market study. This briefing is designed for C-suite leaders, corporate strategy teams, BD executives and investors preparing for pivotal choices in 2026. It synthesizes macro trajectories, competitive moves and regulatory shifts that will determine who captures the next wave of opportunity — while intentionally omitting the granular segment tables to prompt access to our full intelligence platform for transactional-level detail.
Hyperimmune Globulins Market
Market snapshot: growth trajectory and what it means for strategy
The hyperimmune globulins market has moved from a niche therapeutics category to a strategically important, mid-sized specialty biologics market. Using 2025 as the study’s base year, the market is estimated to be approximately USD 1.8 billion. Our forecast model, which integrates historical trends (2020–2025), production capacity shifts and anticipated clinical/regulatory catalysts, projects the market to grow at a compound annual growth rate (CAGR) of 6.7% over the 2026–2032 period — reaching roughly USD 2.8 billion by 2032.
Hyperimmune Globulins Market
For executives, that headline growth conceals two actionable realities: (1) capacity and yield improvements on the supply side can rapidly reframe competitive advantage and margin profiles, and (2) targeted clinical advances and label expansions can create disproportionate commercial upside for specific product categories. In short, steady headline expansion coexists with asymmetric, high-impact events that will determine winners and losers.
Hyperimmune Globulins Market
Why 2026 is an inflection year
-
Regulatory momentum is accelerating. Recent approvals and investigational filings in 2024–2026 have created a pipeline of near-term catalysts that will affect market access and reimbursement strategy in 2026.
-
Manufacturing innovation is shifting the cost curve. Yield-enhancement approvals and production milestones are improving supply economics, altering sourcing dynamics and shortening the window for new entrants to establish differentiated cost positions.
-
Commercial consolidation and partnerships are intensifying. Distribution arrangements and co-commercialization agreements are redefining reach in key channels — a trend that will accelerate in 2026 as companies convert trial readouts into go-to-market plans.
Practical value of the report for 2026 decisions
Our research is structured to be actionable. It supports three classes of executive decisions:
-
Portfolio prioritization — which indications, formulations and delivery routes to scale, divest or deprioritize based on projected returns and execution risk through 2032.
-
Capacity and sourcing choices — when to invest in yield-enhancing processes or secure long-term plasma supply versus pursuing contract manufacturing partnerships.
-
M&A and partnership playbooks — defensive and offensive deal scenarios grounded in valuation sensitivity to regulatory and production outcomes.
What the full report contains (operational, not just descriptive)
-
Model-driven market forecast by year (base year: 2025) with scenario off-ramps tied to regulatory and manufacturing events; dynamic dashboards to test price, adoption and supply variables.
-
Commercial economics models: net revenue and margin curves under alternate reimbursement and pricing scenarios, including sensitivity to yield improvements and plasma sourcing costs.
-
Go-to-market playbooks for different company archetypes — incumbents, regional specialists, pure-play manufacturers and late-stage clinical entrants — with prioritized tactical initiatives for 12–36 month execution windows.
-
Supply-chain resilience framework: risk heat maps for plasma availability, cold-chain logistics and contract manufacturing capacity, plus mitigation roadmaps and sourcing scorecards.
-
Regulatory and reimbursement tracker mapping known approvals and plausible near-term filings into market-access timelines and payer negotiation levers.
-
Commercial benchmarking of pricing strategy, channel mix and patient hub requirements (redacted in this preview to preserve competitive sensitivity).
Competitive landscape — who matters and why
The market remains shaped by a mix of vertically integrated plasma-to-product firms, specialized contract manufacturers and regional distributors. Key corporate actors to monitor include established plasma-derived manufacturers, manufacturers of indication-specific immune globulins, and strategic distributors that control access to hospital and public-health channels.
-
ADMA Biologics — an end-to-end plasma-derived player that has recently secured regulatory approval for a production yield enhancement process. That approval meaningfully alters production economics and positions ADMA to defend incumbency or pursue volume-driven price strategies. ADMA’s pediatric label expansion for one of its products further underscores a willingness to pursue label extensions to grow addressable markets.
-
Biotest Pharmaceuticals — an established manufacturer with commercial partnerships that expand distribution reach for newer formulations of immunoglobulin therapy; its collaboration models provide a template for how mid-sized players can punch above their weight.
-
CSL Behring — a large incumbent with an extensive portfolio and strong manufacturing footprint; their scale and product breadth make them a natural anchor for many hospital procurement decisions and a likely acquirer of complementary assets.
-
Kedrion / Kamada — examples of the distributor-to-manufacturer chain, where strategic alliances allow regional players to secure supply and expand product offerings without duplicative capital investment.
-
Takeda — a public-health collaborator and manufacturer of specialty hyperimmune products that demonstrates how government partnerships and not-for-profit supply agreements can shape production cadence and brand positioning.
-
Emerging biologics developers (e.g., Immuron) — clinical-stage entrants who have recently cleared investigational filings and who represent the primary source of category innovation over the forecast horizon.
Collectively, these company dynamics show a market driven as much by manufacturing and distribution playbooks as by pure clinical differentiation.
Recent, high-impact developments (implications)
-
Yield-enhancement approvals are a game-changer: regulators accepting novel production processes compress capital intensity and enable incumbents to generate more output from existing plasma pools. Strategically, this increases returns to scale and raises the bar for new greenfield capacity investments.
-
Clinical progress on pathogen-targeted hyperimmune candidates opens new indication tailwinds. Programs moving into mid-stage trials (and those with expanded pediatric or immunocompromised labels) will become focal points for partnership and licensing activity in 2026.
-
Not-for-profit production agreements with public-health agencies can stabilize supply for critical products but also create commercial blind spots for private players; companies must model both the reputational and margin impacts of such commitments.
-
Commercial partnerships for novel delivery systems (e.g., subcutaneous formulations) are reshaping channel economics and payer negotiations — and will be a critical determinant of uptake in outpatient and home-infusion settings.
Strategic imperatives for leaders in 2026
-
Prioritize yield and capacity actions: quantify how incremental yield improvements affect your unit economics and market share potential. In many scenarios, modest yield gains deliver outsized free cash flow improvements.
-
Lock down supply and flexibility: diversify plasma procurement, secure capacity through CMOs and include performance-linked clauses to protect against demand shocks.
-
Pursue selective label and formulation expansions: clinical investments that enable pediatric or immunocompromised indications, or more convenient delivery routes, materially expand addressable patients and bargaining power with payers.
-
Adopt an outcomes-based GTM for hospital and public-health accounts: combine evidence generation with patient-support services to mitigate payer resistance and accelerate formulary placement.
-
Design M&A with regulatory and capacity contingencies baked in: valuation models must stress-test integration timelines and the risk of production ramp delays.
How to use this research now
-
Strategy teams: use our scenario models to stress-test portfolio roadmaps and 2026 capital plans under alternate supply and regulatory outcomes.
-
Commercial leaders: extract the go-to-market playbooks and payer-approach templates to accelerate roll-out for any label expansions in your pipeline.
-
BD and Corporate Development: apply our comparative company profiles and deal-scenario valuation matrices to prioritize targets and structure contingent consideration linked to manufacturing and regulatory milestones.
Conclusion — the value proposition of the full report
PW Consulting’s complete Hyperimmune Globulins market study combines granular, model-backed forecasts with executable playbooks — the kind of intelligence that turns a growth-rate headline into concrete investment and commercialization choices. The market’s projected expansion to the high single-digit hundreds of millions by 2032 (from a 2025 base near USD 1.8 billion) is meaningful, but the real value lies in understanding how manufacturing yields, label expansions, and partnership architectures will redistribute returns within the market.
This preview intentionally leaves out transaction-level segment tables and regional/application splits to preserve analytical exclusivity. Accessing the full report provides the confidential segmentation, interactive models, and deal-ready exhibits necessary for high-stakes 2026 decision-making. PW Consulting stands ready to convene a tailored executive briefing and workshop to translate the findings into a prioritized 18-month action plan for your organization.
For detailed analysis of this topic, please visit the official page: Hyperimmune Globulins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Perlite & Vermiculite Market to Reach USD 6.30B by 2032, 5.75% CAGR
By pmarketresearch, 2026-07-13
Perlite and Vermiculite Market: Strategic Imperatives for 2026 — PW Consulting Preview
As companies set budgets and capital priorities for 2026, the expanded perlite and exfoliated vermiculite complex presents a mix of steady demand, material-specific technical challenges, and opportunity windows for firms that move with speed and clarity. PW Consulting’s new market study — anchored to a 2025 base year and projecting through 2032 — synthesizes historical behavior (2020–2025) with forward-looking scenarios (2026–2032). The market is forecast to expand at a compound annual growth rate (CAGR) of 5.75% over the forecast window. To frame the scale: the global market grew from a multibillion-dollar level in 2020 to an elevated 2025 base, and is anticipated to continue its upward trajectory into the early 2030s. This preview explains why our analysis is strategically material for decisions you must take in 2026, what proprietary insight the full report contains, and how leading players are already positioning themselves.
Perlite and Vermiculite Market
Why 2026 Is a Decision Point
-
Demand stability meets structural change. Longstanding end uses — construction insulation and lightweight aggregates, horticultural substrates, and industrial filtration — continue to underpin baseline demand. Simultaneously, higher-performance applications (precision filtration, engineered lightweight composites) and regulatory pressures (workplace dust control and product stewardship) are driving material differentiation and premiumization.
Perlite and Vermiculite Market -
Supply-side dynamics are granular and site-specific. Perlite and vermiculite are mined, expanded, and processed in localized clusters. Ore quality and processing technology materially affect product performance: for example, crude vermiculite ore typically includes 3–4 percentage points of moisture that affect expansion characteristics during exfoliation — a technical detail that alters yields and product mix at plant level.
Perlite and Vermiculite Market -
Regulatory and trade considerations are non-trivial. Perlite is widely regulated as a “nuisance dust,” requiring consistent compliance investments across jurisdictions. Moreover, expanded perlite and vermiculite are classified under a specific HS code (6806.20), an operational detail that influences customs treatment, duties, and cross-border sourcing strategies.
-
Market structure favors both scale and nimbleness. The industry is fragmented — the three- and five-firm concentration ratios remain low relative to many mineral value chains — which both limits pricing power among global majors and creates acquisition opportunities for firms seeking route-to-market expansion or downstream integration.
What PW Consulting’s Report Delivers (Practical, Executable)
-
Robust market sizing and scenario modeling: historical series (2020–2025), base-year calibrated estimates (2025), and three scenario-led projections through 2032 that stress-test demand against macro shocks, energy price regimes, and policy shifts.
-
Demand-driver analytics: differentiated by application archetypes and value-chain position, with quantified growth levers and elasticity assumptions to help forecast product-specific volumes under alternative adoption curves.
-
Supply-constraint mapping: deposit quality, beneficiation and expansion capacity, and logistic chokepoints mapped to a supplier risk scorecard for near-term (12–18 month) and medium-term (18–36 month) horizons.
-
Price benchmarking and input-cost models: indexed to energy and freight vectors, with sensitivity matrices for ore-grade variation, expansion yield, and milling loss.
-
Commercial playbooks: go-to-market options for producers, tolling and contract-manufacture models for downstream users, and M&A scorecards for acquirers targeting consolidation or capability acquisition.
-
Regulatory and ESG checklists: compliance pathways for nuisance-dust controls, product labeling implications of HS-classification, and practical steps for reducing lifecycle emissions in expansion processing.
-
Operational deep-dive annexes: exfoliation process variables, particle-size control for filtration media, closed-cell expanded product characteristics, and guidance for pilot-scale trials.
Data-Driven Snapshot (Preview)
PW Consulting’s calibrated market series shows consistent expansion from the early 2020s into the mid-decade, with the base-year (2025) reflecting both cyclical recovery in construction and steady growth in horticulture and industrial segments. The forecast path we present to 2032 is driven by a 5.75% CAGR, which implies meaningful growth potential for firms that can align capacity and product quality with evolving end-use requirements. Because this preview intentionally omits granular regional and application splits, the full report contains the detailed breakdowns that underwriting teams and corporate strategists will require to model investment returns or to size M&A targets.
Competitive Landscape — How to Read the Field
-
Global majors vs. regional specialists: Firms such as Imerys (France) exemplify a platform play, investing in product innovation and engineered filter aids. A concentration of capabilities among a handful of global groups coexists with a long tail of specialist processors and miners, particularly in North America, Europe, and parts of Asia and the Mediterranean basin.
-
Service and product differentiation is winning share: Companies that pair basic expanded perlite with application-specific processing (milling to filter-grade size, closed-cell formulations, or horticultural blends) are capturing premium margins. Recent product innovations demonstrate the commercial payoff for precision particle control and brand positioning.
-
Recent movements to note: capacity and capability investments in 2025 indicate where firms expect near-term demand to be strongest — examples include precision filter-aid product launches and new or expanded processing facilities. These moves materially alter regional supply balances and should inform sourcing decisions in 2026.
-
Fragmentation creates acquisition windows: low overall market concentration (three- and five-firm CRs in the mid-20% range) means numerous attractive bolt-on targets exist for companies seeking scale or route-to-market in priority countries. However, successful roll-ups require fast post-acquisition integration of quality control and logistics to avoid margin erosion.
Strategic Playbook for 2026 Executives
-
Prioritize supply-security contracts with tiering by ore quality. Because ore characteristics materially affect expansion yields and product consistency, securing multiple source options reduces operational risk.
-
Invest selectively in downstream differentiation. Opportunities in precision filtration, engineered lightweight systems, and horticultural substrates reward modest R&D and pilot-plant investment.
-
Time capacity investments to demand signals, not sentiment. With a multi-year CAGR in the mid-single digits, capital projects should be phased and include contingency for energy and freight volatility.
-
Leverage regulatory compliance as a commercial asset. Demonstrable controls on dust emissions and product stewardship can shorten procurement cycles with larger industrial buyers and unlock premium contracts.
-
Use M&A to buy capabilities, not just volume. Assets that add proprietary processing (milling to precise particle distributions, closed-cell expansion capability) or established distribution in high-value end markets will outperform low-synergy volume acquisitions.
-
Operationalize traceability and quality analytics. Data-rich production monitoring—tracking ore moisture, expansion yield, and particle-size distributions—reduces returns and supports premium product claims.
Risks and Contingencies to Monitor in 2026
-
Input-cost shocks: energy and freight spikes rapidly erode margins in expansion-intensive processes; hedging and flexible tolling contracts are cost-effective mitigants.
-
Regulatory tightening: tighter dust-control requirements or shifts in classification could necessitate plant retrofits, particularly in jurisdictions raising occupational health standards.
-
Ore variability: site-level differences in moisture and mineralogy impact yields — realistic worst-case yield scenarios should be built into project appraisals.
-
Geopolitical and trade friction: HS-code aligned duty treatments and localized protective measures can change net landed costs faster than capex cycles permit adjustment.
Illustrative Industry Signals (Selective)
-
Product innovation continues to accelerate: premium filter-aid grades and milled perlite products released in 2025 signal buyer willingness to pay for performance enhancements rather than commodity pricing alone.
-
Capacity moves are geographically targeted: new or enlarged processing facilities opened in 2025 show where suppliers are betting on demand concentration; such investments shift regional logistics economics and competitive dynamics.
-
Public production disclosures underscore materiality: disclosed production volumes and values from established regional players provide hard checkpoints against which private company claims should be validated.
Concluding Guidance — How to Use This Preview
This article is intentionally a strategic “preview” — it highlights the analytical lens and executive actions that PW Consulting recommends for 2026 without exposing the granular regional, application, and pricing tables that underpin investment-grade decisions. If your firm is evaluating capacity projects, acquisition targets, or supply contracts in perlite and vermiculite, the full PW Consulting report provides the detailed split-views, price curves, and risk-scored supplier matrices you need to underwrite decisions with confidence.
For companies planning to allocate capital or revise procurement strategies in 2026, time is the critical variable: early movers that align technical capability with proven demand pockets — while effectively managing dust regulation, ore variability, and logistical friction — will convert the underlying mid-single-digit growth trajectory into outsized returns. PW Consulting’s full study delivers the operational detail and scenario-tested recommendations required to make those calls.
For detailed analysis of this topic, please visit the official page: Perlite and Vermiculite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plywood market to soar from USD 10,100M (2025) to USD 14,100M by 2032
By pmarketresearch, 2026-07-13
Plywood Market 2026: Strategic Imperatives for Leaders — A PW Consulting Preview
As senior advisors to boards and chief procurement officers across the built-environment and industrial goods sectors, PW Consulting presents a focused preview of our forthcoming Plywood Market research. Anchored on a 2025 base year and a 2026–2032 forecast horizon, the study quantifies trends that will shape sourcing, capital planning, product strategy, and trade-risk management through the rest of the decade. In brief: the global plywood market reached approximately USD 10.1 billion in 2025 and, with a 2026–2032 compound annual growth rate of 5.21%, is on a trajectory that takes it toward the low-to-mid USD 14 billion range by 2032. This preview highlights the strategic takeaways senior executives must act on in 2026, while preserving the granular segmentation tables and proprietary models that are available in the full report.
Plywood Market
Why this study matters in 2026
-
Timing: 2026 is a pivot year. Macroeconomic normalization after pandemic-era shocks, a renewed wave of industrial capital investment, and heightened trade policy activity mean organizations must re-evaluate supply, cost and market access assumptions that have underpinned plywood strategies since 2020.
Plywood Market -
Supply-chain fragility meets concentrated risk: Raw-material price volatility and evolving trade measures are escalating input-cost uncertainty for manufacturers and specifiers. Our analysis isolates the precise transmission mechanisms from lumber markets to plywood pricing and profitability—essential for near-term contract renegotiations.
Plywood Market -
Strategic positioning vs. operational execution: Beyond headline growth, value is being captured by firms that combine scale with operational modernization, differentiated product portfolios (including engineered and decorative variants), and resilient sourcing strategies that hedge tariff and freight shocks.
-
Actionable intelligence for capital allocation: Whether to expand veneer capacity, retrofit drying kilns, or pursue bolt-on acquisitions depends on demand mix, cost curves, and regulatory scenarios—each of which we quantify across multiple plausible futures in the report.
Key market signals PW Consulting highlights
-
Measured but consistent market expansion: The market’s mid-single-digit CAGR through 2032 reflects structural demand from construction and furniture manufacturing, tempered by recycling and substitution pressures in packaging and non-structural applications.
-
Cost push from upstream lumber: Lumber price upticks have transmitted to plywood production costs. Short-term spikes in framing lumber feed into input cost scenarios that materially affect thin-margin product lines and spot-market supply.
-
Trade policy volatility: Recent preliminary determinations by authorities on imports from multiple Asian suppliers have introduced a new layer of trade-risk for buyers and exporters. Expect rapid re-routing of flows, near-term price dislocations, and heightened administrative risk in sourcing decisions.
-
Capex and technology investments: Leading producers are investing to modernize veneer and plywood lines, improve thermal efficiency, and accelerate specialty-product launches (including bio-based adhesives), shifting the competitive frontier toward higher-mix, lower-cost operations.
-
Market fragmentation with growing top-tier influence: The competitive landscape remains neither fully consolidated nor atomized. A handful of large global producers co-exist with regional specialists, which creates opportunities for strategic partnerships and targeted M&A.
What the PW Consulting Plywood Market Report delivers (practical, executable content)
-
Transparent market sizing and forecast methodology — Our base-year accounting (2020–2025 historical series) and 2026–2032 projection framework are documented step-by-step so clients can test alternate assumptions. We provide topline market values and scenario outputs tied to demand drivers, not just point estimates.
-
Scenario-based financial models — Interactive templates model margin sensitivity to wood-price swings, freight-cost variability, and selected trade-policy outcomes. These are built for CFOs and commercial leaders to stress-test pricing strategies and capital projects.
-
Supplier and capacity maps — Proprietary mapping of production nodes, logistics chokepoints, and certification footprints supports sourcing redesigns and resilience planning. The full report contains GIS-ready overlays and supplier-contact tooling.
-
Regulatory impact trajectories — We model the operational and margin impacts of active and potential countervailing and antidumping measures, and outline tactical responses (e.g., transshipment controls, tariff mitigation strategies, and traceability upgrades).
-
Commercial playbooks — Ready-to-use go-to-market and procurement playbooks for downstream players (builders, OEMs, distributors) and upstream producers, including contract clause language, hedging approaches, and channel-partner scouting criteria.
-
Competitive benchmarking and capability heatmaps — We score major players across manufacturing footprint, product-mix flexibility, sustainability credentials, and digital/operational maturity. This enables quick-gap analysis for investment and partnership decisions.
-
M&A and capex tracker — A real-time register of announced capacity projects, product launches and strategic investments (with timelines and strategic intent), so deal teams can prioritize targets and avoid bidding in heated corridors.
-
Executive dashboards — Condensed KPI sets and board-ready one-pagers that distill implications for strategy, procurement and risk functions.
Competitive landscape — what matters to executives
The plywood competitive set comprises global integrators, regional champions and highly focused exporters. Major industrial groups and specialist producers are pursuing different plays: operational modernization and scale from integrated mills; product differentiation through engineered and sustainable grades; and export-driven strategies from regions with favourable forestry economics. Our report profiles leading firms and evaluates recent strategic moves to clarify where market power and opportunity are converging.
-
Industry leaders: Global manufacturers with integrated supply chains are emphasizing capacity optimization and product breadth to protect margins in cyclical periods. These players are also best positioned to absorb short-term tariff disruptions through diversified sourcing.
-
Regional specialists: Firms focused on hardwood and specialty plywood are leveraging certification and product customization to defend pricing power in cabinetry, millwork and high-end furniture segments.
-
Export-oriented players: Several producers in Asia and Latin America remain cost-competitive on global markets but face increasing trade friction and a pivot toward higher-value product lines to offset duties and freight costs.
Selected recent market developments we analyze in depth include mill modernization projects, new binder chemistries for birch plywood, and an uptick in announced capacity upgrades among North American veneer operations. These moves are reshaping competitive dynamics and accelerating the premiumization of certain plywood grades.
Regulatory and trade dynamics — framing the near-term risk set
-
Trade measures are now a central variable in sourcing decisions. Preliminary administrative determinations affecting imports from multiple producing countries have led to immediate market responses—inventory repositioning, contract term renegotiation, and re-optimization of freight lanes. The full report quantifies the margin and volume impacts across alternative duty scenarios.
-
Import flows changed markedly through 2025 and into early 2026, with notable increases in volumes from certain exporting countries. This movement has been a primary driver behind regulatory scrutiny and is likely to influence downstream supplier selection in 2026.
-
Material-cost pass-through and specification flexibility determine winners and losers in a higher-duty environment. Buyers with flexible specifications or established supplier relationships in multiple regions can mitigate shock exposure; those without must prepare contingency plans.
How senior teams should use this intelligence in 2026
-
Procurement: Re-run category strategies under alternative duty and lumber-price scenarios. Lock in critical volumes where advantage exists; increase the use of shorter contracts and indexed clauses where downside risk is concentrated.
-
Supply-chain design: Diversify sourcing corridors, assess nearshoring for high-value grades, and convert part of inventory policy toward strategic safety stock for critical SKUs.
-
Product and portfolio strategy: Rationalize low-margin SKUs vulnerable to input volatility; accelerate launches of value-added plywood products that command higher margins and lower commoditization risk.
-
Capital planning: Use our capex decision templates to test IRR sensitivity across demand recovery and tariff scenarios, and prioritize investments that reduce unit costs or open premium markets.
-
M&A and partnerships: Screen targets not just on capacity but on certification, specialized product capability, and access to low-cost logs or resin innovations. Strategic bolt-ons can rapidly close capability gaps without the time and cost of greenfield builds.
In closing — why PW Consulting’s report is decision-ready
This preview outlines the strategic contours: a mid-single-digit growth trajectory, heightened input and trade risks, a competitive set retooling through capex and product innovation, and clear levers for creating durable advantage. For executives who must make procurement, investment, or M&A decisions in 2026, the full PW Consulting Plywood Market Report supplies the empirical backbone — detailed regional and application breakouts, granular cost models, and downloadable scenario tools — to make those decisions defensible and repeatable.
To access the complete dataset, methodology appendices, company scorecards, and Excel-based scenario models, please consult the full report at our distribution page. The preview above is intended to establish the analytical framing and strategic uses; the full report contains the granular tables and interactive files your teams will need to execute with confidence.
For detailed analysis of this topic, please visit the official page: Plywood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electrical Discharge Machines (EDM) Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
PW Consulting’s latest EDM market study delivers a decision-grade view for executives planning through 2026 and beyond. Using a base year of 2025 and a historical window covering 2020–2025, the report models the market over a 2026–2032 forecast horizon. At the macro level, the global EDM market reached approximately 1,730 Million USD in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.8% through the forecast period, reaching roughly 2,530 Million USD by 2032. Market concentration is moderate, with the three-largest vendors accounting for approximately 35% of industry sales and the top five about 45% — a structure that creates both bargaining power for leading suppliers and opportunity for focused challengers.
Electrical Discharge Machines (EDM) Market
Why this research matters for 2026 strategic choices
-
Capital allocation and timing: Buyers and manufacturers face trade-offs between upgrading legacy sinker/wire platforms, investing in high-precision micro-drilling capability, or outsourcing from certified specialist shops. Our study highlights the inflection points where investment yields optimal payback given expected volume and product complexity trends.
Electrical Discharge Machines (EDM) Market -
Supplier selection and risk management: With moderate concentration among incumbents, procurement teams must balance price, technology fit, aftermarket support and regulatory readiness. The report provides a supplier evaluation framework tailored to medical-device and aerospace supply chains where compliance is non-negotiable.
Electrical Discharge Machines (EDM) Market -
M&A and partnership screening: For corporates and PE sponsors, the EDM space is attractive for bolt-on consolidation or capability accretions. We identify the operational and commercial KPIs that predict successful integration and value capture without exposing proprietary subsegment tables here.
-
Regulatory positioning: Medical device applications — a growth engine for precision EDM — are governed by standards and regulations that materially affect time-to-market and allowable process windows. Our research links regulatory constraints to unit economics and go/no-go product decisions.
Market dynamics and near-term catalysts
The EDM market’s 2020–2025 trajectory reflects resilient demand for high-precision machining across medical, aerospace and high-end electronics applications. Key structural forces shaping the 2026 landscape include technological evolution in electrode and wire handling, increased adoption of automation and software-enabled process control, and tightening regulatory oversight where EDM is used in critical component manufacturing.
-
Precision medical manufacturing as a demand anchor: Medical device manufacturers continue to rely on EDM for implants, minimally invasive instrument components, and micro-scale features that conventional machining cannot economically deliver. Recent industry activity — including certification updates and regulatory filings — underscores the importance of traceable, validated EDM process chains.
-
Regulatory and certification tailwinds: Several regulatory requirements now explicitly affect EDM operators serving medical supply chains: ISO 13485 certification expectations, application of FDA 21 CFR Part 820 quality-system controls, EU medical-device directives, and MDSAP-related obligations for firms operating across multiple jurisdictions. These rules raise the baseline for shop-floor documentation, change control and supplier audits — shifting procurement decisions toward providers that can demonstrate robust compliance evidence.
-
Supply-side innovation and service models: Manufacturers are pushing integrated solutions — combining machines, consumables, and digital process control — and aftermarket services such as predictive maintenance and qualification-as-a-service. These models change the cost-of-ownership calculus and privilege vendors offering end-to-end validated workflows.
-
Recent market signals: Product communications and certifications from both OEMs and contract manufacturers point to near-term opportunity clusters. Examples include new EDM capability catalogues targeted at surgical instrumentation, regulatory filings that reference EDM-produced components, and ISO/MDSAP certification events at contract EDM shops — all indicating that demand and compliance readiness are aligning.
Competitive landscape — who matters and why
The competitive map combines global OEMs with regional specialists. Leading firms differentiate on precision, process validation, and aftermarket support. Our analysis focuses on the companies that matter to buyers and investors because of their technological depth or channel reach:
-
Makino (Japan) — Known for sinker and wire EDM systems with a strong foothold in medical device machining, particularly implants and precision instruments. Their product mix emphasizes repeatability and validation-ready workflows for regulated manufacturing.
-
GF Machining Solutions (Switzerland) — Offers wire-cutting and sinker EDM platforms targeted at high-precision medical components, with a global service network and industry-oriented process packages that reduce qualification timelines for OEMs.
-
Sodick (Japan) — Specializes in high-precision wire and sinker EDMs, with particular strengths in micro-EDM and process stability, attractive to tier-1 subcontractors serving medical and aerospace customers.
-
Mitsubishi Electric (Japan) — Focused on wire EDM systems designed for extreme accuracy applications; their engineering pedigree and control systems are appealing where tolerance and surface integrity are mission-critical.
-
CHMER (Taiwan) — Competes on value and application breadth across wire-cut and die-sinker machines, often winning cost-sensitive or mixed-product-line contracts.
Across the field, differentiation is less about raw machine horsepower and more about validated process packages, integrated software for process control, and aftermarket qualification services. Given the modest CR3/CR5 concentration, opportunities exist for specialist entrants that can pair technology with regulatory competence.
What the report delivers — a practical toolkit
This study is designed to be directly usable in boardroom decisions and operational planning. Core actionable outputs include:
-
Transparent market-sizing and scenario models (2020–2032) with sensitivity tests for volume, ASP and adoption curves.
-
Investment case templates and capex ROI calculators tailored to wire, sinker and micro-drilling use-cases.
-
Supplier evaluation matrix and scorecards covering technology fit, compliance posture, service SLA and total cost of ownership.
-
Regulatory compliance checklist and recommended audit scripts aligned with ISO 13485, FDA 21 CFR Part 820, MDSAP practices and applicable EU requirements.
-
Technology roadmap and adoption playbook for automation, in-process monitoring and digital twinning to reduce qualification time and scrap.
-
M&A screening criteria and integration playbooks for acquiring shops or capability bolt-ons without disrupting existing validated processes.
-
Case studies demonstrating supplier transitions, process re-qualification, and rapid capacity ramp strategies for regulated programs.
To respect competitive sensitivity and preserve the trailer-style dynamic of the brief, we showcase methodology and findings here while intentionally withholding granular subsegment tables, regional splits and raw transaction-level datasets. Those detailed data and appendices are available via the full report on our site.
How procurement, operations and strategy teams should use the analysis in 2026
-
Q1 — Rapid supplier triage: Use our supplier scorecards to narrow candidate lists to those meeting regulatory and technical thresholds. Prioritize firms with demonstrated ISO 13485/MDSAP certificates when medical-device qualification timelines are tight.
-
Q2 — Capital allocation and pilot projects: Run head-to-head pilot programs using the report’s capex ROI templates. Validate not only machine performance but also change-control and documentation processes required for device approvals.
-
Q3 — Scale and compliance lock-in: For designs entering scale production, leverage the process-validation playbook to minimize rework during regulatory submissions. Ensure supplier SLAs include traceability and retention of process records.
-
Ongoing — Strategic portfolio decisions: Use our scenario models to test insourcing vs. outsourcing strategies under different demand and ASP growth paths, and to stress-test integration plans for any planned acquisitions.
Final perspective and next steps
The EDM market presents a rare combination: technologically mature platforms undergoing incremental innovation at a time when regulatory and product complexity are increasing demand for validated, high-precision capability. For decision-makers setting 2026 priorities, the questions are tactical (which machines, which suppliers, when to qualify) and strategic (where to build proprietary capability, when to buy). PW Consulting’s report converts those questions into executable options — from procurement scorecards to acquisition checklists — while preserving the proprietary raw data in the full deliverable.
If your 2026 plan depends on minimizing qualification risk, optimizing total cost of ownership, or capturing value through consolidation, the full report contains the segment-level analytics, regional models and supplier benchmarking you’ll need to proceed confidently. For access to the complete datasets, appendices and customizable decision tools, please visit the source page to purchase the full study or to commission a tailored workshop with our industry specialists.
For detailed analysis of this topic, please visit the official page: Electrical Discharge Machines (EDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com