

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: IGBT Market Poised for 6.88% CAGR to USD 12.97B by 2032

IGBT Market 2026 Strategic Preview: Essential Insights for Executive Decision-Making
As Pw Consulting’s Chief Industry Analyst, I present a focused strategic preview of our IGBT Market research—designed to inform capital allocation, product strategy, supply-chain posture, and M&A prioritization for 2026. This preview synthesizes the most consequential findings from our full study (base year 2025) and lays out how the market trajectory and near-term industry dynamics translate into practical, boardroom-ready choices. To preserve the value of our proprietary segmentation and model, this article deliberately omits granular regional and application breakdowns; the full report contains the detailed tables, scenario outputs, and downloadable model that underpin the guidance below.
IGBT Market
Market Trajectory: A Data-Driven Snapshot
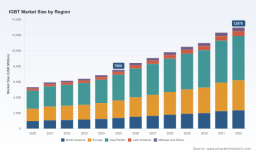
The IGBT market has entered a sustained growth phase. Our market model tracks a recovery and accelerated adoption curve from 2020 through the forecast horizon. In aggregate terms (USD, revenue in Million), the industry grew from approximately 5.3 billion in 2020 to 7.56 billion in 2025. Under our base forecast, the market expands to roughly 8.43 billion in 2026 and continues on a compound annual growth path to reach an estimated 12.97 billion by 2032. The compound annual growth rate embedded in the forecast period is 6.88%.
IGBT Market
Two implications are immediate for 2026 planning: first, absolute demand for higher-performance power modules and smart IGBT solutions is rising; second, the growth profile creates incentives for both incumbents and new entrants to accelerate product roadmaps and supply-chain commitments now, rather than waiting for fully realized end-market pull.
IGBT Market
Why 2026 Is a Strategic Inflection Point
- Momentum meets scarcity: Rising end-demand is colliding with supply constraints in critical upstream inputs. Notably, Si wafer availability has tightened—pushing lead times for intelligent power modules beyond 16 weeks in many cases. For manufacturers and OEMs, this means lead-time risk must be managed proactively through dual-sourcing, priority agreements, and localized safety-stock strategies.
- Technology transition windows: Product launches and sampling activity from major suppliers (e.g., new 400 V / 800 V chips for EV platforms, and next‑generation 1.2 kV modules for industrial and renewable segments) indicate a narrowing window to validate and adopt next‑gen IGBT architectures. OEMs who defer migration risk being locked into longer lifecycles of legacy parts or facing retrofit costs.
- Regulatory and policy drivers: Export control regimes and accelerated renewables deployment are reshaping both supply and demand. Export controls adopted since 2024 add geopolitical complexity to sourcing advanced device-process technologies, while substantial additions to wind and solar capacity in 2025 reinforce long-term demand for inverter-grade IGBT solutions.
Practical Strategic Actions for 2026
Our analysis converts market dynamics into actionable decision levers. For leadership teams preparing budgets and product plans for 2026, prioritize the following:
- Prioritize qualification pipelines: Accelerate qualification cycles for new IGBT families and modules that align to your product roadmap. Given sampling programs and commercial announcements already underway among key suppliers, early engagement will secure engineering slots and mitigate time-to-market risk.
- Secure upstream capacity: Negotiate wafer and packaging capacity commitments with tier-1 suppliers, and evaluate inventory-financing options. Short-term increases in safety stock can be value-accretive when lead times exceed 16 weeks for critical module families.
- Match product tiers to margin pools: Layer your portfolio decisions—reserve R&D and high-cost packaging investments for segments where differentiation yields durable margin advantage (e.g., electric powertrains and industrial motion control). For high-volume, lower-margin applications, optimize cost through standardized module architectures and contract manufacturing partnerships.
- Scenario-proof procurement: Build flexible buying strategies with triggers tied to observed wafer-price and lead-time shocks. Contingency contracts that can be activated based on objective thresholds protect production without permanently inflating working capital.
- Reassess M&A and JV priorities: The market concentration metrics indicate meaningful scale advantages. Strategic acquisitions that add complementary module capabilities, local manufacturing footprint, or access to vertically integrated wafer capacity can rapidly move an acquirer up the curve. Target prioritization should weight technology fit, shortening of qualification timelines, and access to regulated or constrained supply chains.
Competitive Landscape: Who’s Doing What—and What That Means
The industry remains led by established power-electronics players that combine device physics, packaging, and system know-how. Market concentration is material: the combined share of the three largest firms is approaching half the market, while the top five firms together control a clear majority—underscoring scale economies in R&D, production, and channel access.
- Infineon Technologies AG — A global leader with deep product families spanning CoolSiC and hybrid drive modules. Their recent announcements targeting EV electric drive trains signal continued prioritization of automotive and high-efficiency drivetrain platforms. For customers, Infineon represents a strategic partner for high-voltage and silicon-carbide transitions.
- ON Semiconductor Corporation — Focused on flexible portfolios of standard and custom IGBTs across EV and industrial segments. Their strength lies in delivering tailored solutions at scale—a model attractive to OEMs needing differentiated electrical or packaging requirements without starting from silicon design.
- Mitsubishi Electric Corporation — Long-standing traction and industrial module supplier; recent sampling of new 1.2 kV LV100 and NX-type modules underscores their push into higher-efficiency industrial and renewable applications. Mitsubishi’s cadence of sample-to-production timelines is an important signal for OEM roadmaps in 2026.
- Fuji Electric & ROHM Semiconductor — Both combine aggressive device iterations (e.g., RC-IGBT and field-stop trench technologies) with targeted compact packaging—well suited to xEV and inverter segments where thermal and size trade-offs are critical.
- Magnachip, STMicroelectronics & Toshiba — Each leverages niche strengths: Magnachip’s recently launched 650 V/1200 V discrete series for solar and storage (late 2025) expands options for inverter OEMs; ST’s packaging and automotive focus play to high-efficiency conversion trends; Toshiba’s traction modules keep it relevant in rail and heavy industrial sectors.
For corporate strategists, the takeaway is clear: supplier selection in 2026 is not a binary technical choice—it is a strategic decision that shapes supply‑chain resilience, product differentiation, and total lifecycle costs.
Supply-Chain & Policy Risks That Will Drive Boardroom Decisions
- Upstream material constraints: Si wafer scarcity has moved from a tactical headache to a strategic lever. Where possible, secure capacity via multi-year agreements, explore wafer-substitute roadmaps if applicable to your designs, and prioritize product architectures that tolerate alternate supply routes.
- Export controls and technology access: Post-2024 export-control regimes add friction to acquiring advanced process technologies and certain control electronics. Firms pursuing aggressive silicon or packaging roadmaps must embed geopolitical risk assessments into engineering-sourcing trade-offs and consider local development or licensing strategies where necessary.
- Demand-policy coupling: Rapid renewables deployment and energy-policy incentives materially alter end-market sizing for inverters and storage. Expect policy-driven procurement cycles (e.g., utility tenders) to periodically amplify demand—requiring flexible manufacturing response plans.
What the Full Report Contains (Practical, Executable Deliverables)
The complete PW Consulting IGBT Market study provides a suite of deliverables structured for rapid operationalization by commercial, engineering, and corporate development teams. Highlights include:
- A transparent, downloadable market model (historical 2020–2025; forecast 2026–2032) with scenario toggles for adoption pace, wafer-price shocks, and policy-driven demand surges.
- A supplier risk matrix quantifying lead-time exposure, technology maturity, and geopolitical sensitivity—mapped to suggested mitigation actions and contract structures.
- Segment-level pricing curves and margin waterfall diagnostics to guide product architecture trade-offs and target profitability by application class (note: detailed segment tables are reserved for the full report).
- Competitive profiles and a 12–24 month battle plan for customer engagements with the key vendors discussed above, including procurement playbooks and engineering-qualification checklists.
- M&A screening framework: prioritized acquisition themes, indicative valuation ranges, and integration scorecards tailored to IGBT value chains.
How Executives Should Use This Preview in 2026 Planning
- Investment committees: Use the macro trajectory and concentration metrics to set capital allocation thresholds for capacity expansion, R&D, and inorganic growth. Prioritize investments that close product gaps faster than competitors.
- Product management: Align release calendars to supplier sample windows and prioritize modules that unlock adjacent revenue streams (e.g., electrified mobility and utility-scale inverters).
- Procurement: Convert lead-time intelligence into contracting actions—multi-sourced frameworks, capacity carve-outs, and performance-based penalties to stabilize supply assumptions reflected in 2026 budgets.
- Corporate development: Target small to mid-size acquisitions that provide immediate supply resilience, niche module IP, or local manufacturing footprints—especially where regulatory controls complicate cross-border technology transfer.
Closing: The Strategic Opportunity Ahead
The IGBT market’s projected expansion to roughly 13 billion USD by 2032, coupled with a mid-single-digit CAGR, represents both opportunity and a test of strategic agility. Firms that translate lead-time intelligence, supplier roadmaps, and regulatory shifts into decisive 2026 actions will capture outsized share and margin. Conversely, organizations that treat the market as a steady-state electronics category risk being outmaneuvered by suppliers and competitors better aligned to the next wave of EV, industrial automation, and renewable-power requirements.
For readers seeking the full empirical foundation—detailed regional and application splits, the scenario-ready model, supplier scorecards, and transaction-level M&A screening—please consult the full Pw Consulting IGBT Market report and model on our website. The comprehensive materials provide the granular inputs you need to convert the strategic priorities outlined here into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: IGBT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com