

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Plywood market to soar from USD 10,100M (2025) to USD 14,100M by 2032

Plywood Market 2026: Strategic Imperatives for Leaders — A PW Consulting Preview
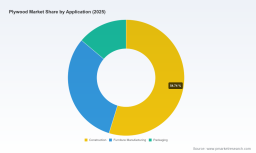
As senior advisors to boards and chief procurement officers across the built-environment and industrial goods sectors, PW Consulting presents a focused preview of our forthcoming Plywood Market research. Anchored on a 2025 base year and a 2026–2032 forecast horizon, the study quantifies trends that will shape sourcing, capital planning, product strategy, and trade-risk management through the rest of the decade. In brief: the global plywood market reached approximately USD 10.1 billion in 2025 and, with a 2026–2032 compound annual growth rate of 5.21%, is on a trajectory that takes it toward the low-to-mid USD 14 billion range by 2032. This preview highlights the strategic takeaways senior executives must act on in 2026, while preserving the granular segmentation tables and proprietary models that are available in the full report.
Plywood Market
Why this study matters in 2026
-
Timing: 2026 is a pivot year. Macroeconomic normalization after pandemic-era shocks, a renewed wave of industrial capital investment, and heightened trade policy activity mean organizations must re-evaluate supply, cost and market access assumptions that have underpinned plywood strategies since 2020.
Plywood Market -
Supply-chain fragility meets concentrated risk: Raw-material price volatility and evolving trade measures are escalating input-cost uncertainty for manufacturers and specifiers. Our analysis isolates the precise transmission mechanisms from lumber markets to plywood pricing and profitability—essential for near-term contract renegotiations.
Plywood Market -
Strategic positioning vs. operational execution: Beyond headline growth, value is being captured by firms that combine scale with operational modernization, differentiated product portfolios (including engineered and decorative variants), and resilient sourcing strategies that hedge tariff and freight shocks.
-
Actionable intelligence for capital allocation: Whether to expand veneer capacity, retrofit drying kilns, or pursue bolt-on acquisitions depends on demand mix, cost curves, and regulatory scenarios—each of which we quantify across multiple plausible futures in the report.
Key market signals PW Consulting highlights
-
Measured but consistent market expansion: The market’s mid-single-digit CAGR through 2032 reflects structural demand from construction and furniture manufacturing, tempered by recycling and substitution pressures in packaging and non-structural applications.
-
Cost push from upstream lumber: Lumber price upticks have transmitted to plywood production costs. Short-term spikes in framing lumber feed into input cost scenarios that materially affect thin-margin product lines and spot-market supply.
-
Trade policy volatility: Recent preliminary determinations by authorities on imports from multiple Asian suppliers have introduced a new layer of trade-risk for buyers and exporters. Expect rapid re-routing of flows, near-term price dislocations, and heightened administrative risk in sourcing decisions.
-
Capex and technology investments: Leading producers are investing to modernize veneer and plywood lines, improve thermal efficiency, and accelerate specialty-product launches (including bio-based adhesives), shifting the competitive frontier toward higher-mix, lower-cost operations.
-
Market fragmentation with growing top-tier influence: The competitive landscape remains neither fully consolidated nor atomized. A handful of large global producers co-exist with regional specialists, which creates opportunities for strategic partnerships and targeted M&A.
What the PW Consulting Plywood Market Report delivers (practical, executable content)
-
Transparent market sizing and forecast methodology — Our base-year accounting (2020–2025 historical series) and 2026–2032 projection framework are documented step-by-step so clients can test alternate assumptions. We provide topline market values and scenario outputs tied to demand drivers, not just point estimates.
-
Scenario-based financial models — Interactive templates model margin sensitivity to wood-price swings, freight-cost variability, and selected trade-policy outcomes. These are built for CFOs and commercial leaders to stress-test pricing strategies and capital projects.
-
Supplier and capacity maps — Proprietary mapping of production nodes, logistics chokepoints, and certification footprints supports sourcing redesigns and resilience planning. The full report contains GIS-ready overlays and supplier-contact tooling.
-
Regulatory impact trajectories — We model the operational and margin impacts of active and potential countervailing and antidumping measures, and outline tactical responses (e.g., transshipment controls, tariff mitigation strategies, and traceability upgrades).
-
Commercial playbooks — Ready-to-use go-to-market and procurement playbooks for downstream players (builders, OEMs, distributors) and upstream producers, including contract clause language, hedging approaches, and channel-partner scouting criteria.
-
Competitive benchmarking and capability heatmaps — We score major players across manufacturing footprint, product-mix flexibility, sustainability credentials, and digital/operational maturity. This enables quick-gap analysis for investment and partnership decisions.
-
M&A and capex tracker — A real-time register of announced capacity projects, product launches and strategic investments (with timelines and strategic intent), so deal teams can prioritize targets and avoid bidding in heated corridors.
-
Executive dashboards — Condensed KPI sets and board-ready one-pagers that distill implications for strategy, procurement and risk functions.
Competitive landscape — what matters to executives
The plywood competitive set comprises global integrators, regional champions and highly focused exporters. Major industrial groups and specialist producers are pursuing different plays: operational modernization and scale from integrated mills; product differentiation through engineered and sustainable grades; and export-driven strategies from regions with favourable forestry economics. Our report profiles leading firms and evaluates recent strategic moves to clarify where market power and opportunity are converging.
-
Industry leaders: Global manufacturers with integrated supply chains are emphasizing capacity optimization and product breadth to protect margins in cyclical periods. These players are also best positioned to absorb short-term tariff disruptions through diversified sourcing.
-
Regional specialists: Firms focused on hardwood and specialty plywood are leveraging certification and product customization to defend pricing power in cabinetry, millwork and high-end furniture segments.
-
Export-oriented players: Several producers in Asia and Latin America remain cost-competitive on global markets but face increasing trade friction and a pivot toward higher-value product lines to offset duties and freight costs.
Selected recent market developments we analyze in depth include mill modernization projects, new binder chemistries for birch plywood, and an uptick in announced capacity upgrades among North American veneer operations. These moves are reshaping competitive dynamics and accelerating the premiumization of certain plywood grades.
Regulatory and trade dynamics — framing the near-term risk set
-
Trade measures are now a central variable in sourcing decisions. Preliminary administrative determinations affecting imports from multiple producing countries have led to immediate market responses—inventory repositioning, contract term renegotiation, and re-optimization of freight lanes. The full report quantifies the margin and volume impacts across alternative duty scenarios.
-
Import flows changed markedly through 2025 and into early 2026, with notable increases in volumes from certain exporting countries. This movement has been a primary driver behind regulatory scrutiny and is likely to influence downstream supplier selection in 2026.
-
Material-cost pass-through and specification flexibility determine winners and losers in a higher-duty environment. Buyers with flexible specifications or established supplier relationships in multiple regions can mitigate shock exposure; those without must prepare contingency plans.
How senior teams should use this intelligence in 2026
-
Procurement: Re-run category strategies under alternative duty and lumber-price scenarios. Lock in critical volumes where advantage exists; increase the use of shorter contracts and indexed clauses where downside risk is concentrated.
-
Supply-chain design: Diversify sourcing corridors, assess nearshoring for high-value grades, and convert part of inventory policy toward strategic safety stock for critical SKUs.
-
Product and portfolio strategy: Rationalize low-margin SKUs vulnerable to input volatility; accelerate launches of value-added plywood products that command higher margins and lower commoditization risk.
-
Capital planning: Use our capex decision templates to test IRR sensitivity across demand recovery and tariff scenarios, and prioritize investments that reduce unit costs or open premium markets.
-
M&A and partnerships: Screen targets not just on capacity but on certification, specialized product capability, and access to low-cost logs or resin innovations. Strategic bolt-ons can rapidly close capability gaps without the time and cost of greenfield builds.
In closing — why PW Consulting’s report is decision-ready
This preview outlines the strategic contours: a mid-single-digit growth trajectory, heightened input and trade risks, a competitive set retooling through capex and product innovation, and clear levers for creating durable advantage. For executives who must make procurement, investment, or M&A decisions in 2026, the full PW Consulting Plywood Market Report supplies the empirical backbone — detailed regional and application breakouts, granular cost models, and downloadable scenario tools — to make those decisions defensible and repeatable.
To access the complete dataset, methodology appendices, company scorecards, and Excel-based scenario models, please consult the full report at our distribution page. The preview above is intended to establish the analytical framing and strategic uses; the full report contains the granular tables and interactive files your teams will need to execute with confidence.
For detailed analysis of this topic, please visit the official page: Plywood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com