

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Total Station Theodolites Market Poised for 5.31% CAGR Through 2032
By pmarketresearch, 2026-07-13
Total Station Theodolites Market — Strategic Imperatives for 2026
Executive summary
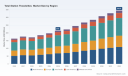
As organizations plan capital allocation, product development and channel strategies for 2026, a clear, actionable view of the Total Station Theodolites market is essential. Our latest PW Consulting market study frames that view with a multi-year perspective: the global market expanded from a 2020 baseline of roughly USD 163 million to an estimated USD 215 million in 2025, and—under our base forecast—continues to grow at a compound annual growth rate (CAGR) of about 5.31% over the 2026–2032 horizon. By 2032, total market revenues are projected to exceed USD 340 million. These headline numbers capture the market’s steady recovery and structural growth driven by technology adoption, productivity demands in construction and mining, and rising preferences for automated surveying workflows.
Total Station Theodolites Market
Why this study matters for 2026 decision-makers
Executives face three simultaneous pressures entering 2026: accelerate ROI from deployed capital, defend margins against rising component and logistics costs, and convert technology-led differentiation into sustainable market share. The PW Consulting study translates broad market momentum into specific, prioritized actions:
Total Station Theodolites Market
- It quantifies the pace of adoption for key technologies—robotic automation, integrated scanning and on-device AI—so product roadmap investments can be sized to match realistic payback windows.
- It frames competitive intensity and concentration dynamics that inform whether to adopt offensive M&A, targeted alliances, or scale-up through channel penetration strategies.
- It provides scenario-tested forecasts and operational benchmarks that procurement, product, and sales leaders can use to stress-test 2026 budgets and pricing assumptions.
What this report delivers — practical components
PW Consulting’s Total Station Theodolites market study is organized for immediate operational use by strategy, product and commercial teams. Key deliverables include:
Total Station Theodolites Market
- Top-down and bottom-up market sizing (base year 2025, forecast 2026–2032) with sensitivity analyses for alternative demand paths.
- Technology and product mapping that aligns device capabilities (manual, robotic, scanning, edge-AI) to typical buyer pain points and ROI levers in field operations.
- A competitive playbook: manufacturer profiles, go-to-market approaches, strengths/weaknesses and recent strategic moves.
- Commercial guidance for pricing, bundling (hardware + software + services), and lifecycle revenue models including service, calibration and spare-parting economics.
- Supply-chain risk assessment addressing component sourcing (notably aluminum structural parts), logistics bottlenecks and quality control vulnerabilities.
- Regulatory and standards impact analysis relevant to procurement and compliance (including ISO guidance for geodetic/surveying instruments).
- Investor-grade appendices: forecast spreadsheets, unit economics templates, and an M&A target shortlist based on capability gaps and geographic access.
Market dynamics to watch in 2026
The market’s forward momentum is not uniform—structural dynamics are reshaping competitive advantage:
- Technology adoption: Edge AI and on-device processing (illustrated by recent product introductions) are shifting value from pure hardware accuracy to data-velocity and field productivity. Devices that can preprocess or flag anomalies on-site materially reduce post-processing costs and survey cycles.
- Automation and labor economics: Robotic total stations enable single-operator workflows that compress labor requirements. This is altering procurement criteria for large contractors and survey service firms that prioritize total cost of ownership over initial capex.
- Material and component trends: Aluminum remains the primary structural material; suppliers exposed to commodity swings must hedge procurement or find design levers to reduce weight without compromising rigidity.
- Standards and compliance: ISO definitions and measurement standards continue to shape procurement specifications. Compliance credentials are a de facto gate for public-sector tenders and large infrastructure projects.
- Channel and services: As devices become more software-intensive, aftermarket services—firmware updates, cloud data ingestion, calibration, and training—represent expanding revenue pools and retention levers.
Competitive landscape — five players driving the agenda
The market exhibits moderate fragmentation: the top-three vendors together account for a modest share of demand, leaving meaningful room for differentiated players and new entrants. That competitive structure favors both focused niche plays and alliance-driven scale strategies.
- Leica Geosystems (Heerbrugg, Switzerland) — Leica continues to lead with integrated offerings that blend high-precision angle measurement, EDM and edge AI on selected models. Its recent introduction of an AI-enhanced robotic unit underlines a strategy of embedding intelligence on-device to deliver productivity gains in complex field conditions. Expect Leica to further monetize software and data services adjacent to hardware.
- Trimble Inc. (Sunnyvale, California) — Trimble’s focus on advanced robotic systems and machine control integrations positions it to capture larger, system-level procurements. Its robotic models emphasize automation features (e.g., autolock) and scanning convergence, suiting contractors seeking end-to-end alignment with machine guidance and BIM workflows.
- Topcon Corporation (Tokyo, Japan) — Topcon pursues hybrid positioning and machine-control synergies. Its product strategy centers on integrating surveying instruments within construction site ecosystems—an attractive proposition for firms that prioritize single-vendor simplicity for machine control, guidance and as-built capture.
- Hi-Target Surveying Instrument Co., Ltd. (Shenzhen, China) — Hi-Target’s competitive edge lies in cost-efficient platforms and rapid local-market service. Its robotic and manual ranges focus on value-conscious segments and fast aftermarket support in regions where price-performance ratios are decisive.
- South Surveying & Mapping Instrument Co., Ltd. (Dalian, China) — South is sharpening its brand through regional engagement—user conferences and trade-show visibility—and expanding its product stack with models tuned for regional buyer requirements. Their recent industry engagement points to a distribution- and service-led growth playbook.
Recent strategic moves — what they reveal
Product launches and industry engagement in late 2025 and early 2026 highlight several themes: first, vendors are racing to embed AI and scanning into ruggedized field units; second, trade shows and user events are being used to accelerate service and channel conversations rather than pure product promotion. These behaviors indicate that 2026 will be a year of commercialization—moving innovations from laboratory demonstrations to field-deployable, revenue-generating systems.
Strategic choices for 2026
We recommend executives prioritize choices across three vectors:
- Product strategy: Prioritize modular architectures that allow customers to add scanning, AI and connectivity features over time. This reduces customer switching friction and preserves upgrade revenue.
- Commercial model: Shift toward bundling hardware with recurring software and service contracts. Financing and buyback programs can unlock adoption among mid-sized contractors constrained by CAPEX cycles.
- Go-to-market and partnerships: For incumbents, defend core markets with strengthened service networks and digital platforms. For challengers and new entrants, seek partnerships with machine-control or data-platform providers to create integrated offerings without the capex of full-stack development.
Risk and mitigations
Key risks for 2026 include component cost inflation (aluminum and precision optics), execution risks on software delivery, and competitive compression from low-cost platforms. Mitigation tactics include multi-sourcing critical materials, staging feature rollouts to reduce integration risk, and establishing regional service hubs to shorten lead times and improve perceived value.
How PW Consulting supports your 2026 planning
This study is designed as a decision-support toolkit for executives who must convert market signals into executable plans in 2026. Clients receive:
- Customized scenario forecasts and unit-volume models calibrated to your product mix and channel footprint.
- A competitive impact matrix that maps each major vendor’s likely moves against specific market segments and price bands.
- Go-to-market playbooks for launching new models, optimizing post-sale services and pricing recurring-revenue offers.
- An M&A and partnership shortlist tailored to capability gaps and regional expansion priorities.
Note: this article intentionally highlights strategic conclusions and market-level metrics while reserving the detailed regional, application and segment-level revenue splits for the full report. Those finer-grained tables and the underlying data models are accessible through the report landing page and are essential for tactical planning such as channel-by-channel sales targets, SKU-level P&L and regional deployment sequencing.
Final perspective — where to place your 2026 bet
The Total Station Theodolites market in 2026 sits at an inflection between hardware-led competition and solutions-driven differentiation. The macro math is straightforward—the market is growing at a mid-single-digit CAGR with ample room for players that can combine reliable precision hardware, domain-focused software and a service-centric commercial model. For firms deciding where to allocate investment in 2026, the highest-return moves will be those that accelerate field productivity for end-customers (through AI, automation, and integrated workflows) while creating recurring revenue through services and data platforms.
PW Consulting’s report converts these strategic imperatives into executable roadmaps. For teams that need the granular data and actionable templates to translate strategy into 2026 budgets and Q1 initiatives, the full dataset and annex materials are available in the report package.
For detailed analysis of this topic, please visit the official page: Total Station Theodolites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Animal Feed Enzymes Market to Reach USD 1,820 Million by 2025 (6.0% CAGR)
By pmarketresearch, 2026-07-13
Animal Feed Enzymes Market — Strategic Briefing for 2026
Market snapshot (what the numbers tell us)
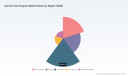
By the 2025 base year this market had evolved from a niche additives category into a strategic lever for feed efficiency and sustainability. Our topline metrics anchor the analysis: global revenues rose steadily through the early 2020s, with the addressable market reaching approximately USD 1,820 Million in 2025. Under the baseline forecast (our 2026–2032 projection set), the market expands at a mid-single-digit pace — a 6.0% compound annual growth rate — reaching a materially larger market by 2032. The near-term step‑change between 2025 and 2026 is visible in our forecasting model and reflects both product upgrades and sharp adoption in higher-value feed formulations.
Animal Feed Enzymes Market
These headline figures hide important internal dynamics — consolidation among incumbents, premiumisation of next‑generation enzyme grades, and higher volatility in inclusion rates linked to fluctuating feed-ingredient prices. The report quantifies these interactions and translates them into actionable scenarios for corporate planning in 2026.
Animal Feed Enzymes Market
Why this research matters for 2026 decision-makers
- Investment allocation: Decide whether to prioritise R&D for next-gen phytases, expand manufacturing capacity, or pursue M&A to close portfolio gaps.
- Commercial strategy: Set pricing architecture that captures value from premium enzyme grades while protecting share in price-sensitive segments.
- Procurement optimisation: Re-design supplier contracts and hedging strategies to limit exposure to raw-material swings that materially affect enzyme use.
- Regulatory & market access: Sequence product launches in regions with lengthier clearance processes to maximise first-mover returns on novel enzyme technologies.
What the full report delivers — operationally usable intelligence
This is not a high-level narrative. The report is designed for immediate operational adoption across strategy, commercial, and technical functions. Key deliverables include:
Animal Feed Enzymes Market
- Addressable-market maps: granular demand models by feed formulation archetype and livestock nutrition strategy (note: public summary hides the line-item splits; full dataset available in the source report).
- Price-elasticity and inclusion-rate models: dynamic sensitivity analyses showing how enzyme uptake shifts under different corn/soybean price scenarios.
- Regulatory pathway playbooks: EFSA/other-region decision timelines, dossier requirements, and go‑to‑market sequencing to reduce approval risk for next‑gen enzyme grades.
- Supplier scorecards and procurement templates: capability matrices, manufacturing footprints, service-level KPIs and contract clauses to mitigate supply disruptions.
- Product and technology benchmarking: head-to-head profiles of commercial enzyme lines, stability under pelleting temperatures, and differential value capture potential.
- M&A & partnership playbooks: valuation frameworks, integration checklists, and a shortlist of target archetypes by strategic objective (capacity, portfolio, channel).
- Scenario planning tools: three central market scenarios (base, accelerated premium adoption, and raw-material shock) with P&L and working-capital implications.
- Implementation roadmaps: 30/90/180-day action plans tailored to manufacturers, feed formulators and distributors.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three firms account for a meaningful share of market revenue, and the top five extend that dominance. This structure creates both barriers and opportunities — incumbents can leverage scale, but pockets of openness remain for differentiated technology or commercial models.
- Novonesis: Following a material acquisition completed in 2025, Novonesis enlarged its enzyme platform and distribution reach. The transaction reshaped route-to-market dynamics and raises the stakes in consolidation-driven strategy.
- BASF SE: While a major technology and distribution player, BASF’s strategic review of its feed-enzyme business signals potential portfolio realignment that could create windows for competitors or new entrants.
- Adisseo: With regulatory approvals for next-generation phytase technology and demonstrated pellet stability, Adisseo is capturing premium positions in feed formulators aiming for higher nutrient release and sustainability claims.
- Kemin, Cargill, Novus, AB Enzymes, IFF, Alltech and DuPont: These firms form a competitive cohort with differentiated strengths — multi‑enzyme blends, strong distribution channels, or proprietary enzyme platforms — and remain active in product launches and regional expansions.
Collectively these players set market norms on pricing, distribution models and technical support packages. The CR3 and CR5 metrics in our report quantify how concentrated influence is at the top and the practical implications for pricing power and innovation diffusion.
Market dynamics and headwinds to factor into 2026 strategy
- Premiumisation of enzyme grades: Next‑generation phytases and stabilised formulations that survive industrial pelleting are commanding higher price points. Capturing these premiums requires validated feed‑level performance data and a targeted commercial approach.
- Raw-material volatility: Corn and soybean meal price swings change the economics of enzyme inclusion. Procurement teams must align contract design and elasticities to avoid margin erosion when feed prices spike.
- Regulatory complexity: Regional clearance processes differ; earlier approvals create competitive moats. Firms with regulatory-ready dossiers gain first-mover advantages for premium products.
- Consolidation and strategic re-positioning: Recent transactions and strategic reviews create transient pockets of opportunity for bolt-on deals, distribution realignment, or partnership formation.
- Sustainability and nutrient management: The role of enzymes in reducing phosphorus excretion and lowering feed carbon intensity elevates their strategic value to integrators and corporate sustainability teams.
Recommended strategic plays for 2026
- For manufacturers: Prioritise product lines with defensible technical differentiation (stability to pelleting, multi‑enzyme synergy). Use our ROI models to justify targeted CAPEX on pilot facilities versus licensing deals.
- For feed formulators and integrators: Run designed pilots with next‑gen phytases across representative operations, using the report’s inclusion-rate templates to quantify feed-cost savings and margin impact before roll‑out.
- For distributors and channel partners: Rebalance commercial incentives toward bundled solutions (enzyme + technical services) that capture recurring revenue and reduce churn.
- For investors and M&A teams: Use the market-concentration and scenario outputs to identify attractive entry points — either through buying differentiated niche innovators or acquiring scale in consolidating segments.
How to convert the insight into 90‑day action
- Day 0–30: Use the supplier scorecards to shortlist vendors and initiate NDA-enabled data exchanges. Stress-test your current enzyme contracts against our price-elasticity scenarios.
- Day 30–60: Deploy a 4–6 week pilot for a next‑gen enzyme in a high‑value feed stream; use the report’s metrics to fast-track ROI validation and internal approvals.
- Day 60–90: Finalise commercial terms with preferred suppliers, update procurement templates, and brief the executive committee with the scenario P&L impacts provided in the report.
The trailer — what this summary omits and why
In keeping with the “trailer” principle, this briefing intentionally showcases insights and commercial implications while withholding line‑by‑line segment tables, regional share breakdowns, and per-application revenue figures. Those granular datasets, model files and the full competitive scorecards are included in the source report and are essential for detailed go/no‑go decisions, contract negotiations and M&A valuation work.
Concluding note — why act in 2026
Enzyme technologies have moved from commoditised additives to strategic enablers of feed efficiency and sustainability. With a structurally growing market, measurable premium opportunities for differentiated products, and a consolidation backdrop that will reshape distribution and pricing, 2026 is a pivotal planning year. Firms that couple technical validation with commercial agility — leveraging regulatory sequencing and procurement‑led risk mitigation — will capture disproportionate value over the forecast horizon.
To access the complete dataset, supplier scorecards, and the full suite of implementation tools referenced here, please consult the PW Consulting Animal Feed Enzymes Market report. The full report contains the granular segmentation and model outputs necessary to translate these strategic recommendations into executable plans.
For detailed analysis of this topic, please visit the official page: Animal Feed Enzymes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Multi-family/HOA Software Market to Hit USD 2,327M by 2032
By pmarketresearch, 2026-07-13
Multi-family & HOA Property Management Software Market: Strategic Imperatives for 2026
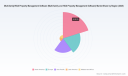
As owners, operators, and technology executives prepare capital allocation and digital roadmaps for 2026, understanding the trajectory and structural forces shaping Multi‑family and HOA Property Management Software has never been more critical. PW Consulting’s latest market research frames the sector within a clear quantitative context—the market reached roughly USD 1.4 billion in our 2025 baseline and is tracking at a compound annual growth rate near 7.6% through the forecast horizon—projecting to exceed USD 2.3 billion by the end of the 2032 forecast. That scale, combined with middling concentration among incumbents, makes this market a fertile ground for both organic product investment and targeted consolidation.
Multi-family/HOA Property Management Software (Multi-family and HOA Property Management Software) Market
Why this study matters for 2026 decision cycles
-
Procurement clarity: As portfolios scale, enterprise buyers need standardized vendor scorecards that align SaaS economics, implementation timelines, and risk controls to capital planning horizons.
Multi-family/HOA Property Management Software (Multi-family and HOA Property Management Software) Market -
Regulatory alignment: Heightened privacy and data residency requirements are no longer a compliance afterthought; they materially affect vendor selection, contract clauses, and TCO.
Multi-family/HOA Property Management Software (Multi-family and HOA Property Management Software) Market -
Operational transformation: Property operations that once relied on disparate spreadsheets and point solutions are converging on integrated platforms—decisions made in 2026 will lock in operational patterns for years.
-
Strategic M&A and partnerships: With the leading vendors commanding a meaningful share of the market, acquirers must use robust due diligence to identify complementary capabilities (payments, resident experience, predictive maintenance, analytics) that accelerate value capture.
Market dynamics shaping vendor and buyer strategies
The sector’s growth is being driven by several intersecting forces. Expectations around resident experience and digital service delivery are rising: portals, mobile leasing, automated communications, and frictionless payments are table stakes. At the same time, providers are differentiating on operational depth—integrated accounting, layered maintenance workflows, and advanced reporting remain decisive in large portfolios.
-
Cloud migration and AI: Vendors continue shifting to cloud-first delivery and embedding automation and predictive analytics into leasing, screening, and maintenance workflows. These capabilities are reshaping implementation risk profiles and long‑term cost curves.
-
Consolidation and concentration: The market shows moderate concentration—top-tier players command a substantial share, while an active roster of regional and niche vendors competes aggressively in pricing and feature specialization.
-
Privacy and localization pressures: Compliance complexity has increased operational burden for many vendors—our sector analysis notes that compliance with regional privacy laws increased operational complexity for a notable share of suppliers. Moreover, roughly half of government‑affiliated housing organizations now prefer localized data storage to satisfy jurisdictional requirements, driving demand for flexible hosting and deployment options.
-
Cybersecurity and cost implications: Rising cyber threats and stricter data rules are raising vendor operational costs and influencing procurement through enhanced security requirements, indemnification clauses, and certification demands.
Competitive landscape — who to watch (and why)
Competition remains active across tiers. A few illustrative vendor archetypes emerge from our research:
-
Large enterprise platforms that bundle deep accounting, operations, and analytics—these firms compete on breadth and scale, targeting large portfolios and institutional owners.
-
Mid-market cloud natives that emphasize modern UX, automation, and rapid deployment—these vendors often win on total cost of ownership and speed-to-value.
-
Niche and compliance specialists focusing on specific segments like affordable housing, HOAs, or regional data‑sovereignty requirements—these providers leverage deep vertical expertise.
The report profiles key companies that represent these archetypes, summarizing headquarters, public-facing offers, and strategic positioning. Examples include platforms with integrated accounting and operations suites, solutions emphasizing AI-enabled resident portals and automation, and vendors focused on community association workflow and compliance. Recent product activity underscores an active innovation cycle—new cloud releases, enhancements to predictive analytics and tenant screening, and mobile leasing improvements have been announced by several leading firms across 2025–2026. Buyers and investors should read these moves not as incremental updates alone but as indicators of strategic priorities: cloud performance, data services, and resident experience are where R&D budgets are concentrated.
What PW Consulting’s report delivers (practical, operational, actionable)
This market study is designed to be a decision-ready toolkit for 2026 planners. Highlights include:
-
Validated market sizing and a 2026–2032 forecast with scenario sensitivity analyses to support budget and M&A modelling.
-
Vendor scorecards that benchmark product breadth, deployment flexibility, implementation risk, and security postures—tailored for enterprise, mid-market, and niche use cases.
-
Procurement playbooks mapping RFP templates, SLA expectations, and negotiation levers for SaaS and hybrid deployments.
-
Implementation roadmaps and change-management guides that reduce time‑to‑value and protect resident experience during migration.
-
TCO and ROI models with stress tests for privacy/regulatory cost inflation and cyber incident scenarios.
-
Ally & ecosystem maps identifying fintech, maintenance, and IoT partners that accelerate platform value.
To preserve strategic advantage and encourage direct engagement, the report intentionally refrains from publishing certain granular split tables and proprietary benchmarks in this free preview. Those detailed segmentations, regional dynamics, and company-level financial estimates are available in the full report and accompanying data annex.
Strategic imperatives for executives in 2026
Based on our analysis, organizations must adopt a dual approach that balances near-term operational gains with long-term strategic flexibility. Key imperatives include:
-
Design for data sovereignty up front: Negotiate deployment and hosting terms that allow for regional data residency options; require clear migration and escrow provisions to mitigate regulatory risk.
-
Prioritize cybersecurity as a product requirement: Insist on third‑party attestation, incident response SLAs, and contractual liability limits that reflect real-world exposures—cyber risks materially impact TCO.
-
Adopt a modular migration strategy: Break large migrations into composable phases (payments and accounting first, followed by resident experience and predictive maintenance) to reduce disruption and demonstrate incremental ROI.
-
Benchmark vendor economics: Evaluate vendors not only on subscription fees but on implementation cost, integration effort, data extraction fees, and long-term upgrade paths.
-
Use pilots to de‑risk scale: Run controlled, KPIs‑driven pilots that measure onboarding times, delinquency trends, maintenance cycle times, and resident satisfaction before committing to enterprise rollouts.
-
Embed M&A into product strategy: For platform leaders, pursue tuck‑ins that close capability gaps (analytics, payments, compliance). For smaller firms, explore carve-outs or strategic partnerships to accelerate distribution.
How to use this research in practice
Procurement teams should use the report to build RFP requirements that are aligned with the organization’s privacy posture and operational cadence. Technology leaders can use the vendor scorecards and integration maps to plan API workstreams and internal service ownership. Finance teams will find the scenario-based TCOs and sensitivity analyses useful for capital planning and for stress-testing vendor economics under adverse regulatory or cyber events.
PW Consulting perspective and next step
The Multi‑family/HOA property management software market presents a clear growth runway and a competitive landscape that rewards software providers who can combine product depth with strong security and flexible deployment options. Decisions made in 2026—about which platforms to adopt, which integrations to prioritize, and where to place capital—will determine operating economics and resident experience for the rest of the decade.
For readers ready to operationalize these insights, PW Consulting’s full report provides the missing segmentation matrices, vendor-level benchmarks, and downloadable modeling templates required to develop procurement RFPs, internal business cases, and M&A target screens. Access the complete research dossier and data annex on our website or contact our advisory team to commission a tailored vendor selection or integration plan.
For detailed analysis of this topic, please visit the official page: Multi-family/HOA Property Management Software (Multi-family and HOA Property Management Software) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Infrared Detector Market to hit USD 1,100M by 2032 at 8.5% CAGR
By pmarketresearch, 2026-07-13
Infrared Detector Market 2026: Strategic Preview for Executive Decision-Making
As organizations prepare their 2026 playbooks, infrared detector technologies have moved from narrow, specialist use-cases into mainstream strategic considerations spanning defense, automotive, industrial automation, building safety, and consumer IoT. PW Consulting’s new Infrared Detector Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes market dynamics, regulatory inflections, supply constraints, and competitive positioning into an actionable intelligence package. This preview outlines the study’s strategic value for 2026 decisions while intentionally withholding the granular subsegment datapoints that we reserve for the full report.
Infrared Detector Market
Market trajectory and what it signals for 2026
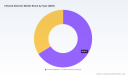
The infrared detector market has expanded meaningfully over the past half-decade, moving from roughly USD 450 million in 2020 to USD 620 million in 2025. Our forecast indicates continued momentum into the late 2020s and early 2030s, with the market tracking to approximately USD 685 million in 2026 and reaching around USD 1.10 billion by 2032—an implied compound annual growth rate of roughly 8.5% across the forecast window.
Infrared Detector Market
This overall growth reflects a confluence of drivers: accelerated adoption of thermal sensing in safety and security, integration of infrared modules into advanced driver-assistance and autonomous mobility stacks, industrial predictive maintenance programs, and cost declines in uncooled detector platforms that broaden addressable markets. Notably, the historical series shows episodic volatility—pandemic-era disruption, supply-chain squeezes, and product launch cycles—which underlines the need for scenario planning rather than single-point forecasts when setting 2026 capital and product-roadmap decisions.
Infrared Detector Market
Why this study matters for 2026 corporate decisions
- Portfolio prioritization: The study identifies where revenue growth and margin expansion are most plausible without disclosing proprietary subsegment economics in this preview. Executives can use the framework to prioritize R&D and SKU rationalization.
- M&A and partnership screening: With market concentration signaling mid-level consolidation, the report provides a ranked playbook to evaluate tuck-ins, strategic alliances, and bolt-on technologies that accelerate time-to-market.
- Supply-chain and materials strategy: We map critical raw-material exposure (including the role of germanium in LWIR optics) and provide hedging and qualification pathways to prevent 2025–2026 style procurement shocks.
- Regulatory and standards compliance: The analysis enables timely product certification strategies by translating recent standards updates into product specification checklists and testing roadmaps.
- Commercial go-to-market: The study contains buyer persona matrices and channel strategies to compress sales cycles for new detector-enabled offerings.
What you’ll find inside the full report (practical deliverables)
- Dynamic market model with scenario-based forecasts (base, upside, downside) and sensitivity levers you can re-run with your own pricing, ASP, and volume assumptions.
- Segment architecture and use-case maps—by detector type, technology, and application—with adoption timing and commercialization risk scores (note: subsegment quantitative tables are withheld here).
- Supplier scorecards and sourcing playbooks that assess manufacturing footprint, technology depth, IP position, and capacity risk for each major OEM and tier-one supplier.
- Regulatory impact matrix translating NFPA, ISO, and regional building codes into product features, certification timelines, and claims that buyers will accept.
- Raw-material exposure analysis including concentration, single-source risks, and strategic options (substitution pathways, recycled-material initiatives, and secondary sourcing strategies).
- Technology roadmaps and R&D prioritization frameworks identifying high-return technical bets and realistic time-to-revenue horizons.
- Commercial templates—pricing elasticity models, channel incentive structures, and enterprise procurement negotiation playbooks tailored to vendors and systems integrators.
- Three executable 12–24 month strategic plans for vendors, system integrators, and large end-users—focused respectively on: (1) rapid product-market fit acceleration, (2) scale and margin optimization, and (3) procurement resilience.
Competitive landscape — who matters and why
The market exhibits a moderate degree of concentration: the top three suppliers account for roughly 38.5% of industry revenues while the top five approach the low-50s percent range. That structure creates clear prospects for both incumbent defenders and fast-follow specialists.
- Hamamatsu Photonics K.K. (Japan) — Well established in scientific, industrial, and research-grade detectors; deep optical expertise and trusted in measurement-grade applications.
- Murata Manufacturing Co., Ltd. (Japan) — Strength in miniaturized modules for consumer and automotive sensors; competitive in high-volume, low-cost markets.
- Texas Instruments Incorporated (United States) — Leverages analog and sensor integration strengths to deliver uncooled solutions for motion detection and industrial automation.
- Raytheon Technologies Corporation (United States) — Focused on defense/aerospace, high-performance cooled detectors, and system-level integration in mission-critical solutions.
- Honeywell International Inc. (United States) — Broad systems approach for building automation, safety, and industrial controls with deep channel relationships.
- NXP Semiconductors N.V. (Netherlands) — Integrates IR sensing into automotive and edge-processor ecosystems for intelligent sensing and sensor fusion.
- Teledyne Technologies (United States) — Portfolio includes detector modules and thermal imaging systems; recent trade-show activity underscores focus on autonomous mobility and drone applications.
- Excelitas Technologies (United States) — Specialty in pyroelectric and thermopile detectors for presence detection and industrial sensing.
- Lynred (France) — Advanced uncooled and cooled detectors with targeted launches for drone and industrial markets.
Recent industry activity demonstrates both innovation and commercial push: Teledyne FLIR’s 2026 trade-show presence highlighted designs for automotive autonomy and compact industrial modules; Lynred introduced a compact detector variant for drones in mid‑2026; InfraTec and DIAS maintained visibility at specialist trade events. These behaviors point to intensified competition around form factor, power consumption, and integration ease over the coming 18 months.
Key dynamics, material risks, and regulatory inflections
- Raw-material concentration: Germanium remains a critical optical substrate for long-wave infrared optics, accounting for a significant share of the infrared optical material market. This creates single-material risk for LWIR supply chains and pricing sensitivity for systems that cannot tolerate performance trade-offs.
- Standards and code changes: The 2025 edition of NFPA 72 and ISO 7240-1:2025 explicitly acknowledge thermal-imaging fire detectors and associated terminology, altering certification paths and opening demand in life-safety product lines. Additionally, regional building code updates effective in 2026 expand baseline detection requirements in residential construction, accelerating procurement cycles for certain detector classes.
- Technology substitution and cost curves: Uncooled detector technologies are driving down system costs and enabling new embedded applications; cooled platforms retain performance advantages for defense and high-end industrial imaging. The interplay between cost reduction and capability demand differentiates vendor go-to-market strategies.
- Supply-chain fragility: Episodic capacity constraints and lead-time volatility for detector wafers and optics necessitate contractual and operational mitigations—dual sourcing, strategic inventory, and design-for-supply flexibility.
Strategic implications and recommended 2026 actions
- Prioritize modular, software-defined products: Investing in modular lenses, interchangeable detectors, and software stacks for image enhancement shortens upgrade cycles and increases product longevity.
- Hedge material exposure: Secure germanium and other optical materials through multi-year supply agreements, qualified second-sources, and material substitution R&D where performance tolerances allow.
- Leverage standards changes: Fast-track certification roadmaps to capitalize on new NFPA and ISO recognition of thermal detectors in safety systems—first-to-certify can capture premium channel placements in building and fire-safety procurement.
- Targeted M&A and alliances: For firms seeking scale, prioritize acquisitions that bring unique detector IP, production capacity, or differentiated optics rather than broad product portfolios; for system integrators, partner with specialists that lower integration risk.
- Commercial cadence optimization: Rework channel incentives to reflect recurring revenue models (service, analytics) rather than one-off hardware sales; this is a practical lever to improve lifetime value in 2026 negotiations.
- Invest in software and sensor fusion: As sensors become commoditized, value will shift to edge analytics and fusion with lidar, radar, and visible cameras—investing here protects margin against hardware price erosion.
How to use this preview—and what’s behind the paywall
This executive preview has highlighted the macro trendlines, competitive players, standards shifts, and the near-term strategic choices you must make entering 2026. The full PW Consulting Infrared Detector Market report contains the operational granularity your teams will use to execute these choices: downloadable market models, vendor scorecards, supplier negotiation playbooks, detailed scenario outputs, and the quantitative subsegment tables that underpin our conclusions (with sensitivity toggles you can populate with internal assumptions).
If your 2026 strategy depends on precise channel pricing, supplier capacity plans, or product-line investment cases, we recommend commissioning the full report or a tailored workshop. PW Consulting can also run a customized stress-test of your product roadmap against our forecast scenarios to identify the optimal investment and hedging mix for the next 12–24 months.
For access to the full datasets, supplier scorecards, and the scenario model workbook, please follow the link to the published report. The dynamics described here will define winners and losers in 2026—decisions made now on sourcing, certification, and system architecture will compound materially through the decade.
For detailed analysis of this topic, please visit the official page: Infrared Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CMP Polishing Pads Market - USD 1,425M in 2025, 6.87% CAGR to 2032
By pmarketresearch, 2026-07-13
CMP Polishing Pads Market — Strategic Briefing for 2026 Decision-Makers
As semiconductor supply chains steady into recovery and next‑generation node cycles intensify, CMP (chemical mechanical planarization) polishing pads have re‑emerged as a strategic consumable category. This briefing, prepared by PW Consulting, distills the market intelligence and practical implications you need to shape sourcing, product development, and M&A strategies in 2026. The full CMP Polishing Pads Market report (base year 2025; forecast 2026–2032) provides the granular segmentation, supplier scorecards, and scenario model outputs that are intentionally summarized here to protect critical splits and drive action.
CMP Polishing Pads Market
Why this intelligence matters in 2026
-
Macro momentum: After a steady recovery from 2020–2025, the global CMP polishing pads market reached a clear inflection point in 2025. Our market model shows a compound annual growth rate (CAGR) of 6.87% across the 2026–2032 forecast horizon, with total market value expanding materially from the 2020 baseline to robust end‑period sizing in 2032 (figures in USD Million). This growth is being driven by both capacity additions at advanced fabs and broader IC packaging demand.
CMP Polishing Pads Market -
Concentration and competitive dynamics: The sector exhibits high supplier concentration — the top three vendors account for approximately 75.5% of market shipments, and the top five approach 83.2%. That structure creates predictable qualification pathways but also supplier power that procurement teams must actively manage.
CMP Polishing Pads Market -
Regulatory and materials inflection points: Environmental mandates and raw‑material volatility are no longer background noise. Notable corporate and regulatory initiatives — including major foundry moves to eliminate chlorinated pore fillers and global pressure to restrict PFAS — are accelerating product redesign and qualification investments across the supplier base.
What the PW Consulting report delivers — operationally usable outputs
-
Rigorous market sizing and demand scenarios: A base‑year analysis (2025) and scenario forecasts through 2032 that combine fab roadmap overlays, expected throughput gains, and consumable consumption models. These outputs quantify addressable demand under three adoption pathways (conservative, base, and accelerated) and include sensitivity cases tied to yield improvements and cycle time reductions.
-
Supply‑side diagnostics and a 5‑point procurement playbook: Factory capacity maps, qualification timeline templates, lead‑time tiers, and a supplier risk heatmap that identifies single‑sourcing exposures. These are translated into immediate actions — e.g., tactical stocking thresholds, dual‑vendor qualification triggers, and cost‑to‑serve levers for high‑value fabs.
-
Raw material and cost driver deep dives: Materials dossiers covering thermoset polyurethanes, polyester formulations, polycaprolactone derivatives, and composite alternatives. We quantify the impacts of feedstock price swings and specialized processing costs on pad unit economics and build a procurement hedging matrix for 12–36 month horizons.
-
Regulatory & sustainability playbook: A compliance roadmap showing how bans/restrictions (e.g., PFAS policies) and lead customer commitments to chlorine‑free pore fillers translate into qualification timelines and rework costs. The report includes a stepwise chemical substitution decision tree and a lifecycle assessment (LCA) template for pad suppliers and fabricators.
-
Competitive benchmark and product taxonomy: Detailed vendor scorecards, product platform mapping, and a technology readiness index for emerging pad architectures. These enable R&D prioritization, co‑development targeting, and M&A screening based on capability gaps rather than headline market share alone.
Key market dynamics to watch — and act on
-
Qualification lead time remains the choke point. Advanced‑node fabs require multi‑stage pad validation — from lab compatibility checks to extended in‑fab drum‑rolls. Buyers should plan for overlapping qualification tracks with parallel tracks for chlorine‑free and fluorine‑free pad chemistries to avoid single‑path dependencies.
-
Raw materials are a two‑edged sword. For example, polycaprolactone derivatives used in some thermoset polyurethane formulations have shown pronounced price volatility — swings on the order of 20–25% tied to upstream crude and synthesis constraints. Meanwhile, specialized monomer production carries cost multipliers versus conventional petroleum‑based polymers. Procurement should layer fixed‑price contracts with indexed purchases and consider strategic inventory for critical grades.
-
Regulation is accelerating innovation and qualification costs. Large foundries have publicly committed to replacing chlorinated pore fillers within near‑term roadmaps, and PFAS restrictions are pushing composite and fluorine‑free alternatives into accelerated commercialization. These shifts create opportunity for suppliers with flexible materials platforms but raise switching costs for fabs tied to legacy chemistries.
-
Supplier concentration creates both stability and strategic risk. The high CR3/CR5 percentages mean buyers benefit from robust supplier expertise and consistent product platforms, but that same concentration increases negotiation urgency and the need for certified alternates, particularly for specialty pad grades used in advanced packaging and cutting‑edge nodes.
Competitor landscape — strategic positioning and implication
-
Hubei Dinglong Co., Ltd. — a vertically integrated, full‑process producer with proprietary casting capabilities. Recent investments (including a joint analysis and testing platform launched in 2025) signal an aggressive move into custom pad co‑development for domestic and regional fabs. Strategic implication: partners needing bespoke formulations or localized supply should engage early on co‑development terms.
-
Fujibo Holdings Inc. — a high‑capacity manufacturer with multiple plants across Japan and Taiwan. The company’s scale and manufacturing footprint support rapid volume qualifications and supply continuity. Strategic implication: attractive for high‑volume, lower‑complexity pads where supply security trumps extreme customization.
-
IV Technologies (iVT) — long‑standing specialization in polymeric pads and membranes with a focused R&D cadence. Their niche expertise makes them a go‑to for opto‑electronic and certain specialized polishing applications. Strategic implication: consider iVT for co‑innovation where polymer science is a gating factor.
-
Spartan Felt and Saint‑Gobain — reliable global suppliers with broad application portfolios, trusted for traditional planarization needs and aftermarket support. Strategic implication: strong candidates for multi‑site deployments requiring consistent quality and global logistics capabilities.
-
Qnity Electronics (formerly DuPont), 3M, and Entegris — technology leaders offering next‑generation platforms and microreplicated pad solutions. Recent product launches (notably Qnity’s Emblem™ platform in late 2025) and advanced microreplication approaches position these vendors as premium suppliers for AI/advanced computing node applications. Strategic implication: premium performance often comes with rigorous qualification and ASP premiums — prioritize pilot deployments where yield or throughput gains justify the cost.
Recent developments that will shape 2026 choices
-
Supplier innovation and testing platforms: Hubei Dinglong’s 2025 launch of a joint analysis and testing platform underscores a broader trend: suppliers investing in shared validation infrastructure to accelerate customer qualification cycles. Buyers who participate in such platforms can shorten time‑to‑qualified status and influence pad formulations.
-
Customer‑driven chemistry changes: TSMC’s validated rollouts of chlorine‑free pore fillers and their planned full deployment by end‑2026 are a practical example of how buyer commitments de‑risk supplier R&D investments and force ecosystem shifts. Semiconductor companies should factor the timing and cost of internal pad requalification into capital and yield projections.
-
Next‑generation pad platforms: Technology launches targeted at AI and advanced nodes (e.g., Emblem™) are surfacing earlier in supplier roadmaps. These platforms aim to deliver step‑change performance, but their economic case is node‑ and process‑specific. Operational pilots and joint ROI models are essential before scaled adoption.
How executives should act in 2026 — recommended playbook
-
Procurement: Build dual‑track qualification pipelines (legacy chemistry + low‑PFAS/chlorine‑free alternatives). Lock in partial forward coverage for critical grades and request supplier KPIs tied to lead‑time SLAs and qualification support.
-
R&D and process engineering: Prioritize integration testing of composite and fluorine‑free pads in dedicated pilot tools. Allocate budget for rapid in‑fab assessments (shortened drum‑rolls) in collaboration with suppliers offering co‑validation platforms.
-
Supply chain and risk: Map single‑point vulnerabilities across critical pad grades and raw materials, focusing on polycaprolactone supply and other specialty feedstocks. Establish alternative sourcing clauses and consider strategic stockpiles for narrow bands of critical pads.
-
Corporate development: Use the market concentration and platform differentiation analysis to screen potential acquisitions or minority investments — prioritize targets that add unique chemistry platforms, rapid co‑development capabilities, or regional manufacturing footprints.
Limitations and next steps
This briefing highlights the strategic contours and actionable implications from our CMP Polishing Pads Market study. To preserve the commercial value of our segmentation and supplier scorecards, we have deliberately kept granular regional and application splits out of this summary. The full report contains detailed regional, type, and application breakdowns, product‑level BOM sensitivity outputs, vendor CLM scores, and downloadable scenario models in USD (Million). For procurement templates, supplier negotiation playbooks, and the data tables underpinning the forecasts, please consult the full report on our website or contact PW Consulting directly.
Final note
For companies making 2026 investment and sourcing decisions, CMP polishing pads are no longer a routine consumable but a strategic lever that intersects yield, sustainability compliance, and fab throughput. Our modeling shows a market trajectory that rewards early engagement with suppliers who can validate chlorine‑ and fluorine‑free solutions, while also hedging raw material risk. PW Consulting’s full report equips you with the detailed maps, supplier assessments, and executable playbooks needed to convert this market trajectory into competitive advantage.
For detailed analysis of this topic, please visit the official page: CMP Polishing Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Kinesio Tape Market — Strategic Preview for 2026: Why This Report Matters
Executive snapshot
As PW Consulting’s Senior Strategy Advisor, I present a concise, high-fidelity preview of our Kinesio Tape Market research — an actionable intelligence package built to inform executive decision-making throughout 2026. The market is on a clear expansion path: using 2025 as the base year, our topline model places global revenue in the mid-hundreds of USD Million and projects continued acceleration through the 2026–2032 forecast window at an 8.2% compound annual growth rate. Historical performance from 2020–2025 shows resilient demand despite episodic supply and reimbursement noise, positioning the industry at a strategic inflection point as product innovation, sustainability, and clinical adoption converge.
Kinesio Tape Market
Why 2026 is a strategic inflection year
-
Consolidation and professionalization: Recent M&A and brand-level investments have shifted the competitive environment from fragmented commodity selling toward integrated, clinically informed product lines and omnichannel distribution. This is the year many leaders will convert brand equity into scalable clinical and institutional contracts.
Kinesio Tape Market -
Evidence and certification tipping points: Requirements for skin-contact biocompatibility (ISO 10993) and the ongoing enforcement of device classifications (e.g., Class I medical device subject to FDA 510(k) pathways in the U.S.) are raising the bar for product development and procurement. Firms that embed these standards early narrow commercial risk and accelerate access to institutional buyers.
Kinesio Tape Market -
Material and application innovation: Advances such as graphene-infused adhesives, eco-friendly substrates, and water-resistant constructions are creating product differentiation opportunities beyond price. Early adopters who can translate materials science into clinically validated outcomes will capture the premium segment.
Market trajectory — what the headline numbers mean for strategy
Readers should view the topline model as a directional framework for capital allocation. From 2020 through the 2025 base year the market demonstrated steady expansion, and our forecast extends that momentum through 2032, driven by product innovation, broader clinical adoption, and rising sports and rehabilitation demand globally. An 8.2% CAGR over the forecast window implies that mid-market and premium segments will expand faster than lower-margin commoditized supply — a critical insight for product, manufacturing and sales strategies.
For decision-makers, the implications are straightforward: growth exists, but margins will favor companies that combine differentiated product features (material science, ISO-certified biocompatibility) with institutional access (clinical partnerships, athletic program endorsements) and operational control (supply chain resilience, cost-to-serve optimization).
Competitive landscape: who matters and why
The market sits in a moderately concentrated competitive structure. A small set of established and legacy brands still command a meaningful share of value, but recent activity indicates an opening for both incumbents and well-funded challengers to extend reach and capture higher-margin use cases.
-
Kinesio Holding Corporation — the originator of the category — remains strategically important as both a brand and technology steward. Recent product launches emphasize eco-friendly formulations, aligning with institutional procurement trends and major event selection committees.
-
KT Tape (now under Bridges Consumer Healthcare LLC) — acquisition activity has accelerated omnichannel and R&D investment, and the brand’s evolution toward technologically enhanced adhesives (including graphene-infused prototypes) is a credible route to premiumization.
-
RockTape — notable for clinician-oriented product development and new self-application lines, RockTape’s partnerships with sports-rehab providers signal a play for institutional adoption.
-
TheraBand, Mueller, SpiderTech and other established suppliers — these players bridge clinical and consumer channels, leveraging broader product portfolios and distribution networks to defend market positions.
-
Regional and specialized manufacturers (Japan, Korea, Europe) — these firms continue to supply high-performance and certified tapes, increasingly competing on product attributes and sustainability credentials.
Recent market events — acquisitions, certifications for major teams, and launches of graphene- and biodegradable-based products — materially change competitive posture. The full report contains a strategic benchmarking matrix that evaluates product roadmaps, channel reach, certification status and innovation pipelines to identify takeover targets and partnership candidates.
Regulatory and reimbursement dynamics — constraints and opportunities
-
Regulatory frame: In the U.S., kinesio tapes are classified as Class I medical devices; firms must manage FDA 510(k) clearance pathways where applicable and demonstrate compliance with skin-contact biocompatibility standards such as ISO 10993. These certifications are increasingly a commercial gate rather than a technical nicety.
-
Reimbursement realities: Kinesio taping itself is often not a reimbursable procedure under dominant public payors, and supplies are typically coded under applicable tape HCPCS codes. This means commercial strategies should not assume growth via reimbursement-driven volume — instead, the primary levers are institutional contracts (clinics, sports federations), employer wellness programs, and consumer retail.
-
Clinical evidence and procurement: As clinical buyers demand documented outcomes, vendors who invest in randomized studies, registries, or institutional pilots will unlock procurement pathways that are less price-sensitive and more quality-driven.
Supply chain and product architecture considerations
Raw material architecture remains central: modern kinesio tapes typically rely on a latex-free acrylic adhesive paired with a porous textile backing engineered for stretch and breathability. Manufacturers should prioritize supply continuity for specialty adhesive chemistries and sustainable substrate options. Near-term risks include adhesive raw material volatility, certification lead times for new substrates, and potential tariff or logistics shocks in trans-regional sourcing.
What our full report delivers — operationally actionable content
The full PW Consulting Kinesio Tape Market report moves beyond high-level narrative. It equips leaders with executable playbooks and decision support tools, including:
-
A detailed go-to-market playbook segmented by buyer persona (clinician, athletic program manager, retail purchaser) with recommended channel mixes and KPIs to measure traction.
-
Product development scorecards linking material choices (e.g., textile construction, adhesive formulations) to clinical performance metrics and procurement preferences.
-
Regulatory roadmap templates for FDA registration and ISO 10993 certification timelines, resource estimates and risk checkpoints.
-
Commercial scenarios and pricing models calibrated to the 2026 revenue base and 8.2% CAGR forecast — supporting unit economics, margin expansion levers, and cash-flow timelines for new product introductions.
-
Competitive benchmarking and M&A target shortlists derived from strategic fit, technology gaps and aftermarket synergies — including integration playbooks to preserve customer relationships and accelerate cross-sell.
-
Operational tools: supplier scorecards, packaging optimization checklists for sustainability compliance, and SKU rationalization frameworks that prioritize high-margin SKUs and reduce complexity.
Importantly, the report intentionally withholds granular regional and application-level revenue splits in this preview to preserve the full, data-rich models available in the paid analysis. Executives seeking the explicit segmentation matrices, price-by-region benchmarks, and addressable-market micro-models should consult the complete dataset.
Recommended strategic moves for 2026
-
Prioritize certification and clinical validation: Start ISO 10993 testing and plan for FDA engagements now; the timeline to certification can be a competitive differentiator.
-
Invest in material differentiation: Allocate R&D resources toward high-value adhesives and sustainable substrates that align with institutional procurement and major event specifications.
-
Build institutional channels: Secure pilot partnerships with leading sports-rehabilitation clinics and national training programs — these partnerships accelerate evidence generation and brand authority.
-
Optimize go-to-market mix: Balance direct institutional sales with omnichannel consumer presence; use digital buyer journeys to convert professional endorsements into retail demand.
-
Hunt for smart acquisitions and alliances: Target adjacent suppliers that fill capability gaps (e.g., adhesive chemistry, diagnostic adjuncts) and accelerate access to new procurement channels.
Next steps — how to use this intelligence
If your 2026 planning cycle includes product launches, capital allocation, or M&A, treat this preview as the strategic frame. The full PW Consulting report contains the underlying models, sensitivity analyses and detailed competitor dossiers needed to convert these strategic recommendations into executable plans. For teams focused on immediate deployment, our consulting practice offers tailored workshops that map the report’s insights to your commercial and R&D roadmaps.
For access to the complete dataset, segmentation matrices, and the proprietary scenario-planning model, please refer to the report landing page or contact PW Consulting directly. The rich mix of regulatory, clinical, and commercial intelligence in the full analysis is designed to remove ambiguity and enable confident 2026 decisions.
For detailed analysis of this topic, please visit the official page: Kinesio Tape Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting FPC Outlook: USD 306.5 Million by 2032 at 6.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
FPC Market 2026: Strategic Preview for Decision-Makers
As enterprise leaders prepare budgets, technology roadmaps, and supply-chain strategies for 2026, understanding the flexible printed circuit (FPC) ecosystem has moved from specialist interest to boardroom imperative. PW Consulting’s FPC Market — Preview Edition frames the dynamics that will shape capital allocation, sourcing decisions, and product strategies over the next planning cycle. This introduction highlights the report’s strategic value, synthesizes the macro trajectory, and outlines the practical tools embedded in the full study — while intentionally reserving granular segment and regional splits for subscribers who access the complete report.
FPC Market
Executive snapshot: why FPCs matter in 2026
FPCs are foundational components for a wave of higher-value electronics — from EVs and ADAS harnesses to foldable consumer devices, medical wearables, and compact industrial sensors. The market shows sustained expansion: from a baseline measured across the historical period up to 2025 through our forecast window (2026–2032). Using 2025 as the base year, the market has grown materially since 2020 and is projected to compound at a steady mid-single-digit CAGR of 6.5% through 2032, reflecting both replacement and expansion demand driven by miniaturization, high-frequency signal requirements, and increasing reliability standards in safety-critical applications.
FPC Market
Quantitatively, the FPC industry moved from an industry-scale base in 2020 to a notably larger industry by 2025, with forecasts pointing to continued growth through 2032. For executives, the implication is clear: investment timelines that assume static supply availability or flat pricing will be exposed to execution risk. Instead, 2026 planning must incorporate capacity, material, and tariff contingencies to protect margins and time-to-market.
FPC Market
What this means for 2026 corporate decisions
- Procurement and Sourcing: The industry’s growth trajectory increases leverage for strategic sourcing teams — but not uniformly. Raw material constraints and tariff structures create pockets of price and supply volatility. Procurement leaders should prioritize multi-sourcing strategies, contractual footprints that include material-index pass-throughs, and localized buffer capacity in near-shore facilities.
- Product & Platform Roadmaps: Designers must reconcile ambitions for ultra-thin, high-density, or high-frequency designs with manufacturing realities. New material classes (e.g., LCP) and advanced adhesives expand capability but carry supply-chain and qualification timelines that must be embedded early in 2026 product development cycles.
- Capital Allocation: Building internal FPC capacity or hybrid captive arrangements can be defensible for high-volume, high-reliability applications. Financial models should test scenarios versus contract manufacturing to capture the trade-offs between CapEx, time-to-volume, and technology obsolescence.
- M&A and Partnerships: With mid-market consolidation and targeted technology plays, acquirers can unlock value through bolt-on capabilities such as rigid-flex expertise, automated defect detection, or IC-substrate integration.
Market trajectory and structural drivers
The market’s compound annual growth reflects three structural demand pillars: electrification and advanced safety in automotive; miniaturization and foldable/connected devices in consumer electronics; and the rising penetration of FPCs in medical, aerospace, and industrial automation where weight, reliability, and form-factor are critical. On the supply side, technology moves — such as multilayer laminates, liquid crystal polymer (LCP) adoption for high-frequency performance, and advanced adhesives — are enabling new architectures but are increasing dependence on specialty raw materials.
These material dynamics matter: polyimide substrates—central to many FPC architectures—can trade at multiples relative to commodity FR4 laminates, magnifying input cost sensitivity. At the same time, trade policy and export controls are reshaping cost structures: certain flex and rigid-flex product flows face layered tariff regimes that can aggregate to substantial effective duty rates, while export restrictions on critical laminates and films raise the specter of supply interruptions. The combined effect is a market that is growing, but with heterogenous margin pressure across product tiers and geographies.
Competitive landscape: capabilities, differentiation, and strategic moves
The sector exhibits moderate concentration, with a measurable share held by the largest players. The competitive field combines global contract manufacturers, vertically integrated incumbents, and specialized regional producers. Key strategic positions include:
- Vertical integration and materials control: Firms with upstream access to copper or substrate materials are positioned to manage margin volatility and shorten qualification cycles for automotive and communications customers.
- Advanced materials and design capability: Suppliers commercializing LCP-based FPCBs or leveraging specialty dielectrics and adhesives can command pricing power in high-frequency and high-reliability segments.
- Assembly and system integration: Providers offering end-to-end assembly, rigid-flex integration, and automated defect detection lower customer integration costs and accelerate time-to-market for complex modules.
- Regional execution and cost advantage: Lower labor-cost geographies retain competitiveness for standard architectures, applying pressure on commodity FPC pricing while customers increasingly source premium designs from specialists.
Illustrative vendor moves underscore these themes. Several leading companies have recently commercialized or launched products and capacity that signal strategic priorities: ultra-miniature connectors for wearable IoT; LCP-based FPCBs for next-generation communications; rigid-flex series tailored to automotive sensor suites; and plant expansions integrating AI-driven defect detection. These are not isolated developments — they form a pattern of technology and capacity alignment to higher-value segments, particularly in automotive, communications, and medical applications.
Risk matrix: supply, policy, and execution
Decision-makers must plan across three correlated risk vectors:
- Material concentration: Specialized substrates and adhesives create single points of failure. Mitigation includes dual-sourcing, qualified second suppliers, and strategic inventory of critical films and laminates.
- Trade and regulatory shocks: Recent tariff structures and export controls materially alter landed costs. Scenario modeling for duty shocks and localized production is now table-stakes for procurement and product pricing strategies.
- Labor and cost dynamics: Competitive pressure from lower-cost manufacturing regions compresses margins in commodity segments, accelerating a shift toward either higher-value differentiation or cost-driven outsourcing.
What the full PW Consulting FPC Market report delivers
Our comprehensive study — structured for operating executives, procurement heads, and corporate strategists — translates market trends into executable intelligence. The report combines rigorous market sizing (base year 2025, historical period 2020–2025, forecast 2026–2032 at a projected 6.5% CAGR, currency USD, revenue unit Million) with scenario-based analysis and practical decision tools. Core deliverables include:
- Proprietary market model and forecast corridor with sensitivity analyses for material-price and tariff scenarios.
- Strategic supplier scoring and a go/no-go matrix for in-house capacity versus contract manufacturing.
- Technology readiness and adoption curves for advanced materials (e.g., LCP, specialty dielectrics) and process innovations.
- Commercial playbooks for OEMs and EMS providers: specification templates, qualification timelines, and cost-to-serve calculators.
- M&A and partnership scouting dossiers, including capability gap maps and integration risk checklists.
- Regulatory and compliance tracker emphasizing tariffs, export controls, and product-specific requirements pertinent to 2026 trade environments.
- Supply-chain stress test templates to simulate raw-material shortages or geopolitical trade disruptions and to construct hedging/mitigation plans.
To preserve competitive value for readers who deploy this intelligence operationally, the report intentionally centralizes granular breakouts — such as detailed regional and application splits, and supplier-specific contract models — behind the subscription wall. That depth is essential for supplier negotiations, capital budgeting, and product qualification planning in 2026 and beyond.
How to use the preview findings in your 2026 planning cycle
- Start with scenarios: Build at least three procurement scenarios — baseline, tariff shock, and material-shortage — and map internal product exposures by BOM criticality.
- Prioritize qualification pipelines: Fast-track qualification of alternative substrate suppliers and LCP options for product lines where RF performance or thermal stability is mission-critical.
- Design for manufacturability: Embed FPC manufacturability reviews earlier in the design cycle to reduce re-spins and supplier change costs.
- Evaluate strategic partnerships: Consider co-investments with incumbent FPC specialists for captive capacity or priority supply agreements when your product mix demands assured, high-reliability supply.
Final note — an invitation to the full intelligence
This preview sets the strategic context for 2026: a market expanding on a steady mid-single-digit CAGR, but increasingly defined by material constraints, tariff complexity, and a bifurcation between commodity and high-value FPC segments. PW Consulting’s full FPC Market report operationalizes these insights into models, supplier assessments, and playbooks that directly inform procurement, R&D, and M&A decisions. For teams preparing 2026 budgets and roadmaps, the full study provides the granular segmentation, supplier-level analysis, and scenario outputs necessary to move from insight to action.
Access the complete report to retrieve the detailed segmentation tables, supplier dossiers, and executable templates designed for immediate integration into your 2026 planning processes.
For detailed analysis of this topic, please visit the official page: FPC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Management IC Market 2026: Strategic Guidance from PW Consulting
As the electrification and digitization waves continue to reshape product architectures across automotive, consumer, industrial and telecom end markets, Power Management ICs (PMICs) have migrated from component-class status to strategic system enabler. PW Consulting’s latest PMIC Market study (base year 2025; historical 2020–2025; forecast 2026–2032) documents this transition with a rigorous, reproducible market model. The market expanded from approximately USD 163.15 Million in 2020 to USD 215.0 Million in 2025 and, under our central case, will grow at a 6.5% CAGR to reach roughly USD 344.8 Million by 2032. These headline figures set the stage — the decisions firms make in 2026 about portfolio focus, supply-chain architecture and go-to-market will determine who captures the asymmetric upside.
Power Management IC (PMIC) Market
Why this study matters for 2026 corporate decisions
- Objective sizing for investment prioritization: the study provides a reconciled historical series and a scenario-driven forecast that isolates structural growth (end-market electrification, data-center densification) from transitory demand swings.
- Design and product strategy levers: with new efficiency mandates and changing application architectures, firms must choose between pursuing integration (multi-function PMICs) versus specialization (high-efficiency, single-function regulators).
- Supply-chain and geopolitical risk planning: regulatory shifts and export controls are re-shaping sourcing and manufacturing economics — the report translates those dynamics into quantified exposure maps and mitigation playbooks.
- Competitive and M&A alignment: the study combines concentration metrics and firm-level dossiers to help C-suite teams prioritize inorganic targets and partnership architectures.
What the PW Consulting report delivers — practical and operational
We built this study as a decision-support toolkit, not an academic paper. The full deliverable is organized around seven actionable modules:
Power Management IC (PMIC) Market
- Market model and interactive forecast (2026–2032) — transparent assumptions, sensitivity levers, and downloadable worksheets to test alternative scenarios.
- Segmentation and demand drivers — multi-dimensional splits by region, product family (e.g., voltage regulators, battery-management ICs, switching controllers, motor-control ICs) and application, with growth drivers and margin profiles for each segment. Note: detailed segment-level figures are available in the full report and interactive dataset.
- Value-chain heatmaps — from wafer sourcing to final assembly and testing, highlighting cost pools, logistics chokepoints and near-term capacity constraints.
- Competitive dossiers and scorecards — comprehensive profiles for public and regional champions, including R&D focus, automotive qualification pipelines, product breadth, channel strength and partnership momentum.
- Regulatory and policy scenario analysis — modeled impacts of efficiency mandates, export-control regimes and tariff actions on demand and unit economics.
- M&A and strategic options playbook — target capability matrices, valuation heuristics and integration risk checklists built from precedent transactions and buy-side interviews.
- Commercial templates — negotiable contract clauses, qualification timelines, and a playbook for securing Tier‑1 design wins in automotive and hyperscale data-center segments.
Key market dynamics shaping 2026 strategy
- Efficiency mandates and product redesign. New efficiency thresholds and standby-power caps introduced in late 2025 force PMIC vendors and OEM customers to re-evaluate architectural tradeoffs. Our analysis shows that burst-mode optimization, transient response tuning and system-level co-design (PMIC + battery management + power stages) become differentiators for design wins in both consumer and automotive programs.
- Geopolitical frictions and export controls. Tightened export controls since 2024–2025 and ongoing inquiries into semiconductor imports have elevated the cost of cross-border supply chains. Firms with single-source dependencies in constrained geographies will face longer qualification cycles and higher working-capital demands. Our scenario models quantify the relative impact of alternative export-control and tariff outcomes on sourcing costs and time-to-market.
- Consolidation and competitive concentration. The PMIC market shows meaningful concentration among leading players; our concentration metrics indicate that the top three and top five vendors command a commanding portion of market revenues, creating both barriers and consolidation opportunities for challengers. Competitive dynamics are now shaped more by platform breadth and system-level partnerships than by discrete-device cost alone.
- Electrification and system complexity. Automotive electrification, battery energy-storage integration and power-hungry edge compute nodes are expanding addressable content per system. This increases per-unit ASPs for integrated PMIC solutions but also raises qualification and reliability demands that lengthen sales cycles.
Competitive landscape — what to watch in 2026
Market leaders combine broad product portfolios with deep channel access and automotive/industrial qualification competency. Several public and private players occupy distinct strategic positions:
Power Management IC (PMIC) Market
- Large analog incumbents sustain advantages through scale in power analog, a broad BOM footprint and established design-win channels for industrial and consumer customers.
Recent vendor moves illustrate these trends: leading firms have released higher-density isolated power modules and updated multi-channel automotive PMIC datasheets in early 2026, signaling ongoing investment in both product breadth and documentation to accelerate customer adoption. Investors and strategic teams should monitor product-announcement cadence, qualification pipelines, and ecosystem partnerships more closely than quarterly revenue swings.
Strategic implications and recommended actions for 2026
- Prioritize product development for regulatory-forward designs. Firms that proactively design for higher efficiency thresholds and lower standby power will shorten OEM qualification timelines and reduce retrofit costs.
- Rebalance supply chains toward resilient dual-sourcing and nearshoring where economics permit. Use the report’s exposure maps to quantify near-term cost versus risk tradeoffs and reconfigure contracts to include capacity and lead-time clauses.
- Target acquisitions for capability gaps, not capacity alone. M&A should focus on acquiring differentiated IP (e.g., battery-management algorithms, isolated-power modules, advanced packaging) and accelerating time-to-design-win in strategic end markets.
- Embed regulatory scenario planning into product and commercial roadmaps. The timing and scope of export-control and tariff measures will materially affect customer engagements and S&OP; incorporate alternative-case revenue and margin plans into 2026 budgets.
- Shift go-to-market models to system-level selling. Success increasingly requires co-design with OEMs and T1 suppliers; invest in application engineering teams and qualification-lab capabilities.
- Use competitive concentration to your advantage. If you are a market leader, convert breadth into lock-in with platform bundles and long-term supply agreements. If you are a challenger, pursue niche specialization and faster time-to-qualification.
How to use the full PW Consulting study
Consider this article a strategic trailer: it presents the high-level trajectories, the decision levers and the competitive posture you need to evaluate in 2026, while preserving the detailed segmentation and company-level datasets for the full report. The complete study contains the interactive forecast model, granular regional and application splits, unit economics by product family, vendor scorecards and executable templates that corporate strategy, M&A and product teams can operationalize immediately.
For leadership teams preparing 2026 planning cycles, the PW Consulting PMIC Market report is a decision accelerator: it reduces uncertainty around demand sizing, prioritizes capability investments, and prescribes actionable mitigations for supply-chain and regulatory shocks. To request the full dataset, license the interactive forecast or schedule a strategic briefing with our senior analysts, visit the PW Consulting research portal or contact our industry practice leads. The choices made in 2026 will determine who captures the highest-margin, system-defining design wins in the decade ahead.
For detailed analysis of this topic, please visit the official page: Power Management IC (PMIC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com