

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting FPC Outlook: USD 306.5 Million by 2032 at 6.5% CAGR (2026–2032)

FPC Market 2026: Strategic Preview for Decision-Makers
As enterprise leaders prepare budgets, technology roadmaps, and supply-chain strategies for 2026, understanding the flexible printed circuit (FPC) ecosystem has moved from specialist interest to boardroom imperative. PW Consulting’s FPC Market — Preview Edition frames the dynamics that will shape capital allocation, sourcing decisions, and product strategies over the next planning cycle. This introduction highlights the report’s strategic value, synthesizes the macro trajectory, and outlines the practical tools embedded in the full study — while intentionally reserving granular segment and regional splits for subscribers who access the complete report.
FPC Market
Executive snapshot: why FPCs matter in 2026
FPCs are foundational components for a wave of higher-value electronics — from EVs and ADAS harnesses to foldable consumer devices, medical wearables, and compact industrial sensors. The market shows sustained expansion: from a baseline measured across the historical period up to 2025 through our forecast window (2026–2032). Using 2025 as the base year, the market has grown materially since 2020 and is projected to compound at a steady mid-single-digit CAGR of 6.5% through 2032, reflecting both replacement and expansion demand driven by miniaturization, high-frequency signal requirements, and increasing reliability standards in safety-critical applications.
FPC Market
Quantitatively, the FPC industry moved from an industry-scale base in 2020 to a notably larger industry by 2025, with forecasts pointing to continued growth through 2032. For executives, the implication is clear: investment timelines that assume static supply availability or flat pricing will be exposed to execution risk. Instead, 2026 planning must incorporate capacity, material, and tariff contingencies to protect margins and time-to-market.
FPC Market
What this means for 2026 corporate decisions
- Procurement and Sourcing: The industry’s growth trajectory increases leverage for strategic sourcing teams — but not uniformly. Raw material constraints and tariff structures create pockets of price and supply volatility. Procurement leaders should prioritize multi-sourcing strategies, contractual footprints that include material-index pass-throughs, and localized buffer capacity in near-shore facilities.
- Product & Platform Roadmaps: Designers must reconcile ambitions for ultra-thin, high-density, or high-frequency designs with manufacturing realities. New material classes (e.g., LCP) and advanced adhesives expand capability but carry supply-chain and qualification timelines that must be embedded early in 2026 product development cycles.
- Capital Allocation: Building internal FPC capacity or hybrid captive arrangements can be defensible for high-volume, high-reliability applications. Financial models should test scenarios versus contract manufacturing to capture the trade-offs between CapEx, time-to-volume, and technology obsolescence.
- M&A and Partnerships: With mid-market consolidation and targeted technology plays, acquirers can unlock value through bolt-on capabilities such as rigid-flex expertise, automated defect detection, or IC-substrate integration.
Market trajectory and structural drivers
The market’s compound annual growth reflects three structural demand pillars: electrification and advanced safety in automotive; miniaturization and foldable/connected devices in consumer electronics; and the rising penetration of FPCs in medical, aerospace, and industrial automation where weight, reliability, and form-factor are critical. On the supply side, technology moves — such as multilayer laminates, liquid crystal polymer (LCP) adoption for high-frequency performance, and advanced adhesives — are enabling new architectures but are increasing dependence on specialty raw materials.
These material dynamics matter: polyimide substrates—central to many FPC architectures—can trade at multiples relative to commodity FR4 laminates, magnifying input cost sensitivity. At the same time, trade policy and export controls are reshaping cost structures: certain flex and rigid-flex product flows face layered tariff regimes that can aggregate to substantial effective duty rates, while export restrictions on critical laminates and films raise the specter of supply interruptions. The combined effect is a market that is growing, but with heterogenous margin pressure across product tiers and geographies.
Competitive landscape: capabilities, differentiation, and strategic moves
The sector exhibits moderate concentration, with a measurable share held by the largest players. The competitive field combines global contract manufacturers, vertically integrated incumbents, and specialized regional producers. Key strategic positions include:
- Vertical integration and materials control: Firms with upstream access to copper or substrate materials are positioned to manage margin volatility and shorten qualification cycles for automotive and communications customers.
- Advanced materials and design capability: Suppliers commercializing LCP-based FPCBs or leveraging specialty dielectrics and adhesives can command pricing power in high-frequency and high-reliability segments.
- Assembly and system integration: Providers offering end-to-end assembly, rigid-flex integration, and automated defect detection lower customer integration costs and accelerate time-to-market for complex modules.
- Regional execution and cost advantage: Lower labor-cost geographies retain competitiveness for standard architectures, applying pressure on commodity FPC pricing while customers increasingly source premium designs from specialists.
Illustrative vendor moves underscore these themes. Several leading companies have recently commercialized or launched products and capacity that signal strategic priorities: ultra-miniature connectors for wearable IoT; LCP-based FPCBs for next-generation communications; rigid-flex series tailored to automotive sensor suites; and plant expansions integrating AI-driven defect detection. These are not isolated developments — they form a pattern of technology and capacity alignment to higher-value segments, particularly in automotive, communications, and medical applications.
Risk matrix: supply, policy, and execution
Decision-makers must plan across three correlated risk vectors:
- Material concentration: Specialized substrates and adhesives create single points of failure. Mitigation includes dual-sourcing, qualified second suppliers, and strategic inventory of critical films and laminates.
- Trade and regulatory shocks: Recent tariff structures and export controls materially alter landed costs. Scenario modeling for duty shocks and localized production is now table-stakes for procurement and product pricing strategies.
- Labor and cost dynamics: Competitive pressure from lower-cost manufacturing regions compresses margins in commodity segments, accelerating a shift toward either higher-value differentiation or cost-driven outsourcing.
What the full PW Consulting FPC Market report delivers
Our comprehensive study — structured for operating executives, procurement heads, and corporate strategists — translates market trends into executable intelligence. The report combines rigorous market sizing (base year 2025, historical period 2020–2025, forecast 2026–2032 at a projected 6.5% CAGR, currency USD, revenue unit Million) with scenario-based analysis and practical decision tools. Core deliverables include:
- Proprietary market model and forecast corridor with sensitivity analyses for material-price and tariff scenarios.
- Strategic supplier scoring and a go/no-go matrix for in-house capacity versus contract manufacturing.
- Technology readiness and adoption curves for advanced materials (e.g., LCP, specialty dielectrics) and process innovations.
- Commercial playbooks for OEMs and EMS providers: specification templates, qualification timelines, and cost-to-serve calculators.
- M&A and partnership scouting dossiers, including capability gap maps and integration risk checklists.
- Regulatory and compliance tracker emphasizing tariffs, export controls, and product-specific requirements pertinent to 2026 trade environments.
- Supply-chain stress test templates to simulate raw-material shortages or geopolitical trade disruptions and to construct hedging/mitigation plans.
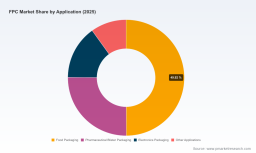
To preserve competitive value for readers who deploy this intelligence operationally, the report intentionally centralizes granular breakouts — such as detailed regional and application splits, and supplier-specific contract models — behind the subscription wall. That depth is essential for supplier negotiations, capital budgeting, and product qualification planning in 2026 and beyond.
How to use the preview findings in your 2026 planning cycle
- Start with scenarios: Build at least three procurement scenarios — baseline, tariff shock, and material-shortage — and map internal product exposures by BOM criticality.
- Prioritize qualification pipelines: Fast-track qualification of alternative substrate suppliers and LCP options for product lines where RF performance or thermal stability is mission-critical.
- Design for manufacturability: Embed FPC manufacturability reviews earlier in the design cycle to reduce re-spins and supplier change costs.
- Evaluate strategic partnerships: Consider co-investments with incumbent FPC specialists for captive capacity or priority supply agreements when your product mix demands assured, high-reliability supply.
Final note — an invitation to the full intelligence
This preview sets the strategic context for 2026: a market expanding on a steady mid-single-digit CAGR, but increasingly defined by material constraints, tariff complexity, and a bifurcation between commodity and high-value FPC segments. PW Consulting’s full FPC Market report operationalizes these insights into models, supplier assessments, and playbooks that directly inform procurement, R&D, and M&A decisions. For teams preparing 2026 budgets and roadmaps, the full study provides the granular segmentation, supplier-level analysis, and scenario outputs necessary to move from insight to action.
Access the complete report to retrieve the detailed segmentation tables, supplier dossiers, and executable templates designed for immediate integration into your 2026 planning processes.
For detailed analysis of this topic, please visit the official page: FPC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com