

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CMP Polishing Pads Market - USD 1,425M in 2025, 6.87% CAGR to 2032

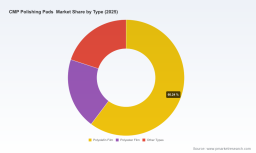
CMP Polishing Pads Market — Strategic Briefing for 2026 Decision-Makers
As semiconductor supply chains steady into recovery and next‑generation node cycles intensify, CMP (chemical mechanical planarization) polishing pads have re‑emerged as a strategic consumable category. This briefing, prepared by PW Consulting, distills the market intelligence and practical implications you need to shape sourcing, product development, and M&A strategies in 2026. The full CMP Polishing Pads Market report (base year 2025; forecast 2026–2032) provides the granular segmentation, supplier scorecards, and scenario model outputs that are intentionally summarized here to protect critical splits and drive action.
CMP Polishing Pads Market
Why this intelligence matters in 2026
-
Macro momentum: After a steady recovery from 2020–2025, the global CMP polishing pads market reached a clear inflection point in 2025. Our market model shows a compound annual growth rate (CAGR) of 6.87% across the 2026–2032 forecast horizon, with total market value expanding materially from the 2020 baseline to robust end‑period sizing in 2032 (figures in USD Million). This growth is being driven by both capacity additions at advanced fabs and broader IC packaging demand.
CMP Polishing Pads Market -
Concentration and competitive dynamics: The sector exhibits high supplier concentration — the top three vendors account for approximately 75.5% of market shipments, and the top five approach 83.2%. That structure creates predictable qualification pathways but also supplier power that procurement teams must actively manage.
CMP Polishing Pads Market -
Regulatory and materials inflection points: Environmental mandates and raw‑material volatility are no longer background noise. Notable corporate and regulatory initiatives — including major foundry moves to eliminate chlorinated pore fillers and global pressure to restrict PFAS — are accelerating product redesign and qualification investments across the supplier base.
What the PW Consulting report delivers — operationally usable outputs
-
Rigorous market sizing and demand scenarios: A base‑year analysis (2025) and scenario forecasts through 2032 that combine fab roadmap overlays, expected throughput gains, and consumable consumption models. These outputs quantify addressable demand under three adoption pathways (conservative, base, and accelerated) and include sensitivity cases tied to yield improvements and cycle time reductions.
-
Supply‑side diagnostics and a 5‑point procurement playbook: Factory capacity maps, qualification timeline templates, lead‑time tiers, and a supplier risk heatmap that identifies single‑sourcing exposures. These are translated into immediate actions — e.g., tactical stocking thresholds, dual‑vendor qualification triggers, and cost‑to‑serve levers for high‑value fabs.
-
Raw material and cost driver deep dives: Materials dossiers covering thermoset polyurethanes, polyester formulations, polycaprolactone derivatives, and composite alternatives. We quantify the impacts of feedstock price swings and specialized processing costs on pad unit economics and build a procurement hedging matrix for 12–36 month horizons.
-
Regulatory & sustainability playbook: A compliance roadmap showing how bans/restrictions (e.g., PFAS policies) and lead customer commitments to chlorine‑free pore fillers translate into qualification timelines and rework costs. The report includes a stepwise chemical substitution decision tree and a lifecycle assessment (LCA) template for pad suppliers and fabricators.
-
Competitive benchmark and product taxonomy: Detailed vendor scorecards, product platform mapping, and a technology readiness index for emerging pad architectures. These enable R&D prioritization, co‑development targeting, and M&A screening based on capability gaps rather than headline market share alone.
Key market dynamics to watch — and act on
-
Qualification lead time remains the choke point. Advanced‑node fabs require multi‑stage pad validation — from lab compatibility checks to extended in‑fab drum‑rolls. Buyers should plan for overlapping qualification tracks with parallel tracks for chlorine‑free and fluorine‑free pad chemistries to avoid single‑path dependencies.
-
Raw materials are a two‑edged sword. For example, polycaprolactone derivatives used in some thermoset polyurethane formulations have shown pronounced price volatility — swings on the order of 20–25% tied to upstream crude and synthesis constraints. Meanwhile, specialized monomer production carries cost multipliers versus conventional petroleum‑based polymers. Procurement should layer fixed‑price contracts with indexed purchases and consider strategic inventory for critical grades.
-
Regulation is accelerating innovation and qualification costs. Large foundries have publicly committed to replacing chlorinated pore fillers within near‑term roadmaps, and PFAS restrictions are pushing composite and fluorine‑free alternatives into accelerated commercialization. These shifts create opportunity for suppliers with flexible materials platforms but raise switching costs for fabs tied to legacy chemistries.
-
Supplier concentration creates both stability and strategic risk. The high CR3/CR5 percentages mean buyers benefit from robust supplier expertise and consistent product platforms, but that same concentration increases negotiation urgency and the need for certified alternates, particularly for specialty pad grades used in advanced packaging and cutting‑edge nodes.
Competitor landscape — strategic positioning and implication
-
Hubei Dinglong Co., Ltd. — a vertically integrated, full‑process producer with proprietary casting capabilities. Recent investments (including a joint analysis and testing platform launched in 2025) signal an aggressive move into custom pad co‑development for domestic and regional fabs. Strategic implication: partners needing bespoke formulations or localized supply should engage early on co‑development terms.
-
Fujibo Holdings Inc. — a high‑capacity manufacturer with multiple plants across Japan and Taiwan. The company’s scale and manufacturing footprint support rapid volume qualifications and supply continuity. Strategic implication: attractive for high‑volume, lower‑complexity pads where supply security trumps extreme customization.
-
IV Technologies (iVT) — long‑standing specialization in polymeric pads and membranes with a focused R&D cadence. Their niche expertise makes them a go‑to for opto‑electronic and certain specialized polishing applications. Strategic implication: consider iVT for co‑innovation where polymer science is a gating factor.
-
Spartan Felt and Saint‑Gobain — reliable global suppliers with broad application portfolios, trusted for traditional planarization needs and aftermarket support. Strategic implication: strong candidates for multi‑site deployments requiring consistent quality and global logistics capabilities.
-
Qnity Electronics (formerly DuPont), 3M, and Entegris — technology leaders offering next‑generation platforms and microreplicated pad solutions. Recent product launches (notably Qnity’s Emblem™ platform in late 2025) and advanced microreplication approaches position these vendors as premium suppliers for AI/advanced computing node applications. Strategic implication: premium performance often comes with rigorous qualification and ASP premiums — prioritize pilot deployments where yield or throughput gains justify the cost.
Recent developments that will shape 2026 choices
-
Supplier innovation and testing platforms: Hubei Dinglong’s 2025 launch of a joint analysis and testing platform underscores a broader trend: suppliers investing in shared validation infrastructure to accelerate customer qualification cycles. Buyers who participate in such platforms can shorten time‑to‑qualified status and influence pad formulations.
-
Customer‑driven chemistry changes: TSMC’s validated rollouts of chlorine‑free pore fillers and their planned full deployment by end‑2026 are a practical example of how buyer commitments de‑risk supplier R&D investments and force ecosystem shifts. Semiconductor companies should factor the timing and cost of internal pad requalification into capital and yield projections.
-
Next‑generation pad platforms: Technology launches targeted at AI and advanced nodes (e.g., Emblem™) are surfacing earlier in supplier roadmaps. These platforms aim to deliver step‑change performance, but their economic case is node‑ and process‑specific. Operational pilots and joint ROI models are essential before scaled adoption.
How executives should act in 2026 — recommended playbook
-
Procurement: Build dual‑track qualification pipelines (legacy chemistry + low‑PFAS/chlorine‑free alternatives). Lock in partial forward coverage for critical grades and request supplier KPIs tied to lead‑time SLAs and qualification support.
-
R&D and process engineering: Prioritize integration testing of composite and fluorine‑free pads in dedicated pilot tools. Allocate budget for rapid in‑fab assessments (shortened drum‑rolls) in collaboration with suppliers offering co‑validation platforms.
-
Supply chain and risk: Map single‑point vulnerabilities across critical pad grades and raw materials, focusing on polycaprolactone supply and other specialty feedstocks. Establish alternative sourcing clauses and consider strategic stockpiles for narrow bands of critical pads.
-
Corporate development: Use the market concentration and platform differentiation analysis to screen potential acquisitions or minority investments — prioritize targets that add unique chemistry platforms, rapid co‑development capabilities, or regional manufacturing footprints.
Limitations and next steps
This briefing highlights the strategic contours and actionable implications from our CMP Polishing Pads Market study. To preserve the commercial value of our segmentation and supplier scorecards, we have deliberately kept granular regional and application splits out of this summary. The full report contains detailed regional, type, and application breakdowns, product‑level BOM sensitivity outputs, vendor CLM scores, and downloadable scenario models in USD (Million). For procurement templates, supplier negotiation playbooks, and the data tables underpinning the forecasts, please consult the full report on our website or contact PW Consulting directly.
Final note
For companies making 2026 investment and sourcing decisions, CMP polishing pads are no longer a routine consumable but a strategic lever that intersects yield, sustainability compliance, and fab throughput. Our modeling shows a market trajectory that rewards early engagement with suppliers who can validate chlorine‑ and fluorine‑free solutions, while also hedging raw material risk. PW Consulting’s full report equips you with the detailed maps, supplier assessments, and executable playbooks needed to convert this market trajectory into competitive advantage.
For detailed analysis of this topic, please visit the official page: CMP Polishing Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com