

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hyperimmune Globulins Market — USD 1,798M in 2025; 6.7% CAGR to 2032

Hyperimmune Globulins Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented preview of our forthcoming Hyperimmune Globulins market study. This briefing is designed for C-suite leaders, corporate strategy teams, BD executives and investors preparing for pivotal choices in 2026. It synthesizes macro trajectories, competitive moves and regulatory shifts that will determine who captures the next wave of opportunity — while intentionally omitting the granular segment tables to prompt access to our full intelligence platform for transactional-level detail.
Hyperimmune Globulins Market
Market snapshot: growth trajectory and what it means for strategy
The hyperimmune globulins market has moved from a niche therapeutics category to a strategically important, mid-sized specialty biologics market. Using 2025 as the study’s base year, the market is estimated to be approximately USD 1.8 billion. Our forecast model, which integrates historical trends (2020–2025), production capacity shifts and anticipated clinical/regulatory catalysts, projects the market to grow at a compound annual growth rate (CAGR) of 6.7% over the 2026–2032 period — reaching roughly USD 2.8 billion by 2032.
Hyperimmune Globulins Market
For executives, that headline growth conceals two actionable realities: (1) capacity and yield improvements on the supply side can rapidly reframe competitive advantage and margin profiles, and (2) targeted clinical advances and label expansions can create disproportionate commercial upside for specific product categories. In short, steady headline expansion coexists with asymmetric, high-impact events that will determine winners and losers.
Hyperimmune Globulins Market
Why 2026 is an inflection year
-
Regulatory momentum is accelerating. Recent approvals and investigational filings in 2024–2026 have created a pipeline of near-term catalysts that will affect market access and reimbursement strategy in 2026.
-
Manufacturing innovation is shifting the cost curve. Yield-enhancement approvals and production milestones are improving supply economics, altering sourcing dynamics and shortening the window for new entrants to establish differentiated cost positions.
-
Commercial consolidation and partnerships are intensifying. Distribution arrangements and co-commercialization agreements are redefining reach in key channels — a trend that will accelerate in 2026 as companies convert trial readouts into go-to-market plans.
Practical value of the report for 2026 decisions
Our research is structured to be actionable. It supports three classes of executive decisions:
-
Portfolio prioritization — which indications, formulations and delivery routes to scale, divest or deprioritize based on projected returns and execution risk through 2032.
-
Capacity and sourcing choices — when to invest in yield-enhancing processes or secure long-term plasma supply versus pursuing contract manufacturing partnerships.
-
M&A and partnership playbooks — defensive and offensive deal scenarios grounded in valuation sensitivity to regulatory and production outcomes.
What the full report contains (operational, not just descriptive)
-
Model-driven market forecast by year (base year: 2025) with scenario off-ramps tied to regulatory and manufacturing events; dynamic dashboards to test price, adoption and supply variables.
-
Commercial economics models: net revenue and margin curves under alternate reimbursement and pricing scenarios, including sensitivity to yield improvements and plasma sourcing costs.
-
Go-to-market playbooks for different company archetypes — incumbents, regional specialists, pure-play manufacturers and late-stage clinical entrants — with prioritized tactical initiatives for 12–36 month execution windows.
-
Supply-chain resilience framework: risk heat maps for plasma availability, cold-chain logistics and contract manufacturing capacity, plus mitigation roadmaps and sourcing scorecards.
-
Regulatory and reimbursement tracker mapping known approvals and plausible near-term filings into market-access timelines and payer negotiation levers.
-
Commercial benchmarking of pricing strategy, channel mix and patient hub requirements (redacted in this preview to preserve competitive sensitivity).
Competitive landscape — who matters and why
The market remains shaped by a mix of vertically integrated plasma-to-product firms, specialized contract manufacturers and regional distributors. Key corporate actors to monitor include established plasma-derived manufacturers, manufacturers of indication-specific immune globulins, and strategic distributors that control access to hospital and public-health channels.
-
ADMA Biologics — an end-to-end plasma-derived player that has recently secured regulatory approval for a production yield enhancement process. That approval meaningfully alters production economics and positions ADMA to defend incumbency or pursue volume-driven price strategies. ADMA’s pediatric label expansion for one of its products further underscores a willingness to pursue label extensions to grow addressable markets.
-
Biotest Pharmaceuticals — an established manufacturer with commercial partnerships that expand distribution reach for newer formulations of immunoglobulin therapy; its collaboration models provide a template for how mid-sized players can punch above their weight.
-
CSL Behring — a large incumbent with an extensive portfolio and strong manufacturing footprint; their scale and product breadth make them a natural anchor for many hospital procurement decisions and a likely acquirer of complementary assets.
-
Kedrion / Kamada — examples of the distributor-to-manufacturer chain, where strategic alliances allow regional players to secure supply and expand product offerings without duplicative capital investment.
-
Takeda — a public-health collaborator and manufacturer of specialty hyperimmune products that demonstrates how government partnerships and not-for-profit supply agreements can shape production cadence and brand positioning.
-
Emerging biologics developers (e.g., Immuron) — clinical-stage entrants who have recently cleared investigational filings and who represent the primary source of category innovation over the forecast horizon.
Collectively, these company dynamics show a market driven as much by manufacturing and distribution playbooks as by pure clinical differentiation.
Recent, high-impact developments (implications)
-
Yield-enhancement approvals are a game-changer: regulators accepting novel production processes compress capital intensity and enable incumbents to generate more output from existing plasma pools. Strategically, this increases returns to scale and raises the bar for new greenfield capacity investments.
-
Clinical progress on pathogen-targeted hyperimmune candidates opens new indication tailwinds. Programs moving into mid-stage trials (and those with expanded pediatric or immunocompromised labels) will become focal points for partnership and licensing activity in 2026.
-
Not-for-profit production agreements with public-health agencies can stabilize supply for critical products but also create commercial blind spots for private players; companies must model both the reputational and margin impacts of such commitments.
-
Commercial partnerships for novel delivery systems (e.g., subcutaneous formulations) are reshaping channel economics and payer negotiations — and will be a critical determinant of uptake in outpatient and home-infusion settings.
Strategic imperatives for leaders in 2026
-
Prioritize yield and capacity actions: quantify how incremental yield improvements affect your unit economics and market share potential. In many scenarios, modest yield gains deliver outsized free cash flow improvements.
-
Lock down supply and flexibility: diversify plasma procurement, secure capacity through CMOs and include performance-linked clauses to protect against demand shocks.
-
Pursue selective label and formulation expansions: clinical investments that enable pediatric or immunocompromised indications, or more convenient delivery routes, materially expand addressable patients and bargaining power with payers.
-
Adopt an outcomes-based GTM for hospital and public-health accounts: combine evidence generation with patient-support services to mitigate payer resistance and accelerate formulary placement.
-
Design M&A with regulatory and capacity contingencies baked in: valuation models must stress-test integration timelines and the risk of production ramp delays.
How to use this research now
-
Strategy teams: use our scenario models to stress-test portfolio roadmaps and 2026 capital plans under alternate supply and regulatory outcomes.
-
Commercial leaders: extract the go-to-market playbooks and payer-approach templates to accelerate roll-out for any label expansions in your pipeline.
-
BD and Corporate Development: apply our comparative company profiles and deal-scenario valuation matrices to prioritize targets and structure contingent consideration linked to manufacturing and regulatory milestones.
Conclusion — the value proposition of the full report
PW Consulting’s complete Hyperimmune Globulins market study combines granular, model-backed forecasts with executable playbooks — the kind of intelligence that turns a growth-rate headline into concrete investment and commercialization choices. The market’s projected expansion to the high single-digit hundreds of millions by 2032 (from a 2025 base near USD 1.8 billion) is meaningful, but the real value lies in understanding how manufacturing yields, label expansions, and partnership architectures will redistribute returns within the market.
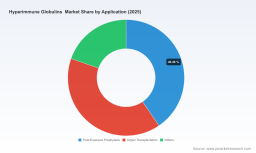
This preview intentionally leaves out transaction-level segment tables and regional/application splits to preserve analytical exclusivity. Accessing the full report provides the confidential segmentation, interactive models, and deal-ready exhibits necessary for high-stakes 2026 decision-making. PW Consulting stands ready to convene a tailored executive briefing and workshop to translate the findings into a prioritized 18-month action plan for your organization.
For detailed analysis of this topic, please visit the official page: Hyperimmune Globulins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com