

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Intra Oral Scanners Market to Grow at 9.2% CAGR Through 2032

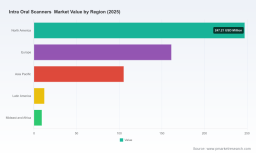
Intraoral Scanners 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a strategic preview of our comprehensive Intra Oral Scanners market research — a briefing built for corporate leaders, investors, and clinical operations executives preparing critical decisions in 2026. This article highlights why the intraoral scanner (IOS) market is a high-conviction investment area, summarizes the macro trajectory, and outlines the executable insights you will find in the full report. In keeping with our “trailer” approach, we demonstrate analytical depth while intentionally withholding core sub-segment tables and granular share-breakdowns to encourage consultation of the source report for transaction-grade intelligence.
Intra Oral Scanners Market
Market at a Glance — Why 2026 is a Pivot Year
The IOS market has moved from an early-adopter niche to a mainstream digital dentistry infrastructure. After accelerating through 2020–2025, the global market grew from roughly USD 350 million in 2020 to about USD 535 million in 2025. Under our baseline model, the market enters the forecast window (2026–2032) with a compound annual growth rate of 9.2%, approaching roughly double the 2025 size by 2032. This trajectory is driven by converging forces: clinical validation, software-enabled diagnostic expansion, falling per-scan costs, and structural reimbursement updates that embed scanning into standard workflows.
Intra Oral Scanners Market
Why this report matters for 2026 decisions
- Capital allocation: whether you are a device OEM deciding R&D and platform investments, or a multi-site dental group evaluating fleet economics, our analysis quantifies the investment horizon for scanner replacement cycles and complementary consumables, enabling build-vs.-buy decision rules.
- Go-to-market and channel strategy: our markets maps and buyer-journey segmentation reveal where service partners, labs, and dental chains will prioritize bundled hardware–software offerings versus open-platform strategies.
- Regulatory and reimbursement risk-adjustment: the report integrates recent regulatory milestones and coding changes to show how near-term approvals and CDT updates change payback timelines for clinics and lab partners.
What the full report delivers — practical, transaction-ready outputs
- Proven methodology: an auditable framework combining primary interviews, device benchmarking, clinical validation studies, and bottom-up revenue modeling (base year 2025; historical 2020–2025; forecast 2026–2032).
- Deployment economics: clinic-level TCO models with sensitivity analysis for utilization rates, sterilization cycles, consumables and maintenance that convert scanner metrics into per-procedure costs and ROI tables.
- Commercial playbooks: differentiated GTM options for OEMs (direct, distributor, OEM+lab), pricing levers (hardware subsidies, SaaS imaging fees, data licensing), and a mapping of channel margins for prioritized markets.
- Technology roadmaps: maturity assessment for key enablers — AI diagnostic overlays, hyperspectral imaging, photogrammetry for full-arch accuracy, and cloud-native vs. on-premises workflows.
- Regulatory and reimbursement tracker: impact analysis of recent rulings and code updates on adoption velocity, plus scenario planning for tightened regulatory controls or expedited clinical clearances.
- Competitive risk matrix: differentiated strategic options for incumbents and challengers, including vertical integration scenarios with labs, orthodontic workflows, and implant ecosystems.
Competitive Dynamics — what to watch in 2026
The IOS competitive landscape is concentrated around several global leaders and a broadening field of regional and value-oriented challengers. Our concentration analysis shows a market where the top three players collectively command a dominant share of industry revenue, and the top five extend that dominance further — a structure that favors scale advantages in software ecosystems, clinical validation, and regulatory investment.
Intra Oral Scanners Market
Key players we analyze in depth include long-established dental device manufacturers and fast-moving software-integrated challengers. Representative company profiles and recent milestones covered in the report:
- Dentsply Sirona — continued focus on high-accuracy restorative and chairside solutions; recent regulatory clearance expanded clinical claims that change the competitive baseline for diagnostic features.
- 3Shape — aggressive software play with TRIOS 6 and diagnostic modules; firmware-level innovation (e.g., hyperspectral packages) moves the vendor from scanner supplier to diagnostic platform provider.
- Align Technology — strong orthodontic workflows and visual ergonomics; device roadmap emphasizes integration with clear aligner ecosystems and visualization tools for clinicians and patients.
- Straumann — ecosystem play linking scanning with implant and prosthetic solutions, with an emphasis on sterilizable tip economics and clinical reliability.
- Leading Chinese OEMs and new entrants — competitive price-performance instruments and targeted full-arch photogrammetry solutions that pressure mid-range pricing and expand addressable markets.
Recent industry developments illustrate the pace of competitive evolution: a major FDA 510(k) clearance in 2025 expanded clinical diagnostic claims for a flagship scanner, a 2025 product launch at IDS repositioned a leading software vendor with AI-driven diagnostic apps, and 2026 updates include firmware-enabled hyperspectral imaging and independent product recognitions that alter buyer perceptions. The full report provides an event calendar and impact scoring to translate these announcements into market share scenarios.
Regulatory, clinical and reimbursement inflection points
- Regulatory: ISO 13485 remains a gating requirement in major markets; recent device clearances that allow specific diagnostic claims materially increase device value and buyer willingness to pay.
- Reimbursement: CDT code changes effective in 2026 formally recognize digital workflows (including duplicate denture fabrication via scanning and 3D printing), accelerating scanner adoption in restorative and prosthetic clinics where reimbursement alignment reduces payback periods.
- Clinical workflow costs: autoclave-compatible tips and consumables introduce recurring costs — typical sterilization cycles per tip are a practical operating constraint, and we show how tip lifecycle economics affect per-procedure pricing models.
Technology and operational drivers — what changes unit economics
Three technology trends will shape unit economics through 2026 and beyond: (1) the maturation of AI-powered diagnostic overlays that expand use cases beyond impressions; (2) improvements in full-arch photogrammetry and hyperspectral imaging that reduce retake rates and lab rework; and (3) the shift to cloud-native scanning platforms that enable subscription revenue and centralized analytics. Operationally, the net savings from reduced impression materials and shipping must be balanced against capital expenditure and integration costs. Our clinic-level models allow users to test multiple depreciation schedules and utilization assumptions to derive practical acquisition thresholds.
Strategic playbooks for 2026 stakeholders
- OEMs: prioritize platform extensibility and validated diagnostic claims. Invest selectively in hyperspectral and AI integrations that create defensible software moats; use financing and subscription models to accelerate penetration in small-group practices.
- Dental chains and DSOs: standardize on a primary platform that maximizes cross-site workflow consistency; leverage volume procurement for bundled software services and prioritize systems with open-architecture compatibility to avoid vendor lock-in risks.
- Dental labs and service bureaus: partner early with photogrammetry-capable vendors to offer validated full-arch services; create margin-rich “scan-to-model” capabilities and data-driven QA packages for high-value implant and prosthetic cases.
- Private equity and investors: focus diligence on software monetization, installed-base service revenue, and regulatory claim breadth. Use our scenario outputs to stress-test exit multiples under multiple adoption curves.
How to use the report in 60–90 days
- Week 1–2: run the clinic-level TCO model with your utilization and financing inputs to establish a buy/sell threshold for equipment procurement cycles.
- Week 3–6: perform a vendor short-list using our competitive scorecards and validated feature-differentiation maps; field-test two devices against retention and sterilization workflows.
- Week 7–12: negotiate commercial pilots with preferred vendors, leveraging our subscription and channel margin benchmarks to structure trial economics and performance clauses.
Conclusion — the strategic take
Intraoral scanners are transitioning from a device purchase into a platform decision with long-lived implications for clinical workflows, data ownership, and recurring revenue streams. The market’s double-digit growth trajectory through the next seven years creates multiple entry points for value creation, but success depends on integrating device capabilities with software, regulatory strategy, and channel economics. Our full report provides the granular, transaction-grade intelligence you need to convert these market dynamics into defensible corporate actions in 2026.
Next step
For the complete data tables, sub-segment forecasts, and executable models referenced here — including the drilldowns that support acquisition valuation, product roadmaps, and go-to-market playbooks — please consult the full PW Consulting Intra Oral Scanners market report. The report contains the confidential sub-segment outputs and scenario analyses required for procurement, M&A, and capital allocation decisions.
For detailed analysis of this topic, please visit the official page: Intra Oral Scanners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com