

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LED Drivers Market to Reach USD 72.61 Million by 2032 at 10.1% CAGR

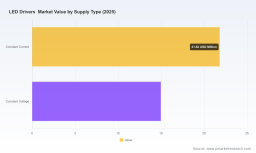
LED Drivers Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As LED-based lighting and solid-state applications move from niche to pervasive, LED drivers have transitioned from a commodity adjunct to a strategic component that shapes product economics, system reliability, and energy outcomes. Our synthesis of historical performance (2020–2025) and forward-looking scenarios (2026–2032) shows a market on a sustained expansion path, underpinned by product electrification, regulatory tightness on energy performance, and rapid IC innovation. The market is growing at a robust compound annual growth rate (CAGR) of 10.1% through the forecast window, with the overall market more than doubling from the mid-2020s to the end of the decade under our central case.
LED Drivers Market
For executive teams planning 2026 investments — whether in procurement, R&D, manufacturing footprint or M&A — the findings in our full LED Drivers Market study translate into actionable strategic priorities and direct ROI implications. This preview highlights the high-level drivers, competitive positioning signals, and the practical decision levers that organizations should prioritize this year. Detailed subsegment metrics, supplier-level scorecards and downloadable financial models are intentionally reserved for the full report to preserve actionable differentiation; the summary below is designed to demonstrate analytical depth and decision relevance.
LED Drivers Market
Why this research matters for 2026 decisions
-
Procurement optimization: Component lead times and raw-material concentration have become primary determinants of product launch timelines and margin realization. 2026 procurement cycles must account for both price volatility and supply-security clauses to protect gross margins.
LED Drivers Market -
Product roadmap prioritization: Choices around GaN adoption, DALI/D4i interoperability, dimming sophistication, and IP-rated form factors directly affect product premium and compliance windows as energy-efficiency rules tighten.
-
M&A and partnership timing: With a moderately consolidated supplier landscape and a handful of scale players controlling a meaningful portion of capacity, bolt-on acquisitions or licensing deals can be decisive for market entrants and tier-2 OEMs seeking fast capability expansion.
-
Manufacturing and localization: Tariff scenarios, component sourcing risk, and regional policy incentives will make 2026 the year to finalize or accelerate reshoring and assembly footprint strategies.
What the full report delivers (practical, operational outputs)
-
Proprietary market-sizing and forecast models (2020–2032) with downloadable spreadsheets and scenario toggles for alternative macro and raw-material trajectories.
-
Supplier scorecards and a five-step procurement playbook that maps supplier capabilities to product specifications (dimming, flicker, IP rating, thermal design) and procurement levers (MOQ, consignment, hedging).
-
Technology adoption pathways comparing incumbent silicon drivers with GaN-on-Si options, including ROI windows, component-level BOM sensitivity, and thresholds where GaN delivers net TCO gains.
-
Regulatory and standards matrix tying global policy developments to product certification roadmaps (including energy-efficiency requirements and smart-lighting interoperability standards).
-
Supply-risk index that quantifies exposure to raw-material concentration, geopolitical policy moves, and single-source suppliers; includes recommended mitigation tiers.
-
Commercial playbooks for brand licensing, OEM/ODM partnerships, and white-label strategies, with model clauses and example term-sheets calibrated to current market conditions.
-
Primary interview insights from manufacturers, lighting OEMs and IC suppliers, plus transaction comps and a short-list of acquisition targets based on strategic fit and integration risk.
Market dynamics to incorporate into your 2026 planning
The LED drivers market operates at the intersection of semiconductor trends, raw-material concentration, and energy policy. Several dynamics are central to near-term outcomes:
-
Raw-material concentration: Refined supplies for critical inputs used in driver ICs remain highly geographically concentrated. That concentration creates acute price and availability sensitivity when export controls or production shocks occur.
-
Regulatory tightening: Regional energy-efficiency directives are accelerating demand for higher-efficiency drivers and certified smart functionality. Compliance timelines are compressing product roadmaps and creating a premium for certified offerings.
-
IC innovation and cost curves: Rapid declines in the cost of GaN-on-Si driver ICs are moving what was once a niche performance upgrade into mass-adoption economics; the tipping point varies by application complexity and scale.
-
Trade and tariff risks: Proposed tariff adjustments on semiconductor inputs and components create incremental fabrication cost risk; manufacturers must model tariff pass-through scenarios and adjust sourcing strategy accordingly.
-
Supply-chain shocks and short-term dislocations: Policy actions affecting rare earths and analog semiconductor inputs have already produced intermittent supply disruptions and price spikes; resilient design-for-supply and multi-sourcing are now operational imperatives.
Competitive landscape — signals, not exhaustive rankings
The competitive map combines established power-supply specialists, IC innovators, and lighting-system incumbents. The market exhibits moderate concentration (three-firm and five-firm concentration ratios indicate a material presence of scale manufacturers) which influences pricing power and channel dynamics.
-
Mianwei Electronics (New Taipei City, Taiwan): A global leader known for reliable, standard power supplies and a wide LED driver portfolio including dimmable and ingress-protected models. Their breadth makes them a steady supply anchor for general lighting OEMs.
-
Tridonic GmbH & Co. KG (Austria): Focused on high-efficiency, smart drivers with strong DALI and professional lighting credentials. Their sustainability orientation and controls expertise position them well in high-end and commercial segments.
-
Inventronics Inc. (Hangzhou, China): Specializes in robust drivers for sports and large-format lighting with certified wireless/DALI+ offerings. Recent leadership changes and product expansions underscore a strategic push into premium lifecycle services.
-
Eaglerise (China): High-performance general lighting drivers; notable for recent licensing moves that extend brand reach via partnerships with established luminaire brands.
-
ERGLighting (USA): US-based designer focusing on UL-listed, low-flicker products — attractive to customers requiring domestic-supply credentials and tight compliance assurances.
-
SOSEN Electronics, Lifud Technology, Macroblock, Delta Electronics, Philips/Signify and others: These players populate a spectrum from IC level innovation to branded system suppliers. Each brings differentiated strengths — from highest-efficiency constant-current platforms to intelligent ICs and global go-to-market reach.
Recent industry moves are instructive: brand-licensing partnerships, executive transitions at major suppliers, and targeted product launches in non-isolated drivers and sports-lighting applications signal accelerating product specialization and go-to-market complexity. These developments create both opportunity and integration risk for OEMs and distributors planning 2026 product introductions.
Strategic playbook — recommended priorities for 2026
-
Hedge critical-input exposure: Implement multi-tiered contracts for gallium-dependent components and evaluate strategic stockpiles sized to 3–6 months of critical input needs under high-stress scenarios.
-
Accelerate GaN migration where economics support it: Identify two pilot product lines where GaN-on-Si yields unit-cost or performance advantages and create cross-functional sprints to shorten time-to-production.
-
Certify early, sell longer: Invest in compliance and smart-driver certification ahead of expected regulation enforcement windows to capture premium shelf space and avoid last-minute redesign costs.
-
Design for multi-sourcing: Standardize driver interfaces and modularize power subsystems so that multiple suppliers can be qualified with minimal rework.
-
Negotiate flexible commercial terms: Include price-indexed clauses, call-off arrangements, and options for capacity ramp-down to balance cost control against supply reliability.
-
Explore licensing/brand partnerships selectively: For OEMs seeking rapid channel entry, licensing established lighting brands or co-branding premium driver modules can compress commercialization timelines.
-
Monitor consolidation signals: Use our scenario triggers to identify when to pursue acquisitions versus strategic alliances based on supplier valuation spreads and capacity availability.
Why PW Consulting’s full study is essential for executable plans in 2026
This preview outlines the high-level forces reshaping the LED drivers market, but the execution advantage comes from granular, validated inputs: supplier-specific performance benchmarking, subsegment demand elasticities, BOM-level sensitivity models, and contractual templates that translate strategy into procurement and engineering actions. Our full report packages those assets with a supply-risk index, scenario-adjustable financial models, and an annotated short-list of strategic targets — tools designed to move teams from planning to measurable outcomes within a single fiscal cycle.
Conclusion
The LED drivers market is in the midst of a structural upcycle driven by electrification, regulatory pressure for efficiency, and semiconductor-driven performance gains. The 10.1% CAGR through the forecast horizon encapsulates both the growth opportunity and the implicit complexity every executive must manage in 2026. Success will belong to organizations that combine rapid technical adoption, disciplined supply resilience, and commercially savvy partnerships. PW Consulting’s full market intelligence is built to accelerate those capabilities — the high-resolution segmentation, supplier dossiers and modeling workbooks that underpin confident, defensible decisions are included in the full report available from our research portal.
For detailed analysis of this topic, please visit the official page: LED Drivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com