

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Graphite Heat Exchanger Market to Hit USD 456.11M by 2032 at 9% CAGR

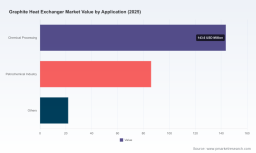
Graphite Heat Exchanger Market — Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest Graphite Heat Exchanger Market study (base year 2025; historical 2020–2025; forecast 2026–2032) is designed to be the operative intelligence pack that senior executives, procurement leads, and product strategists will use to shape decisions in 2026. The market is on a robust growth trajectory — our top-line modelling shows a compound annual growth rate (CAGR) of 9.0% over the 2026–2032 forecast window, with the total market expanding from USD 251.38 Million (base year 2025) toward USD 456.11 Million by 2032. This report translates that macro momentum into executable options: where to invest, which partners to prioritise, and how to de-risk projects in ultra-corrosive process environments.
Graphite Heat Exchanger Market
Why this study matters for 2026
-
Timing: 2026 is a hinge year for buyers and suppliers. Accelerating chemical production volumes and renewed capital expenditures across refining and specialty chemicals are creating near-term demand spikes while long-term technical requirements are shifting.
Graphite Heat Exchanger Market -
Margin pressure and supply-side risk: Raw material dynamics and selective industry consolidation are already influencing supplier economics and lead times; procurement strategies formed in 2026 will determine coefficient of variability in 2027–2030 performance.
Graphite Heat Exchanger Market -
Regulatory and technical compliance: Graphite heat exchangers must comply with international pressure and manufacturing codes and are routinely validated by independent authorities; this elevates the importance of certified supply chains and validated installation practices in 2026 procurements.
Top-line market context (concise)
Our market model integrates historical revenue flows (2020–2025) and forward-looking demand drivers to produce a consistent, auditable series of annual market values in USD Million. The market demonstrates steady expansion through the forecast horizon, with accelerating adoption in corrosive-service applications and an increasing value placed on engineered solutions that balance durability with serviceability. Market concentration is moderate: the combined revenue share of the top three suppliers is in the high 30s (CR3 ≈ 38%), and the top five reach just over half the market (CR5 ≈ 52%), indicating room for both competitive differentiation and targeted consolidation plays.
What the report delivers — practical content for executives
-
Integrated demand and revenue forecasts (2026–2032) with scenario-mode outputs for Base / Upside / Downside planning.
-
Supply-side intelligence: validated supplier profiles, capability matrices, and production capacity assessments — including plant certifications and testing accreditations where applicable.
-
Commercial playbooks: procurement scorecards, contract terms to mitigate price volatility, and lifecycle cost models for retrofit versus replacement decisions.
-
Technical dossiers: comparative heat-transfer performance briefs, corrosion-resistance benchmarks, and installation/maintenance best practices aligned to international pressure codes and third-party testing protocols.
-
Risk and opportunity maps: raw-material sensitivity analysis, regulatory risk heatmaps, and an M&A/opportunity shortlist framework (deal prioritisation, typical value multiples, integration risk pointers).
-
Case studies and worked examples: project-level capital and operating expense (CapEx / OpEx) modelling, commissioning timelines, and warranty / aftermarket frameworks to align supplier incentives.
Market dynamics shaping decisions in 2026
-
Upstream demand push: Global chemical production volumes rose materially in recent periods, creating incremental need for corrosion-resistant heat transfer equipment. This underlying demand is a primary driver of the market’s near-term growth profile.
-
Raw material volatility: Graphite pricing exhibits regional spreads that matter for procurement and landed cost. Recent price points show meaningful divergence across geographies, affecting supplier margins and, by extension, lead times and availability for engineered graphite components.
-
Standards and independent validation: Products are increasingly expected to meet international pressure codes and to be independently tested and certified. For buyers, this raises the bar for supplier selection and creates commercial value for vendors with documented third‑party validation and traceable process controls.
-
Technological differentiation: Manufacturers compete on multiple vectors — block architectures, shell & tube adaptations, plate designs, impregnation techniques, and sealing systems. The winners will be those that convert performance advantages (thermal efficiency, corrosion life) into reduced total cost of ownership.
Competitive landscape — who matters and why
The market is populated by specialist engineering houses and materials groups. The profiles below indicate strategic positions and implications rather than exhaustive vendor scorecards (full supplier benchmarking is included in the report).
-
CG Thermal LLC (Houston, USA) — Known for Impervite® advanced graphite heat exchangers and multiple design variants targeted at ultra-corrosive acids and chemical processing. Strategic implication: strong North American engineering presence and product portfolio oriented at high-value corrosive-service projects; relevant for partnerships on turnkey deployments and co‑development of site‑specific solutions.
-
Mersen (Paris, France) — Offers a breadth of engineered graphite heat-exchange platforms. Strategic implication: breadth and scale make them a natural partner for multinational buyers seeking uniform specifications across regions.
-
Graphite India Limited (Kolkata, India) — Focused on impervious graphite exchangers for phosphoric acid and other chemical processes. Strategic implication: strong regional manufacturing cost advantage for projects in South Asia and adjacent corridors; attractive for cost optimisation in greenfield projects.
-
SGL Carbon SE (Wiesbaden, Germany) — Supplies DIABON® graphite heat exchanger products and is reorganising parts of its carbon business to sharpen focus on core competencies. Strategic implication: restructuring may create near-term supply opportunities or acquisitive behaviour; buyers should monitor announcements and evaluate continuity plans.
-
Toyo Tanso Co., Ltd. (Osaka, Japan) — Specialist in isotropic graphite and advanced components. Strategic implication: high-spec material capability that supports performance-sensitive applications (high temperature, specialty chemistries).
-
Nantong Sunshine Graphite Equipment Technology (Nantong, China) — Offers block and shell & tube solutions with full-service compliance to international standards. Strategic implication: attractive for cost-competitive procurement with focus on meeting export certifications.
Recent vendor moves are instructive: CG Thermal’s exhibition presence in late 2025 reaffirms market-facing product launches and application advocacy; SGL Carbon’s announced restructuring in November 2025 underscores potential supplier-side consolidation and the need for contingency sourcing plans.
Strategic imperatives for executives in 2026
-
Hedge raw‑material exposure: lock in graphite supply contracts where possible, build pricing collars, and evaluate strategic inventory buffers for critical projects.
-
Prioritise certified suppliers: require documented compliance with international pressure codes and independent testing as a minimum commercial prerequisite to reduce downstream commissioning risk.
-
Adopt lifecycle procurement KPIs: move beyond purchase price to metrics tied to plant uptime, cycle‑life, servicing intervals, and total cost of ownership — revise supplier SLAs accordingly.
-
Design modularity and retrofit pathways: favour graphite exchanger designs that enable staged installations and simplified maintenance to accelerate payback and reduce operational disruption.
-
Monitor consolidation and M&A windows: with the top five vendors controlling a significant portion of market revenue, there will be tactical opportunities to acquire technology or capacity at attractive multiples during restructuring waves.
-
Invest in after‑sales capability: service, spare stocking, and certified refurbishment deliver outsized margin protection and customer lock-in in corrosive-service markets.
How PW Consulting’s research supports 2026 execution
This study is built to be operational: it includes downloadable cost build-ups, contract templates, an independent supplier maturity matrix, installation and commissioning checklists, and scenario-ready demand models that you can plug into capital planning tools. Importantly — and deliberately — the public executive brief that you are reading now highlights strategic direction and the market’s growth path while withholding the granular regional, product-type, and application-level splits that underpin our recommendations. Those detailed tables and client-ready slide decks are accessible through the report landing page, where you can obtain the full dataset, primary interview transcripts, and bespoke advisory options.
Final note — a 2026 playbook in motion
Entering 2026, buyers and suppliers in the graphite heat exchanger market face a choice: treat the next 18 months as a short-term procurement cycle, or reconfigure supply chains and product strategies to capture durable value across the forecast horizon. With a projected market expansion at a 9.0% CAGR through 2032, the upside from early, well-constructed moves is significant. PW Consulting’s Graphite Heat Exchanger Market study is intended to be the actionable reference for those moves — combining vetted market sizing, supplier intelligence, technical deep dives, and executable playbooks that convert insight into outcomes. For the full dataset, segmentation tables, and supplier scorecards referenced here, please consult the full report available on our website.
For detailed analysis of this topic, please visit the official page: Graphite Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com