

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EDM Market to Reach USD 2,530 Million by 2032

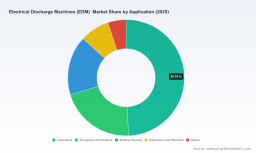
Electrical Discharge Machines (EDM) Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
PW Consulting’s latest EDM market study delivers a decision-grade view for executives planning through 2026 and beyond. Using a base year of 2025 and a historical window covering 2020–2025, the report models the market over a 2026–2032 forecast horizon. At the macro level, the global EDM market reached approximately 1,730 Million USD in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.8% through the forecast period, reaching roughly 2,530 Million USD by 2032. Market concentration is moderate, with the three-largest vendors accounting for approximately 35% of industry sales and the top five about 45% — a structure that creates both bargaining power for leading suppliers and opportunity for focused challengers.
Electrical Discharge Machines (EDM) Market
Why this research matters for 2026 strategic choices
-
Capital allocation and timing: Buyers and manufacturers face trade-offs between upgrading legacy sinker/wire platforms, investing in high-precision micro-drilling capability, or outsourcing from certified specialist shops. Our study highlights the inflection points where investment yields optimal payback given expected volume and product complexity trends.
Electrical Discharge Machines (EDM) Market -
Supplier selection and risk management: With moderate concentration among incumbents, procurement teams must balance price, technology fit, aftermarket support and regulatory readiness. The report provides a supplier evaluation framework tailored to medical-device and aerospace supply chains where compliance is non-negotiable.
Electrical Discharge Machines (EDM) Market -
M&A and partnership screening: For corporates and PE sponsors, the EDM space is attractive for bolt-on consolidation or capability accretions. We identify the operational and commercial KPIs that predict successful integration and value capture without exposing proprietary subsegment tables here.
-
Regulatory positioning: Medical device applications — a growth engine for precision EDM — are governed by standards and regulations that materially affect time-to-market and allowable process windows. Our research links regulatory constraints to unit economics and go/no-go product decisions.
Market dynamics and near-term catalysts
The EDM market’s 2020–2025 trajectory reflects resilient demand for high-precision machining across medical, aerospace and high-end electronics applications. Key structural forces shaping the 2026 landscape include technological evolution in electrode and wire handling, increased adoption of automation and software-enabled process control, and tightening regulatory oversight where EDM is used in critical component manufacturing.
-
Precision medical manufacturing as a demand anchor: Medical device manufacturers continue to rely on EDM for implants, minimally invasive instrument components, and micro-scale features that conventional machining cannot economically deliver. Recent industry activity — including certification updates and regulatory filings — underscores the importance of traceable, validated EDM process chains.
-
Regulatory and certification tailwinds: Several regulatory requirements now explicitly affect EDM operators serving medical supply chains: ISO 13485 certification expectations, application of FDA 21 CFR Part 820 quality-system controls, EU medical-device directives, and MDSAP-related obligations for firms operating across multiple jurisdictions. These rules raise the baseline for shop-floor documentation, change control and supplier audits — shifting procurement decisions toward providers that can demonstrate robust compliance evidence.
-
Supply-side innovation and service models: Manufacturers are pushing integrated solutions — combining machines, consumables, and digital process control — and aftermarket services such as predictive maintenance and qualification-as-a-service. These models change the cost-of-ownership calculus and privilege vendors offering end-to-end validated workflows.
-
Recent market signals: Product communications and certifications from both OEMs and contract manufacturers point to near-term opportunity clusters. Examples include new EDM capability catalogues targeted at surgical instrumentation, regulatory filings that reference EDM-produced components, and ISO/MDSAP certification events at contract EDM shops — all indicating that demand and compliance readiness are aligning.
Competitive landscape — who matters and why
The competitive map combines global OEMs with regional specialists. Leading firms differentiate on precision, process validation, and aftermarket support. Our analysis focuses on the companies that matter to buyers and investors because of their technological depth or channel reach:
-
Makino (Japan) — Known for sinker and wire EDM systems with a strong foothold in medical device machining, particularly implants and precision instruments. Their product mix emphasizes repeatability and validation-ready workflows for regulated manufacturing.
-
GF Machining Solutions (Switzerland) — Offers wire-cutting and sinker EDM platforms targeted at high-precision medical components, with a global service network and industry-oriented process packages that reduce qualification timelines for OEMs.
-
Sodick (Japan) — Specializes in high-precision wire and sinker EDMs, with particular strengths in micro-EDM and process stability, attractive to tier-1 subcontractors serving medical and aerospace customers.
-
Mitsubishi Electric (Japan) — Focused on wire EDM systems designed for extreme accuracy applications; their engineering pedigree and control systems are appealing where tolerance and surface integrity are mission-critical.
-
CHMER (Taiwan) — Competes on value and application breadth across wire-cut and die-sinker machines, often winning cost-sensitive or mixed-product-line contracts.
Across the field, differentiation is less about raw machine horsepower and more about validated process packages, integrated software for process control, and aftermarket qualification services. Given the modest CR3/CR5 concentration, opportunities exist for specialist entrants that can pair technology with regulatory competence.
What the report delivers — a practical toolkit
This study is designed to be directly usable in boardroom decisions and operational planning. Core actionable outputs include:
-
Transparent market-sizing and scenario models (2020–2032) with sensitivity tests for volume, ASP and adoption curves.
-
Investment case templates and capex ROI calculators tailored to wire, sinker and micro-drilling use-cases.
-
Supplier evaluation matrix and scorecards covering technology fit, compliance posture, service SLA and total cost of ownership.
-
Regulatory compliance checklist and recommended audit scripts aligned with ISO 13485, FDA 21 CFR Part 820, MDSAP practices and applicable EU requirements.
-
Technology roadmap and adoption playbook for automation, in-process monitoring and digital twinning to reduce qualification time and scrap.
-
M&A screening criteria and integration playbooks for acquiring shops or capability bolt-ons without disrupting existing validated processes.
-
Case studies demonstrating supplier transitions, process re-qualification, and rapid capacity ramp strategies for regulated programs.
To respect competitive sensitivity and preserve the trailer-style dynamic of the brief, we showcase methodology and findings here while intentionally withholding granular subsegment tables, regional splits and raw transaction-level datasets. Those detailed data and appendices are available via the full report on our site.
How procurement, operations and strategy teams should use the analysis in 2026
-
Q1 — Rapid supplier triage: Use our supplier scorecards to narrow candidate lists to those meeting regulatory and technical thresholds. Prioritize firms with demonstrated ISO 13485/MDSAP certificates when medical-device qualification timelines are tight.
-
Q2 — Capital allocation and pilot projects: Run head-to-head pilot programs using the report’s capex ROI templates. Validate not only machine performance but also change-control and documentation processes required for device approvals.
-
Q3 — Scale and compliance lock-in: For designs entering scale production, leverage the process-validation playbook to minimize rework during regulatory submissions. Ensure supplier SLAs include traceability and retention of process records.
-
Ongoing — Strategic portfolio decisions: Use our scenario models to test insourcing vs. outsourcing strategies under different demand and ASP growth paths, and to stress-test integration plans for any planned acquisitions.
Final perspective and next steps
The EDM market presents a rare combination: technologically mature platforms undergoing incremental innovation at a time when regulatory and product complexity are increasing demand for validated, high-precision capability. For decision-makers setting 2026 priorities, the questions are tactical (which machines, which suppliers, when to qualify) and strategic (where to build proprietary capability, when to buy). PW Consulting’s report converts those questions into executable options — from procurement scorecards to acquisition checklists — while preserving the proprietary raw data in the full deliverable.
If your 2026 plan depends on minimizing qualification risk, optimizing total cost of ownership, or capturing value through consolidation, the full report contains the segment-level analytics, regional models and supplier benchmarking you’ll need to proceed confidently. For access to the complete datasets, appendices and customizable decision tools, please visit the source page to purchase the full study or to commission a tailored workshop with our industry specialists.
For detailed analysis of this topic, please visit the official page: Electrical Discharge Machines (EDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com