

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Perlite & Vermiculite Market to Reach USD 6.30B by 2032, 5.75% CAGR

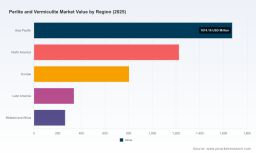
Perlite and Vermiculite Market: Strategic Imperatives for 2026 — PW Consulting Preview
As companies set budgets and capital priorities for 2026, the expanded perlite and exfoliated vermiculite complex presents a mix of steady demand, material-specific technical challenges, and opportunity windows for firms that move with speed and clarity. PW Consulting’s new market study — anchored to a 2025 base year and projecting through 2032 — synthesizes historical behavior (2020–2025) with forward-looking scenarios (2026–2032). The market is forecast to expand at a compound annual growth rate (CAGR) of 5.75% over the forecast window. To frame the scale: the global market grew from a multibillion-dollar level in 2020 to an elevated 2025 base, and is anticipated to continue its upward trajectory into the early 2030s. This preview explains why our analysis is strategically material for decisions you must take in 2026, what proprietary insight the full report contains, and how leading players are already positioning themselves.
Perlite and Vermiculite Market
Why 2026 Is a Decision Point
-
Demand stability meets structural change. Longstanding end uses — construction insulation and lightweight aggregates, horticultural substrates, and industrial filtration — continue to underpin baseline demand. Simultaneously, higher-performance applications (precision filtration, engineered lightweight composites) and regulatory pressures (workplace dust control and product stewardship) are driving material differentiation and premiumization.
Perlite and Vermiculite Market -
Supply-side dynamics are granular and site-specific. Perlite and vermiculite are mined, expanded, and processed in localized clusters. Ore quality and processing technology materially affect product performance: for example, crude vermiculite ore typically includes 3–4 percentage points of moisture that affect expansion characteristics during exfoliation — a technical detail that alters yields and product mix at plant level.
Perlite and Vermiculite Market -
Regulatory and trade considerations are non-trivial. Perlite is widely regulated as a “nuisance dust,” requiring consistent compliance investments across jurisdictions. Moreover, expanded perlite and vermiculite are classified under a specific HS code (6806.20), an operational detail that influences customs treatment, duties, and cross-border sourcing strategies.
-
Market structure favors both scale and nimbleness. The industry is fragmented — the three- and five-firm concentration ratios remain low relative to many mineral value chains — which both limits pricing power among global majors and creates acquisition opportunities for firms seeking route-to-market expansion or downstream integration.
What PW Consulting’s Report Delivers (Practical, Executable)
-
Robust market sizing and scenario modeling: historical series (2020–2025), base-year calibrated estimates (2025), and three scenario-led projections through 2032 that stress-test demand against macro shocks, energy price regimes, and policy shifts.
-
Demand-driver analytics: differentiated by application archetypes and value-chain position, with quantified growth levers and elasticity assumptions to help forecast product-specific volumes under alternative adoption curves.
-
Supply-constraint mapping: deposit quality, beneficiation and expansion capacity, and logistic chokepoints mapped to a supplier risk scorecard for near-term (12–18 month) and medium-term (18–36 month) horizons.
-
Price benchmarking and input-cost models: indexed to energy and freight vectors, with sensitivity matrices for ore-grade variation, expansion yield, and milling loss.
-
Commercial playbooks: go-to-market options for producers, tolling and contract-manufacture models for downstream users, and M&A scorecards for acquirers targeting consolidation or capability acquisition.
-
Regulatory and ESG checklists: compliance pathways for nuisance-dust controls, product labeling implications of HS-classification, and practical steps for reducing lifecycle emissions in expansion processing.
-
Operational deep-dive annexes: exfoliation process variables, particle-size control for filtration media, closed-cell expanded product characteristics, and guidance for pilot-scale trials.
Data-Driven Snapshot (Preview)
PW Consulting’s calibrated market series shows consistent expansion from the early 2020s into the mid-decade, with the base-year (2025) reflecting both cyclical recovery in construction and steady growth in horticulture and industrial segments. The forecast path we present to 2032 is driven by a 5.75% CAGR, which implies meaningful growth potential for firms that can align capacity and product quality with evolving end-use requirements. Because this preview intentionally omits granular regional and application splits, the full report contains the detailed breakdowns that underwriting teams and corporate strategists will require to model investment returns or to size M&A targets.
Competitive Landscape — How to Read the Field
-
Global majors vs. regional specialists: Firms such as Imerys (France) exemplify a platform play, investing in product innovation and engineered filter aids. A concentration of capabilities among a handful of global groups coexists with a long tail of specialist processors and miners, particularly in North America, Europe, and parts of Asia and the Mediterranean basin.
-
Service and product differentiation is winning share: Companies that pair basic expanded perlite with application-specific processing (milling to filter-grade size, closed-cell formulations, or horticultural blends) are capturing premium margins. Recent product innovations demonstrate the commercial payoff for precision particle control and brand positioning.
-
Recent movements to note: capacity and capability investments in 2025 indicate where firms expect near-term demand to be strongest — examples include precision filter-aid product launches and new or expanded processing facilities. These moves materially alter regional supply balances and should inform sourcing decisions in 2026.
-
Fragmentation creates acquisition windows: low overall market concentration (three- and five-firm CRs in the mid-20% range) means numerous attractive bolt-on targets exist for companies seeking scale or route-to-market in priority countries. However, successful roll-ups require fast post-acquisition integration of quality control and logistics to avoid margin erosion.
Strategic Playbook for 2026 Executives
-
Prioritize supply-security contracts with tiering by ore quality. Because ore characteristics materially affect expansion yields and product consistency, securing multiple source options reduces operational risk.
-
Invest selectively in downstream differentiation. Opportunities in precision filtration, engineered lightweight systems, and horticultural substrates reward modest R&D and pilot-plant investment.
-
Time capacity investments to demand signals, not sentiment. With a multi-year CAGR in the mid-single digits, capital projects should be phased and include contingency for energy and freight volatility.
-
Leverage regulatory compliance as a commercial asset. Demonstrable controls on dust emissions and product stewardship can shorten procurement cycles with larger industrial buyers and unlock premium contracts.
-
Use M&A to buy capabilities, not just volume. Assets that add proprietary processing (milling to precise particle distributions, closed-cell expansion capability) or established distribution in high-value end markets will outperform low-synergy volume acquisitions.
-
Operationalize traceability and quality analytics. Data-rich production monitoring—tracking ore moisture, expansion yield, and particle-size distributions—reduces returns and supports premium product claims.
Risks and Contingencies to Monitor in 2026
-
Input-cost shocks: energy and freight spikes rapidly erode margins in expansion-intensive processes; hedging and flexible tolling contracts are cost-effective mitigants.
-
Regulatory tightening: tighter dust-control requirements or shifts in classification could necessitate plant retrofits, particularly in jurisdictions raising occupational health standards.
-
Ore variability: site-level differences in moisture and mineralogy impact yields — realistic worst-case yield scenarios should be built into project appraisals.
-
Geopolitical and trade friction: HS-code aligned duty treatments and localized protective measures can change net landed costs faster than capex cycles permit adjustment.
Illustrative Industry Signals (Selective)
-
Product innovation continues to accelerate: premium filter-aid grades and milled perlite products released in 2025 signal buyer willingness to pay for performance enhancements rather than commodity pricing alone.
-
Capacity moves are geographically targeted: new or enlarged processing facilities opened in 2025 show where suppliers are betting on demand concentration; such investments shift regional logistics economics and competitive dynamics.
-
Public production disclosures underscore materiality: disclosed production volumes and values from established regional players provide hard checkpoints against which private company claims should be validated.
Concluding Guidance — How to Use This Preview
This article is intentionally a strategic “preview” — it highlights the analytical lens and executive actions that PW Consulting recommends for 2026 without exposing the granular regional, application, and pricing tables that underpin investment-grade decisions. If your firm is evaluating capacity projects, acquisition targets, or supply contracts in perlite and vermiculite, the full PW Consulting report provides the detailed split-views, price curves, and risk-scored supplier matrices you need to underwrite decisions with confidence.
For companies planning to allocate capital or revise procurement strategies in 2026, time is the critical variable: early movers that align technical capability with proven demand pockets — while effectively managing dust regulation, ore variability, and logistical friction — will convert the underlying mid-single-digit growth trajectory into outsized returns. PW Consulting’s full study delivers the operational detail and scenario-tested recommendations required to make those calls.
For detailed analysis of this topic, please visit the official page: Perlite and Vermiculite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com