

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Home Audio Equipment Market to Hit USD 47.99B by 2032 at 7.5% CAGR
By pmarketresearch, 2026-07-13
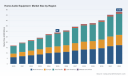
Home Audio Equipment Market — 2026 Strategic Outlook
PW Consulting’s latest Home Audio Equipment Market primer is written for senior leaders who must convert fast-moving market signals into high-confidence 2026 decisions. Built on a base year of 2025 and a detailed historical series from 2020–2025, our research projects the market forward through 2032 at a compound annual growth rate of 7.5%. That trajectory — from roughly USD 29 billion in 2025 to just under USD 48 billion by 2032 — creates both expansion opportunities and strategic inflection points for product, channel, and supply‑chain choices. This article explains the strategic value of the full study, teases its analytical depth, and outlines the practical actions executives should prioritize in 2026. (Note: the report contains full subsegment tables, proprietary scenario models, and granular regional breakdowns — these are intentionally omitted here to direct readers to the full report page.)
Home Audio Equipment Market
Why this research matters for 2026 corporate strategy
Two defining features shape decision-making in 2026: accelerating product convergence and heightened external risk. On the demand side, connectivity, immersive formats, and software-enabled user experiences are re-shaping customer value propositions. On the supply side, tighter controls on e‑waste exports and a renewed policy focus on critical minerals are changing sourcing economics and compliance costs. Our study synthesizes these forces into a single, decision‑ready narrative: the home audio market is large, growing at a steady mid‑single-digit CAGR, and strategically fragmented — meaning that well‑timed investments and partnerships can produce outsized returns if executed with operational and regulatory foresight.
Home Audio Equipment Market
What’s in the report — pragmatic, actionable content
- Forward-looking revenue and unit forecasts (2026–2032) by product family and connectivity architecture, built from bottom‑up adoption curves and top‑down macro scenarios.
- Scenario models that stress-test outcomes against three downside drivers: supply‑side mineral shocks, tightened e‑waste export controls, and a slower-than-expected smart‑home upgrade cycle.
- A competitive playbook with parallel benchmarking: R&D emphasis, software/firmware roadmaps, go‑to‑market strategies, and margin pressure points — enabling quick SWOT synthesis for potential targets.
- Channel and pricing archetypes, including promotional elasticity, subscription bundling levers, and trade vs. direct-to-consumer margin calculus.
- Supply‑chain risk heatmaps and a supplier segmentation matrix that quantify the operational impact of critical‑minerals constraints and export regulations.
- An M&A screening toolkit and integration checklist targeted to buyers hunting scale in software, services, or regional reach.
We present all of the above with the accompanying primary data tables, downloadable financial models, and a decision-scripting appendix to translate analytics into 90/180/360‑day action plans. To preserve the commercial value of those deliverables, detailed subsegment dollars and region/application percentages are accessible through the full report page.
Home Audio Equipment Market
Competitive landscape: who’s shaping the market and why it matters
The market remains strategically fragmented: the top three global players account for a modest share of industry revenue, and the top five only modestly more — a concentration profile that keeps both independent specialists and platform incumbents in play. The leading vendors exemplify divergent routes to growth.
- Bose Corporation — continuing to lean on premium hardware and differentiated audio engineering, Bose combines high‑value wireless speakers and integrated home‑theater systems with software and ANC leadership. For incumbents considering premium lines, Bose’s approach underscores the importance of sustained R&D and brand premiumization.
- Sonos Inc. — Sonos is the market poster child for multi‑room ecosystems and software‑driven value capture. Recent product introductions (including a next‑generation flagship soundbar and refreshed subwoofer and speaker models) reinforce a strategy that mixes product upgrades with platform control and services monetization.
- Harman/JBL — JBL’s deep pro-sound heritage has been translated into high‑power Bluetooth speakers and home theater systems that emphasize performance-to-price ratios. Their posture highlights the opportunity in value-dense audio products that pair mass-market distribution with credible performance claims.
- Klipsch — Klipsch emphasizes efficiency and acoustic design, increasingly coupling premium horn‑loaded speaker architecture with strategic partnerships for powered systems. Their collaboration patterns foreshadow one consolidation pathway: brand-led partnerships to accelerate product refresh cycles.
- Onkyo — Onkyo’s strength in AV receivers and multi‑channel amplification speaks to the enduring relevance of dedicated components for enthusiasts and premium home‑theater buyers. Refreshes announced at recent trade shows signal ongoing demand in higher‑end audio processing hardware.
Recent industry product and warranty moves matter beyond PR: extended warranty programs and collaborative product launches are becoming competitive differentiators. For example, extended warranties by specialist manufacturers and co‑branded hardware partnerships announced at major trade shows change the calculus on post‑sales cost and customer lifetime value — important inputs in our models and deal screens.
Material and regulatory dynamics that will shape supplier strategy
Two policy shifts merit particular attention in 2026 planning:
- As of January 1, 2025, revised Basel Convention practices put prior written consent requirements on international shipments of e‑waste and scrap. That rule raises compliance costs for cross‑border refurbishment, recycling, and downstream manufacturing flows.
- Critical‑minerals listings in 2025 included several materials widely used in audio manufacturing — specifically rare‑earth elements and mainstream semiconductors/raw materials. The presence of these inputs on formal lists increases geopolitical and supply‑chain risk and makes second‑source strategies and materials substitution high‑priority investments.
Operational responses embedded in the report include supplier dual‑sourcing playbooks, design‑for‑recyclability checklists, and a quantified total cost of ownership model that internal teams can use to evaluate nearshoring, vertical integration, or long‑term contracts with guaranteed offtake.
Key strategic imperatives for executives in 2026
- Prioritize software and product‑services: convert hardware buyers into recurring‑revenue customers through subscription services, calibration ecosystems, and firmware‑driven feature tiers.
- Elevate materials strategy: embed critical‑minerals exposure into every sourcing and capital decision, and accelerate design options that reduce reliance on at‑risk inputs.
- Use differentiated warranties and service offers as competitive weapons — longer warranties can justify price premiums but must be net‑modeled against service infrastructure costs.
- Look for M&A targets that add software control points or extend channel reach; in a moderately fragmented market, small bolt‑ons can materially improve gross margin profiles.
- Build export‑compliant refurbishment and recycling pathways now to avoid future disruptions tied to e‑waste controls.
- Tier assortments by connectivity and use‑case: while wireless and smart features are growth drivers, dedicated high‑fidelity hardware still merits investment as a margin anchor.
- Stress‑test pricing under three scenarios in your P&L: base case (steady growth), premiumization acceleration, and a materials‑driven cost shock.
How to use the PW Consulting report to make 2026 choices
Executives approaching 2026 with budget authority will find three immediate uses for our dataset and tools:
- Investment screening: use the included M&A scoring model to compare targets on revenue synergies, product overlap, and integration cost against projected CAGR-driven growth lanes.
- Product roadmapping: align R&D spend with forecasted demand buckets and the report’s adoption curves; accelerate features that support subscription and ecosystem lock‑in.
- Supply‑chain playbooks: apply the supplier risk heatmap and total‑cost model to decide between nearshoring, long‑term contracts, or inventory hedges for critical components.
Each deliverable is accompanied by an executive one‑pager summarizing the strategic implications and a recommended 90‑day action plan for leadership — enabling rapid alignment between strategy teams and operating units.
Conclusion and next step
The home audio market’s steady mid‑single‑digit growth creates an environment where strategic clarity — not guesswork — separates winners from the rest. PW Consulting’s Home Audio Equipment Market report blends scenario‑based forecasting, hands‑on competitive intelligence, and operationally realistic playbooks designed for immediate execution in 2026. If your team needs the granular revenue models, product‑level elasticities, and regional channel projections that guide capital allocation and M&A choices, the full report and interactive model are available at our report page. Contact PW Consulting’s market practice to schedule a walk‑through and tailored brief for your board or investment committee.
For detailed analysis of this topic, please visit the official page: Home Audio Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Disposable Ostomy Bags Market to reach USD 306.8M by 2032 at 5.4% CAGR
By pmarketresearch, 2026-07-13
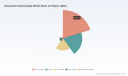
Disposable Ostomy Bags Market — Strategic Insights for 2026 Decision‑Makers
The disposable ostomy bags market is entering the mid‑2020s with steady expansion, structural change and policy exposures that will determine winners and laggards through the next planning cycle. Our latest PW Consulting market study (base year 2025; historical window 2020–2025; forecast 2026–2032) shows the global market expanding from roughly USD 163 million in 2020 to USD 215 million in 2025, and projecting to reach approximately USD 307 million by 2032 at a compounded annual growth rate (CAGR) of 5.4%. This growth is meaningful for device manufacturers, suppliers, payers and health systems planning capital allocation, manufacturing footprints, or M&A for 2026 and beyond.
Disposable Ostomy Bags Market
Why this study matters for 2026 strategic planning
- Predictable expansion, evolving risk profile. The market’s mid‑single digit CAGR masks pockets of defensible revenue and persistent cost pressure — a dynamic that rewards disciplined margin management, regulatory readiness, and service differentiation.
- Concentration creates strategic leverage. The market is moderately concentrated: the top three players account for a clear majority of industry sales, and the top five widen that control further. That concentration shapes competitive behavior (pricing, channel access, clinical partnerships) and raises the bar for new entrants and niche players seeking scale.
- Policy and procurement are near‑term value levers. Recent regulatory and reimbursement developments (sterilization rules, bidding program inclusions and coverage clarifications) materially affect product cost structures and hospital procurement strategies in 2026 — making proactive payer engagement and tender playbooks essential.
- Operational resilience is now strategic. Single‑use disposables rely on medical‑grade materials and validated sterilization processes; supply chain fragility or compliance lapses translate quickly to commercial disruption.
Market dynamics and regulatory context — implications for operations and product strategy
- Sterilization compliance. New occupational exposure and engineering control expectations for ethylene oxide sterilization (EO) impose capital and O&M costs on sterilization-dependent suppliers. Firms must evaluate alternative sterilants, invest in EO engineering controls, or transfer sterilization to compliant third parties to maintain supply continuity and liability mitigation.
- Reimbursement and procurement shifts. Medicare policy clarifications and the inclusion of ostomy supplies within competitive bidding frameworks in 2026 alter purchasing behavior. Suppliers should anticipate tender price pressure, formulary negotiations and variability across local coverage determinations — requiring a coordinated reimbursement and contracting response.
- Regulatory product standards. Single‑use ostomy systems demand medical‑grade materials and quality systems (including ISO 13485 certification). Compliance is table stakes for market access and institutional procurement.
- Cost and material volatility. Raw material price swings, sterilization cost inflation and logistics constraints can erode margins. Firms that implement hedging, alternative material development and flexible manufacturing will protect profitability.
Competitive landscape — what the market structure means for strategic moves
The competitive field combines established global manufacturers with agile regional specialists. Major, globally recognized firms leverage broad brand portfolios, clinician relationships and integrated commercial channels; regional and niche players compete on service responsiveness, cost, or product specialization.
Disposable Ostomy Bags Market
- Global leaders. Established manufacturers with comprehensive one‑piece and two‑piece portfolios benefit from scale, established clinical trust and wide distribution networks. Their strategic advantages include deep clinical evidence libraries, global supply footprints and long‑standing reimbursements contracts.
- Regional challengers and specialists. Several UK-, European- and Asia‑based firms differentiate via targeted product ergonomics, regional reimbursement expertise and specialized accessory lines. These players are often more nimble in local tenders and clinician training programs.
- Private label and contract manufacturing. Growing pressure from procurement and tenders is elevating the role of private label and white‑label suppliers. Contract manufacturers that can offer regulatory certificates and sterilization pathways are increasingly attractive partners.
- Strategic implications. With the top three firms commanding a large share of the market and the top five extending that dominance, opportunities for consolidation, bolt‑on acquisitions, or exclusive distribution agreements are high‑value plays for firms seeking scale or market entry.
What PW Consulting’s report delivers (practical, decision‑grade content)
- Proprietary market model (2020–2032) with scenario modules calibrated to regulatory, reimbursement and supply chain stress tests.
- Demand drivers and adoption curve analysis — clinical drivers, patient demographics, and post‑surgical care pathway impacts.
- Regulatory and reimbursement playbook — practical checklists and a timeline of near‑term policy catalysts that will affect procurement and device design decisions in 2026.
- Supply chain and manufacturing risk map — sterilization pathway assessment, supplier concentration scoring, and cost‑to‑serve modelling.
- Competitive profiling and commercial benchmarking — strategic positioning, portfolio strengths, innovation vectors and go‑to‑market tactics for the leading and regional players.
- Actionable commercial strategies — tender playbooks, payer engagement templates, pricing elasticity analysis and product portfolio rationalisation frameworks.
- M&A and partnership shortlist methodology — target characteristics, valuation heuristics and integration risk checklists tailored to ostomy supply dynamics.
- Executive dashboards and KPIs — recommended metrics for board‑level monitoring and investor diligence in 2026.
Seven practical actions for executives to prioritize in 2026
- Confirm sterilization capacity and compliance paths. Conduct a rapid EO impact assessment, identify alternative sterilization partners or technologies, and quantify required capex or outsourcing costs. Prioritize assets that can be certified under new EO controls or shifted to compliant third parties.
- Rework reimbursement and tender playbooks. Model the financial impact of competitive bidding and local coverage variations; develop flexible pricing ladders and tender support packages (clinical training, bundled services) to protect margins.
- Segment‑led portfolio rationalisation (without guesswork). Use usage‑based profitability models to identify SKUs for premium positioning, cost optimisation or discontinuation — focusing R&D and marketing spend where clinical differentiation and payer willingness‑to‑pay align.
- Hedge supply risk. Establish multi‑sourcing for critical materials and negotiate longer‑term contracts with sterilization providers; consider regional contract manufacturing to shorten lead times for priority markets.
- Invest in clinician and patient support services. Differentiate beyond the pouch with digital adherence, product education and remote monitoring solutions that increase stickiness and justify premium pricing.
- Prepare M&A and partnership playbooks. Target regional leaders that offer distribution shortcuts or niche product portfolios; prioritize targets with clean regulatory pedigrees, ISO 13485 certification and validated sterilization pathways.
- Establish a regulatory horizon team. Track policy updates in sterilization, occupational safety and reimbursement; feed scenarios into quarterly commercial and CAPEX planning cycles.
Key metrics and watchlist for the next 12–18 months
- Global market growth vs. forecast (quarterly pace vs. the 5.4% CAGR baseline).
- Average selling price (ASP) movements and margin compression from tenders.
- Sterilization compliance spend and supplier capacity utilisation rates.
- Payer policy changes: competitive bidding outcomes, local coverage determinations and Medicare guidance updates.
- Supply chain red flags: single‑source materials, lead‑time spikes, and logistics costs.
- Clinical adoption indicators: hospital formulary insertions, clinical guideline updates and nurse/caregiver preference surveys.
PW Consulting’s analysis is designed to be pragmatic and action‑ready. We surface the macro trajectory (from about USD 163 million in 2020 to ~USD 215 million in 2025 and a projected ~USD 307 million by 2032), the competitive realities, and the operational and regulatory fault lines that will determine 2026 outcomes — while deliberately reserving granular subsegment tables, regional splits and proprietary company market shares for the full report.
Disposable Ostomy Bags Market
For decision‑makers preparing budgets, M&A pipelines, or manufacturing roadmaps for 2026, the premium value is in the layered scenarios, procurement playbooks and compliance checklists that translate market trends into executable initiatives. Access the full PW Consulting Disposable Ostomy Bags Market report for the detailed datasets, scenario outputs and tailored templates that will enable confident, evidence‑based decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Disposable Ostomy Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Engine Nacelle Market to Reach USD 844.28M by 2032 at 5% CAGR
By pmarketresearch, 2026-07-13
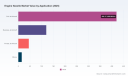
Engine Nacelle Market: Strategic Preview for 2026 Decision-Making
Executive preview
As PW Consulting’s Chief Industry Analyst, I present a focused, forward-looking synopsis of our Engine Nacelle Market study — a decision-grade briefing designed to influence capital allocation, partnership strategy, and product roadmaps in 2026. The global nacelle market is recovering and structurally evolving: after a five-year historical window marked by pandemic-related disruption and a mid-cycle dip, total industry revenues reached approximately USD 600 Million (base year 2025) and are projected to expand at a compound annual growth rate (CAGR) of about 5.0% through our 2026–2032 forecast horizon. That trajectory lifts the market toward the high USD 800 Millions by 2032 under our central scenario.
Engine Nacelle Market
Why this matters to corporate leaders in 2026
-
Timing of investment. The market’s steady 5% CAGR and the short-term rebound between 2024–2026 create a window to accelerate R&D and capacity investments before competition intensifies and supply constraints bite.
Engine Nacelle Market -
Risk of input-cost shocks. Raw-material volatility — notably disruptions to titanium supply — is no longer a theoretical tail risk. Procurement, sourcing strategy, and alloy-substitution workstreams must be prioritized to protect gross margins and delivery fidelity.
Engine Nacelle Market -
Certification & regulatory cycles. Compliance with airworthiness standards (e.g., FAA 14 CFR Part 33) imposes multi-year timelines for design changes and retrofits; understanding certification sequencing is critical when scheduling product launches and after-market offers.
-
Consolidation & competitive positioning. The market exhibits a moderate concentration among established nacelle system specialists and aero-structure Tier‑1s. Strategic M&A and targeted partnerships remain high-impact levers to secure program content and aftermarket streams.
Market sizing and near-term trajectory
Our base-year assessment (2025) places the global Engine Nacelle market at roughly USD 600 Million. Looking into 2026, we expect continued growth driven by fleet renewals, narrowbody program ramp-ups, and aftermarket demand as operators invest in fuel-efficiency and noise-reduction upgrades. By applying a 5% CAGR across our forecast period, the market reaches a substantively larger scale by 2032 under the central projection. Importantly, the historical series shows resilience: the sector recovered from a mid-period downturn and is now on an upward path, but that recovery is uneven across program types and supplier footprints — a nuance that matters for program-level bidding and capacity planning.
Key demand and technology drivers
-
Fuel efficiency and emissions. Airframe and powerplant OEMs continue to prioritize nacelle integrations that reduce engine fuel consumption and lifecycle CO2. Opportunities exist for advanced nacelle geometries, acoustic liners, and smooth integration with low-bypass and next-gen turbofan designs.
-
Noise regulation and community constraints. Stricter airport noise standards and community-driven curfews increase the value of nacelle-level noise-reduction technologies and may accelerate retrofit demand in specific markets.
-
Composite adoption and weight reduction. Lightweight composite nacelle components deliver lifecycle benefits but require robust manufacturing ecosystems and quality systems — firms that have demonstrable capabilities in advanced composites command pricing and program preference.
-
MRO and aftermarket monetization. Growth in installed base and retrofit cycles elevates the attractiveness of service contracts, spares provisioning, and on-wing support as higher-margin revenue streams.
Supply chain, raw materials, and resilience measures
Raw-material dynamics are a strategic constraint. Industry data indicate that geopolitical developments have disrupted key titanium supply lanes, creating potential shortages and elevated costs across the next 18–36 months. For procurement and operations leaders this translates into three actionable priorities: diversify qualified suppliers, accelerate alternative-material qualification programs where technically and regulatorily feasible, and implement tiered sourcing contracts that lock pricing or volumes through critical certification windows.
Competitive landscape — who matters and why
The Engine Nacelle ecosystem is anchored by a mix of integrated Tier‑1 nacelle systems specialists and a set of aero-structure and components-focused players. Our study includes detailed profiles and strategic assessments for the industry’s leading contributors. Highlights:
-
Safran Nacelles (France): Globally recognized for end-to-end nacelle programs and strategic engine partnerships. Strong program integration capabilities make them a natural contender on new OEM platforms.
-
Collins Aerospace (RTX Corporation, United States): A long-tenured systems supplier with a focus on certifiable solutions, lean manufacturing, and acoustic technologies. Their R&D in noise mitigation and program certification depth is a differentiator.
-
Spirit AeroSystems and Nexcelle (United States): Both bring program-specific strength: Spirit with volume programs for major narrowbody platforms, and Nexcelle with focused nacelle architectures and supplier collaborations across major OEMs.
-
European and specialized providers (GKN Aerospace, FACC, Aernnova, Liebherr-Aerospace, among others): These players compete on composite expertise, thrust reverser technology, and actuation systems — portfolio breadth versus specialization is the strategic trade-off.
-
Component- and systems-focused firms (The NORDAM Group, Triumph, Barnes Group Inc, Magellan Aerospace, Woodward, Ducommun): These suppliers occupy critical niches (actuation, fan cowls, thrust reversers) and are increasingly strategic partners for Tier‑1 integrators seeking supply-chain redundancy.
Across these participants, our competitive analysis identifies strategic vectors: (1) consolidation for program access, (2) vertical integration of high-risk subsystems, and (3) product differentiation via low-noise/weight architectures. Top players combine systems-integration credibility with certification track-records and global aftermarket networks.
Recent industry signals
Innovation remains active: for example, ST Engineering MRAS showcased advanced nacelle components at the Singapore Airshow in February 2026, signaling sustained technology investment and the competitive importance of airshow-leveraged demonstrations for program marketing. At the same time, regulators continue to set the pace; adherence to airworthiness standards such as FAA 14 CFR Part 33 is central to any product roadmap.
What our full report provides (practical, transaction-ready deliverables)
We designed this research as an operational tool for 2026 decision cycles. Components include:
-
Bottom-up market model: granular revenue build-ups by program vintage and an integrated forecasting engine that supports scenario toggles (demand shocks, price erosion, material-cost stress tests).
-
Program-level risk heatmaps: certification timelines, supplier single-source exposure, and aftermarket revenue visibility.
-
Supplier capability matrix: technical competencies (composites, actuation, acoustic liners), certification depth, global manufacturing footprint, and willingness to partner or divest.
-
Cost and margin diagnostic: bill-of-materials benchmarking, cost-to-manufacture ranges, and sensitivity to titanium and composite resin prices.
-
Commercial playbooks: bidding strategies for OEMs and suppliers, win themes for MRO service contracts, and integration checklists for joint ventures and acquisitions.
-
Scenario analyses and trigger points: early-warning indicators for supply-chain stress, demand shocks, and profitable entry/exit thresholds for investors and strategic buyers.
Each section is built to be operational: procurement teams get supplier negotiation levers; corporate development teams receive acquisition target scorecards; product leaders obtain certification-aware roadmaps.
Strategic recommendations for 2026
-
Prioritize supply-base diversification immediately. Lock in multi-year agreements with qualified alternative titanium and composite suppliers, and fund accelerated qualification programs to reduce single-source exposure.
-
Invest selectively in acoustic and aerodynamic innovations that deliver measurable fuel-burn and noise benefits. These deliver regulatory and commercial differentiation and can command aftermarket pricing premiums.
-
Define an MRO-led aftermarket strategy. Expand on-wing support offerings and spare-part inventories in markets where retrofit economics are compelling; margin-led services will smooth cyclicality and improve valuation multiples.
-
Push certification roadmaps earlier in the product development cycle. The lead time on airworthiness approvals is non-trivial; firms that front-end certification investments shorten time-to-revenue and reduce program risk.
-
Pursue bolt-on acquisitions for capability gaps rather than broad horizontal deals. Target firms that provide actuation, thrust-reverser expertise, or unique composite process know-how to accelerate program wins.
-
Build scenario playbooks for 2026–2028. Codify trigger points (material-cost thresholds, OEM order book shifts, regulatory changes) that will activate pre-defined responses: hedge contracts, ramp-up/down manufacturing, or strategic buyer approaches.
Final note — the strategic value of the full study
This preview is intended to establish the strategic calculus and the near-term imperatives for 2026. Our full Engine Nacelle Market research delivers the underlying datasets, program-level economics, and supplier scorecards necessary to execute the recommendations above. We intentionally limit disclosure here to preserve the actionable granularity found in the complete report — including program-by-program forecasts, supplier contracts analysis, and market segmentation — which remains accessible through the full study platform.
Next steps
For teams preparing capital plans, procurement strategies, or M&A pipelines in 2026, the optimal next step is a short briefing with our market modeling team to align scenario assumptions with your balance-sheet and program timelines. PW Consulting can run a tailored sensitivity analysis across your product and supplier portfolio to produce a 90‑day action plan that converts market visibility into defensible, immediate moves.
For detailed analysis of this topic, please visit the official page: Engine Nacelle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Circular Push-Pull Connectors Market to Reach USD 287M by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-13
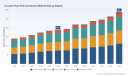
Circular Push‑Pull Connectors Market: Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, this briefing distills the strategic imperatives from our full Circular Push‑Pull Connectors Market study (base year 2025, historical period 2020–2025, forecast 2026–2032). The market is expanding on a steady trajectory—with a compound annual growth rate (CAGR) of 5.8% into the forecast window—and the total addressable market is projected to move from roughly USD 190 million in 2025 toward an expected market sizing in the high‑two‑hundreds by 2032. Below we map the high‑value decisions that should be made in 2026 and explain how our full report equips executives to act with confidence.
Circular Push Pull Connectors Market
Why this research matters for 2026
-
Timing matters: 2026 is a pivot year. Macro infrastructure and regulatory moves are catalyzing demand in specific end markets (compute, medical disposables, industrial automation), while raw‑material shocks and localized supply risks are compressing supplier margins and creating tactical windows for procurement optimization.
Circular Push Pull Connectors Market -
Actionable orientation: The full PW Consulting study is designed to convert market intelligence into executable workstreams—supplier scorecards, pricing levers, integration checklists, and prioritized product roadmaps—so leaders can translate insight into measurable cost avoidance, revenue capture, and reduced time‑to‑market.
Circular Push Pull Connectors Market -
Teaser principle: this briefing demonstrates our analytical depth and directional findings while reserving core segment and company‑level scorecard data for subscribers—ensuring your team gains competitive advantage by accessing the full dataset and Excel models.
High‑level market dynamics you must internalize
-
Growth profile: After consistent expansion through 2020–2025, the market keeps expanding under a mid‑single‑digit CAGR. That growth is driven by the intersection of data‑center expansion, medical device innovation (including single‑use disposables), and industrial automation upgrades that favor quick‑connect, ruggedized circular interfaces.
-
Demand shock vectors: Global AI infrastructure investments topped half a trillion dollars in 2025, and power demand for data centers is projected to rise materially by 2030—both creating copper‑intensive, high‑reliability connector demand. Simultaneously, policy moves accelerating data‑center permitting and grid interconnection transparency materially shorten project lead times and raise near‑term volumes in specific procurement pipelines.
-
Input cost pressure: Precious‑metal price spikes in early 2026 (notably for gold and silver) and volatility in other conductor materials are compressing margins and forcing design trade‑offs. Manufacturers that deploy material substitution strategies, strategic hedges, or design optimization will preserve margins; others will be forced into reactive price increases.
-
Market structure: The competitive landscape remains relatively unconcentrated—no dominant oligopoly—creating opportunities for focused players to scale by specialization, channel partnerships, or bolt‑on M&A. This fragmentation favors nimble entrants that can pair product differentiation with manufacturing agility.
Competitive landscape — themes and recent moves
Our benchmarking of incumbent and emergent suppliers highlights three strategic playbooks in market competition: premium performance specialization, ruggedized/high‑volume industrial scale, and low‑cost/customized manufacturing. Representative firms and directional moves observed through primary research include:
-
High‑performance specialists: LEMO (Switzerland) and Fischer Connectors (Switzerland) continue to push into medical and extreme‑environment data/power segments with product innovations focused on ergonomics, sterilization compatibility, and high‑speed data ratchet locking. Recent 2026 launches (e.g., LEMO’s disposable REDEL Series and Fischer’s ratcheted USB‑C UltiMate) show deliberate moves into higher‑value medical and high‑speed data niches.
-
Robust industrial leaders: ODU (Germany), HARTING (Germany), Amphenol (US), and Rosenberger (Germany) are iterating on high‑current, IP‑rated, and quick‑connect solutions tailored to robotics, factory automation, and transport systems. ODU’s 2026 high‑current safety modules and HARTING’s push‑pull D‑Sub adaptations illustrate how incumbents defend share by deepening system integration.
-
Volume and specialized OEM partners: A broad cohort of suppliers—including NEUTRIK, Binder, JAE Electronics, Hirose, TE Connectivity, and regional manufacturers in Asia—serve specific OEM ecosystems (audio/video, instrumentation, telecom, medical). Chinese and European custom suppliers are increasingly competitive on certification and rapid customization.
-
Emerging dynamics: Product innovation is converging on three technical vectors—higher current density, sealed ratchet/push‑pull interfaces for faster serviceability, and multi‑fiber/multi‑signal variants for smart infrastructure. The companies that marry these capabilities with validated supply chains and low product qualification time will capture the largest near‑term share gains.
What the full report contains (practical modules)
We designed the deliverables to support board‑level strategy down to procurement playbooks and engineering acceptance criteria. Key actionable modules include:
-
Market model and forecasts (2020–2032) with scenario sensitivity and demand drivers mapped to end‑market project pipelines.
-
Supplier benchmarking and capability matrix—engineering performance, production footprint, certifications, and time‑to‑qualify metrics.
-
Product and price benchmarking across form factors (metal, plastic, hybrid) and critical attributes (IP, current rating, data throughput).
-
Supply‑chain risk heatmaps: single‑source dependencies, raw‑material exposure, factory concentration, and mitigation levers.
-
Regulatory impact assessment with scenario implications for permitting and interconnection costs.
-
Commercial playbooks: bid‑strategy templates, contract clauses for commodity pass‑throughs, and distributor/channel optimization.
-
M&A and partnership shortlists with financial heuristics and integration checklists for bolt‑on manufacturing or IP acquisition.
-
Executive dashboards and a downloadable Excel model to test your own assumptions against our base case and two stress scenarios.
Recommended 2026 playbook (immediate to strategic)
-
Immediate (0–6 months): Conduct supplier stress tests for raw‑material exposure, implement short‑term hedges where appropriate, and fast‑track design reviews to reduce precious‑metal usage in non‑critical contacts. Negotiate conditional volume discounts tied to modularity and standardization.
-
Near‑term (6–18 months): Prioritize product launches for segments with accelerated demand windows—data center interconnects and disposable medical connectors—while creating dedicated supplier qualification lanes to shave months off time‑to‑market. Evaluate capacity options in lower‑cost geographies while preserving IP protection through split manufacturing and localized final assembly.
-
Strategic (18–36 months): Consider bolt‑on acquisitions to obtain high‑speed data or high‑current IP, or form JV manufacturing hubs near major data‑center corridors. Build multi‑tier supplier relations with explicit SLAs, and invest in predictive procurement systems that link material prices to contract triggers.
Key risks and monitoring triggers
-
Precious metal volatility: sustained high gold and silver prices will force design and procurement change—monitor price bands and supplier pass‑through clauses.
-
Regulatory acceleration: policy changes accelerating data‑center permitting and interconnection can create concentrated procurement spikes; keep a watch on federal and regional permitting updates.
-
Concentration risk: the market’s moderate fragmentation implies both opportunity and vulnerability—single‑source dependencies or capacity shortfalls among specialist suppliers are principal operational risks.
How PW Consulting helps you act
The full Circular Push‑Pull Connectors Market study is built for 2026 execution: it pairs a rigorously audited market model (2020–2032), validated supplier intelligence, and playbook templates so teams can immediately convert insight into RFPs, design changes, and M&A screening. We intentionally withhold segmented dashboards and supplier scorecards here to protect our subscribers’ competitive advantage—access to the complete dataset unlocks pricing curves, region‑and‑application breakdowns, and downloadable procurement and scenario models that are indispensable for transaction and sourcing decisions.
For teams that must prioritize limited bandwidth in 2026, the most value‑dense actions typically are: (1) lock conditional supply frameworks for mission‑critical product families; (2) accelerate product variants targeted at data‑center and single‑use medical applications; and (3) deploy supply‑risk monitoring tied to raw‑material indices. Our report provides the templates and validated data to execute each of these at scale.
Next step
If you are preparing capital allocation, procurement restructuring, or product‑roadmap decisions in 2026, the full PW Consulting market study provides the granular segmentation, supplier scorecards, and scenario models required to move from strategy to measurable outcomes. Visit our source page to access the full report, downloadable models, and the supplier shortlists that power tactical negotiations and M&A diligence.
For detailed analysis of this topic, please visit the official page: Circular Push Pull Connectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Submarine Optical Fiber Cable Market Poised for 12.6% CAGR to 2032
By pmarketresearch, 2026-07-13
Submarine Optical Fiber Cable Market: Strategic Imperatives for 2026 — Preview
As global bandwidth demand accelerates and geopolitical friction reframes critical infrastructure strategy, submarine optical fiber cables have moved from a niche telecom procurement to a central pillar of national and corporate resilience. This preview synthesizes the directional findings of PW Consulting’s full Submarine Optical Fiber Cable Market study (base year 2025), highlighting the strategic value our research delivers to executives planning capital allocation, supply-chain positioning, and competitive moves in 2026. The purpose here is to demonstrate analytical depth and practical orientation while preserving the granular segment intelligence and proprietary models that are available in the full report.
Submarine Optical Fiber Cable Market
Market trajectory you need to understand now
The market has been on a sustained expansion path through the 2020–2025 historical window and into the forecast horizon (2026–2032). Our topline analysis shows the market expanding at a robust compound annual growth rate of 12.6% across the forecast period, reflecting a confluence of capacity upgrades, new cross-border trunk builds, and an acceleration in regional interconnect projects driven by cloud and content-provider demand.
Submarine Optical Fiber Cable Market
To put this in practical terms for boardrooms and CFOs: the industry’s scale more than doubled over the historical period leading to 2025, and the projection to 2032 suggests continued, material addressable opportunity for network owners, system integrators, and equipment manufacturers. This macro momentum supports commitments to multi-year manufacturing investments, vessel time-charter agreements, and extended vendor partnerships — provided those commitments are stress-tested against supply-chain, regulatory, and cost volatility embedded in our scenario workstreams.
Submarine Optical Fiber Cable Market
Why this matters for 2026 decision cycles
- CapEx prioritization: With multi-year procurement lead times and production capacity constraints becoming the norm, procurement teams must anchor 2026 CapEx plans in probabilistic timelines. Our models translate market growth into expected demand windows for manufacturing slots, ship availability, and cable delivery schedules — enabling CFOs to avoid last-minute premium pricing and schedule slippage.
- Supplier selection and de‑risking: The market exhibits clear concentration dynamics among tier‑one suppliers. Tender strategies that previously emphasized lowest-L1 price now require multi-dimensional evaluation: manufacturing footprint, vessel access, proven high-count fiber systems, and security posture. Our vendor scorecards and weighting frameworks in the full report are designed to convert qualitative supplier claims into quantitative procurement outcomes.
- Network design and demand aggregation: Operators and hyperscalers can translate forecasted growth into an optimized mix of new builds versus capacity upgrades. We provide scenario-based ROI thresholds that identify when a greenfield subsea route is preferable to capacity augmentation — a decision that materially alters landing-party agreements, regulatory filings, and financing structures.
- Regulatory and geopolitical readiness: Recent regulatory action in key jurisdictions has introduced both facilitation measures and supply‑chain controls. Our regulatory risk matrix helps legal and government-affairs teams prioritize engagement and compliance steps that materially impact project timelines and choice of partners.
Competitive landscape — practical takeaways
The supply ecosystem is anchored by a mix of established global contractors and emerging regional players. Key firms addressed by our analysis include manufacturers and system integrators such as SubCom, Alcatel Submarine Networks, HMN Technologies, NEC Corporation, Prysmian Group, and Nexans. Each brings differentiated strengths that translate into contrasting strategic options for buyers and investors:
- SubCom — Operates a vertically integrated production model with specialized cable-laying vessels and a large manufacturing campus. Recent expansions underscore their intent to scale production capacity and shorten lead times for large-system builds, which can be a decisive advantage for projects with tight deployment windows.
- Alcatel Submarine Networks (ASN) — Brings a deep installed base and technological pedigree in long-haul, high-capacity systems. Their extensive global footprint makes them a strong partner where track record and operational continuity matter most for complex, multi-landing routes.
- HMN Technologies — Represents an example of an Asia‑anchored contractor winning regional projects and advancing competitive pricing and delivery timelines in emerging markets, evidenced by recent award activity.
- NEC Corporation — Focused on high-count fiber pair systems and route-specific engineering excellence, NEC is well-positioned where advanced system design and interoperability with terrestrial assets are prioritized.
- Prysmian Group and Nexans — As major cable manufacturers with broad product portfolios, they offer resilience in supply and opportunities for integrated terrestrial-subsea solutions, especially where consolidated supplier strategies reduce interface risk.
In short, procurement strategy in 2026 should be predicated on a nuanced view of vendor tradeoffs: fastest delivery versus optimized lifecycle cost versus national security and localization requirements. The full report’s vendor matrix converts those tradeoffs into procurement-ready ranking and negotiation anchors.
Cost structure and supply-chain dynamics
Two pragmatic cost realities shape every supplier selection and financial model:
- Raw material and engineering choices produce wide per‑kilometer cost dispersion — a single-day procurement mistake on armor specification or fiber count can multiply project cost and complicate future upgrades. Industry references indicate a material per-kilometer cost range driven by fiber-pair counts and armoring needs; these ranges should be modeled explicitly in investment appraisals.
- Localization of manufacturing — exemplified by recent factory investments targeted at supply sovereignty — can yield meaningful import and freight savings and reduce lead‑time risk. Scenario modeling in our study quantifies the P&L sensitivity to a 10–15% supply-cost swing from onshore production shifts, a change that is strategically actionable for operators focused on near-shore builds or national initiatives.
Regulatory and national-security considerations
Regulators are tightening the rulebook at both procedural and strategic levels. Recent measures aimed at streamlining permitting and increasing scrutiny over foreign technology sources change project risk profiles and the cadence of approvals. Legislative developments that impose export controls and supply‑chain constraints require cross-functional governance: procurement, legal, and security teams must align on vendor acceptance criteria and contingency plans. The full report includes a jurisdictional heatmap and a decision-tree tool to prioritize markets for investment based on regulatory friction and project-critical timelines.
Risks, mitigations, and scenario playbooks
Our approach brings a scenario-led engineering discipline to what is often an intuition-driven procurement process. The full study delivers three pragmatic playbooks:
- “Time-to-Service” playbook — for sponsors who must meet aggressive service-activation windows; emphasizes procurement of fast-ship materials, chartering strategy for cable vessels, and modular system designs.
- “Cost‑Optimization” playbook — for operators seeking lowest lifecycle cost; balances fiber-count choices, redundancy architectures, and phased implementation to defer capital without sacrificing service continuity.
- “Sovereignty & Security” playbook — for governments and national carriers; aligns supplier selection with local manufacturing targets, import substitution incentives, and compliance with evolving export-control regimes.
Each playbook includes time-bound milestones, negotiation checklists, and financing templates calibrated to the market growth trajectory and the operating realities of the key vendors covered in our competitive analysis.
What the full PW Consulting report contains (high‑value, operational modules)
The full report is designed as an implementable decision-support tool rather than a purely academic survey. Deliverables include:
- Proprietary demand model covering 2026–2032 with scenario variants tied to cloud‑capacity, content distribution, and national broadband initiatives.
- Vendor scorecards and procurement weighting matrices that convert technical and geopolitical criteria into selection ranks.
- Regulatory heatmaps and a timeline impact model for permitting and security clearances across major jurisdictions.
- Detailed cost-driver analysis and sensitivity tables (material, labor, vessel availability) to stress-test bid assumptions.
- Implementation playbooks (time-to-service, cost-optimization, sovereignty) with contracting templates, KPIs, and negotiation levers.
Note: This preview intentionally omits the detailed segmented financials, region/application breakdowns, and the vendor-level bidding benchmarks, which are core assets reserved for clients of the full report. Those elements are precisely the intelligence that converts market understanding into defensible procurement and investment decisions.
Immediate next steps for executives (practical checklist for 2026)
- Run a scenario workshop with finance and network engineering using a conservative and an aggressive demand case informed by the 12.6% market CAGR — align on go/no-go thresholds before issuing RFPs.
- Prioritize vendor dialogues that secure manufacturing slots and vessel commitments; treat “time-to-ship” as a primary commercial term alongside price.
- Engage government affairs and legal teams early to map regulatory paths and to pre-clear suppliers where export-control exposure exists.
- Model the P&L impact of localized manufacturing options and incorporate potential import‑cost reductions into total-cost-of-ownership (TCO) analyses.
Conclusion — why PW Consulting’s study matters in 2026
By 2026, the submarine optical fiber cable market is no longer just about capacity — it’s about timing, resilience, and geopolitical alignment. Our study transforms a fast-growing but complex market into an actionable roadmap that supports procurement rigor, capital discipline, and strategic risk mitigation. For decision-makers who must commit capital, sign long-term supplier contracts, or design national infrastructure programs in 2026, the full report provides the quantified scenarios, vendor playbooks, and negotiation tools required to convert market opportunity into sustainable advantage.
To access the full dataset, segmented financials, vendor-weighted procurement matrices, and the interactive scenario model, please visit our report page and request the complete Submarine Optical Fiber Cable Market study. The preview above outlines what to expect and why the contained intelligence is mission-critical for 2026 strategies — the deeper, executable analytics are available in the full deliverable.
For detailed analysis of this topic, please visit the official page: Submarine Optical Fiber Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial and Institutional Cleaning Market: Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
As PW Consulting’s flagship intelligence on Industrial & Institutional (I&I) Cleaning, this briefing synthesizes the macro trajectory, competitive dynamics, regulatory turning points, and practical playbooks that will shape capital allocation and commercial strategy in 2026. The market we model uses 2025 as the base year and projects through 2032: following steady growth from 2020, the industry is expected to expand at a compound annual growth rate (CAGR) of 4.72% through our forecast horizon. Total industry revenues grew from the low‑50s (USD Million) in 2020 to an estimated USD 63.4 Million in 2025 and are projected to approach the high‑80s (USD Million) by 2032. Those headline figures frame a market that is mature but adaptive — where raw material shocks, regulatory resets, and service‑led differentiation will reallocate value.
Industrial and Institutional Cleaning Market
Why this matters for 2026 planning
-
Timing: 2026 is not just another forecasting year. It is the inflection moment when post‑pandemic hygiene demand normalizes while structural pressures — notably raw material cost volatility and tightened chemical regulation — accelerate margin compression and compel reformulation or premiuming strategies.
Industrial and Institutional Cleaning Market -
Decision leverage: Procurement, R&D prioritization, and portfolio reshaping decisions taken in 2026 will determine supplier relationships and margin profiles for the next business cycle. Firms that preemptively redesign formulations, renegotiate supply terms, or shift toward service/recurring revenue models will capture asymmetric returns as the market rebalances.
Industrial and Institutional Cleaning Market -
Risk window: New regulatory measures and intensified scrutiny of persistent bioaccumulative toxins will drive short‑term compliance costs and medium‑term ingredient substitution. These risks are quantifiable and manageable — but only with scenario‑based planning and prioritized mitigation actions.
Market dynamics shaping 2026
-
Raw material and energy volatility: 2026 has seen pronounced price shocks across key input streams. Leading suppliers have implemented significant price increases in response to supply chain and energy disruptions. These moves compress formulators’ gross margins unless offset by pricing discipline, reformulation, or operational efficiencies.
-
Regulatory tightening: Authorities in major markets are progressing risk evaluations and enacting amendments that target several widely used industrial chemicals. The evolving regulatory environment elevates compliance costs and introduces phase‑out timelines for certain legacy solvents and specialty agents. Firms must prioritize chemical inventory audits, alternative‑ingredient testing, and regulatory scenario modeling.
-
Service and systems shift: End‑users increasingly value integrated solutions — automated dispensing, data‑enabled hygiene verification, and sustainability assurances. This is translating into demand for bundled hardware‑software‑chemical offerings and service contracts that improve retention and margin resilience.
-
Consolidation and concentration: The market shows a material degree of concentration among major global suppliers. Competitive advantage is shaped by scale in raw material procurement, formulation IP, and channel reach into institutional customers. For many buyers and smaller suppliers, this concentration raises supplier dependency and negotiating complexity.
-
Customer segmentation evolution: Buyers — from healthcare and foodservice to manufacturing and commercial property managers — are differentiating requirements around efficacy, traceability, and sustainability. This creates premiuming opportunities for validated high‑efficacy or low‑environmental‑impact formulations, while commoditization risks persist in basic surface care categories.
Competitive landscape — who moves markets
The competitive arena blends ingredient majors, specialty formulators, and hygiene system providers. The list of global players we profile includes multinational chemical suppliers and operational hygiene leaders. Each offers distinct strategic assets:
-
BASF SE (Ludwigshafen, Germany) — a full‑spectrum supplier of surfactants, enzymes and specialty additives, active across both raw material supply and formulation support. Recent unilateral price adjustments underscore the company’s leverage over upstream cost pass‑through dynamics.
-
Ecolab Inc. (St. Paul, Minnesota, USA) — a service‑led hygiene company combining chemical portfolios with dispensing systems and digital monitoring. Its strength is in cross‑industry penetration and contractually recurring revenues.
-
Diversey Holdings Ltd. (Charlotte, North Carolina, USA) — focused on sustainable, tech‑enabled cleaning solutions for healthcare, hospitality and food service, emphasizing lifecycle cost and compliance advantages.
-
The Clorox Company (Oakland, California, USA) — through its professional line, leverages brand recognition and scale in disinfectants and institutional wipes to serve managed facilities and healthcare segments.
-
Dow Inc., Clariant AG, Huntsman, Stepan, Solvay and others — these firms supply critical surfactants, solvents, polymers and additives that feed the formulation layer. Their strategic positioning centers on raw material innovation, stable supply, and sustainability roadmaps.
-
Kimberly‑Clark Corporation — differentiated by nonwoven and wipe products for institutional hygiene, combining material science with distribution strengths.
Together, this cohort controls a substantial proportion of professional‑grade supply and sets the market’s price and innovation agenda. Recent public moves — notably large price increases by a major provider to offset material and energy cost volatility — illustrate the speed at which upstream shocks can feed through to end markets.
Report contents — actionable intelligence (what’s inside)
Our full market study is built as a practitioner’s toolkit. Highlights include:
-
Top‑down and bottom‑up market sizing with transparent assumptions (base year 2025), and an integrated model projecting to 2032 using a 4.72% CAGR scenario plus high/low cases for sensitivity testing.
-
Supply chain stress testing: supplier concentration analysis, critical‑raw‑material mapping, and a supplier risk heatmap that identifies single‑source exposures and substitution pathways.
-
Regulatory impact matrix: scenario narratives and quantified P&L impacts for likely regulatory outcomes, including compliance timelines and cost pathways for ingredient substitution.
-
Price and margin playbooks: tactical options for cost recovery (contract terms, indexation, tiered pricing), product mix optimization, and route‑to‑market adjustments for 2026 shocks.
-
Technology and service monetization frameworks: go‑to‑market blueprints for transitioning from product sales to recurring revenue via dispensing systems, SaaS sanitation verification, and managed services.
-
M&A & partnership lens: target profiles, valuation heuristics for strategic and financial buyers, and integration checklists for technology or raw material acquisitions.
-
Customizable dashboards and Excel models for board presentations and investment committees that help quantify tradeoffs across price, volume, and margin scenarios.
Strategic imperatives for 2026
-
Lock in upstream protection: Negotiate multi‑year supply contracts with index mechanisms, qualify secondary suppliers, and accelerate testing of alternative chemistries to reduce exposure to single‑source price spikes.
-
Prioritize regulatory preparedness: Build a short list of likely ingredient phase‑outs, fund accelerated substitution R&D for the most at‑risk formulations, and establish regulatory monitoring to shorten reaction time.
-
Shift to service‑led models where feasible: Pilot automated dispensing and hygiene verification offerings with high‑value customers to transition a portion of revenue to recurring streams that are more resilient to raw material swings.
-
Recalibrate pricing architecture: Move from across‑the‑board hikes to differentiated pricing tied to formulation cost, efficacy claims, and service bundling to preserve volume in price‑sensitive accounts.
-
Invest in data and traceability: Deploy batch‑level traceability and performance analytics to support premium claims (sustainability, efficacy) and to defend pricing to institutional buyers.
-
Prepare M&A and partnership options: Identify bolt‑on targets that accelerate access to sustainable chemistries, digital dispensing, or regional distribution networks to shore up market position as competitors pursue consolidation.
How to use this briefing — practical next steps
-
Operational leaders: run a 90‑day supplier audit and a 180‑day reformulation pipeline for exposed SKUs; prioritize negotiations with top suppliers and model cash flow impact of various indexation formulas.
-
Commercial teams: segment customers by price elasticity and service appetite; pilot premium service bundles with a subset of accounts to test willingness to pay and churn impact.
-
R&D and sustainability leads: fast‑track testing of non‑restricted chemistries and allocate validation resources to high‑volume institutional applications that face imminent regulatory risk.
-
Finance and corporate development: use the report’s valuation heuristics and scenario outputs to assess opportunistic M&A or partnership plays that can be executed before competitors reposition.
Final note — why you should read the full report
This briefing outlines the strategic topography of the I&I cleaning market as you enter 2026, but intentionally omits granular regional and application‑level distributions that drive transactional decisions. The complete PW Consulting report delivers those subsegment matrices, supplier‑by‑sku exposure tables, and downloadable scenario models designed for direct use in procurement negotiation rooms and board decks. If your 2026 planning requires executable detail — not just directional intelligence — the full study contains the calibrated numbers and playbooks to act decisively.
For executives preparing budgets, negotiating with suppliers, or evaluating product and service pivots, the right combination of macro outlook, supplier intelligence, and operational playbooks is the difference between cost pass‑through and market share capture. PW Consulting’s full Industrial & Institutional Cleaning Market study provides that combination — ready to be deployed in Q1 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Industrial and Institutional Cleaning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IPDA market to hit USD 1,015.44 Million by 2032 at 3.2% CAGR
By pmarketresearch, 2026-07-13
Isophorone Diamine (IPDA) Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Chief Industry Analyst, I present a high-value strategic preview of our new Isophorone Diamine (IPDA) Market study — designed to inform the critical decisions you will make in 2026. This article surfaces the actionable implications and competitive dynamics you must factor into capital allocation, commercial strategy, and regulatory risk management. It intentionally demonstrates the analytical depth you can expect from the full report while preserving the proprietary, granular intelligence that drives competitive advantage.
Isophorone Diamine (IPDA) Market
Market snapshot: modest growth, meaningful inflection points
From a macro perspective the IPDA market displays steady but measured expansion. Our base-year analysis (2025) captures an industry that has grown from roughly USD 727 million in 2020 to about USD 838 million in 2025. Forward-looking projections for the 2026–2032 forecast horizon use a conservative compound annual growth rate (CAGR) of 3.2%, taking the market through cyclical swings before reaching just over USD 1.0 billion by the end of the forecast window. Notably, the near-term profile includes a visible uptick in 2026 followed by a modest correction in 2027, underscoring the sensitivity of IPDA demand to end-market cycles and feedstock dynamics.
Isophorone Diamine (IPDA) Market
Why this matters for 2026 decisions: a mid-single-digit CAGR signals a market where strategic moves — capacity timing, product differentiation, and supply-chain resilience — will determine winners and losers more than broad market growth alone. In other words, share gains can be achieved through operational excellence, smart commercial contracts, and regulatory foresight rather than relying on booming demand.
Isophorone Diamine (IPDA) Market
Supply structure and concentration — a decisive factor
IPDA is a concentrated market: our analysis shows the top three players collectively command an overwhelming share of global production capacity, with the top five accounting for an even higher proportion. High concentration creates distinct dynamics:
- Pricing discipline tends to be stronger, with periodic price stability punctuated by short-lived volatility when feedstock or regulatory shocks occur.
- Access to off-take and contractual security becomes a competitive lever — large buyers can negotiate favored supply terms, while smaller buyers face exposure.
- Strategic investments (e.g., new production trains, green-grade product launches) are more impactful because they materially alter available global capacity.
Key incumbent profiles that shape these dynamics include legacy chemical majors with integrated manufacturing sites, European specialty players commercializing renewable grades, large Asian commodity producers expanding throughput, and nimble US distributors supplying premium aliphatic diamines to technical end-markets. Each archetype brings different strategic implications for suppliers and buyers alike.
Competitive positioning — what the core players signal
- BASF SE (Ludwigshafen) — Operates IPDA production within a deep, integrated Verbund complex that supports reliable supply and strong technical service for epoxy curing systems. Their position favors customers prioritizing security and technical partnership.
- Evonik Industries AG (Germany; global footprint) — Recent launches of isophorone-based renewable grades illustrate a strategic pivot toward sustainability-driven differentiation. Their dual focus on specialty positioning and broader geographic footprint enables premium pricing in select segments.
- Wanhua Chemical (China) — Aggressively expanding capacity with public filings indicating large-scale projects and environmental assessments. The company is positioning to be a global scale player, which will pressure global trade flows and merchant pricing.
- Achilles Chemical (US) — A supplier focused on premium, ISO9001-aligned IPDA for demanding technical applications. Their strength lies in service, quality assurance, and niche channel reach.
Two recent developments crystallize near-term strategic implications: an Asian producer publicly advancing a major capacity expansion (mid‑2025 environmental filings target substantial new throughput), and a European specialty player launching 100% renewable-acetone derived IPDA products earlier in 2025. These moves demonstrate parallel pressures — scale-driven cost competition and sustainability-driven product differentiation — that will define competitive battlegrounds through 2026 and beyond.
Input and regulatory risks that will shape strategy in 2026
A nuanced understanding of raw material and regulatory risk is central to any credible 2026 playbook.
- Feedstock volatility: Feedstock and upstream raw material costs have shown high annual variability, with swings materially impacting production economics. This volatility amplifies margin risk in merchant markets and can render project economics fragile unless hedged or vertically integrated.
- Regional pricing influence: China’s position as a major producer and exporter means its feedstock and production cost profile exerts outsized influence on global merchant prices. Capacity changes in China therefore ripple quickly through global trade and pricing.
- Regulatory tightening: New emission and chemical manufacturing compliance rules in markets such as the EU have increased operating costs (our analysis points to compliance-related cost uplifts in the low double digits) and constrained operational flexibility. Similar trends in parts of Asia are prompting suppliers to rethink regional footprints and sourcing strategies.
Implication for 2026: risk management must be proactive and multi-dimensional — from feedstock contracting strategies and geographic sourcing to investment in lower-emission process technologies and supply diversification.
Commercial and operational playbook for 2026
Based on the market structure, competitive moves, and risk environment, executive teams should prioritize a tightly sequenced set of actions in 2026:
- Secure supply with hybrid contracting: Combine long-term offtake agreements for critical volumes with formula-linked short-term purchases to balance price certainty and flexibility.
- De-risk feedstock exposure: Implement hedging programs, strategic tolling agreements, or co-sourcing arrangements with feedstock suppliers. Consider backward-integration where scale economics and logistics permit.
- Differentiate with greener grades: Accelerate qualification of renewable or lower-emission IPDA grades for high-value accounts — customers in coatings, composites, and high-performance adhesives are increasingly willing to pay for verified lifecycle improvements.
- Benchmark capacity economics rigorously: In a market growing at a modest CAGR, new greenfield investments must clear conservative IRR hurdles. Brownfield debottlenecking and strategic partnerships often deliver superior risk-adjusted returns.
- Monitor geopolitical trade flows: Watch export policies and EHS permitting in China and Europe; short windows of disrupted trade can shift merchant balances quickly.
- M&A and JV discipline: Opportunistic consolidation can create scale advantages, but buyers must value synergies in logistics, regulatory footprint, and customer access — not just headline capacity.
What the full PW Consulting IPDA study delivers (and why it matters)
The full study maps the market mechanics that executives need to operationalize the playbook above. It includes:
- Supply‑demand modeling with sensitivity to feedstock price regimes and regulatory compliance costs;
- Scenario-based pricing forecasts and margin stress-tests across multiple regulatory and raw-material trajectories;
- Company-level positioning analysis with capabilities, plant footprints, and strategic intent;
- Playbooks for procurement, manufacturing optimization, green product commercialization, and M&A diligence; and
- Field-tested templates for contracts, indexation mechanisms, and a prioritized checklist for capital projects.
We deliberately withhold granular segmentation tables and plant-by-plant capacity schedules in this preview — those are the proprietary insights that materially inform negotiation strategy and capital deployment and are available through the full report and our bespoke advisory engagements.
Top 5 strategic recommendations for 2026
- Prioritize supply security: Negotiate multi-year offtakes with staggered renewal windows to avoid single-point exposure to merchant price swings.
- Invest in product differentiation: Fast-track renewable IPDA qualification for key customers in coatings and composites to capture premium buckets.
- Adopt flexible sourcing: Build optionality with dual‑region sourcing and tolling arrangements to navigate regional regulatory constraints.
- Defer large greenfield bets: Until feedstock volatility moderates and regulatory regimes stabilize, favor brownfield capacity and partnerships over greenfield commitments.
- Embed regulatory surveillance: Create an internal EHS and policy radar to anticipate and monetize regulatory disadvantage and advantage.
Final note — why 2026 is decisive
The IPDA market in 2026 is not characterized by runaway demand but by significant strategic inflection — the convergence of supplier consolidation, capacity moves from large Asian producers, and a premium being placed on sustainable product credentials. For executives, the question is not whether the market will grow — it will, at a modest pace — but who captures value within that growth. The decisions you take in 2026 about contracting, capacity, and sustainability will determine your position through the next economic cycle.
For the granular intelligence, scenario outputs, and transaction-grade models that translate these strategic imperatives into executable moves, access the full PW Consulting IPDA Market report or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Isophorone Diamine (IPDA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Duty-Free Retail Market to Reach USD 83.91B by 2032 at 6.2% CAGR
By pmarketresearch, 2026-07-13
Duty Free Retailing Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As global travel re-normalizes and retail models continue to converge with travel experiences, duty free retailing stands at an inflection point. Our latest PW Consulting market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — quantifies a clear recovery and structural growth path. The global duty free market has expanded from the post‑pandemic trough and reached an estimated USD 55.0 billion in 2025, with a projected compound annual growth rate (CAGR) of 6.2% through 2032. By the end of the forecast window, the market is expected to approach the high‑$80s billion range, reflecting resilient demand, retail innovation and strategic airport partnerships.
Duty Free Retailing Market
Why this study matters for 2026 strategy
-
Timing is strategic. The market’s mid‑single‑digit CAGR translates into substantial incremental revenues over a seven‑year horizon — enough to justify capital investments in store formats, digital infrastructure and concession long‑term contracts if deployed with precision.
Duty Free Retailing Market -
Market concentration matters. The sector demonstrates moderate to high concentration at the top, with the largest players commanding a significant share of revenues. This creates differentiated competitive dynamics that influence pricing power, supplier negotiations and route‑to‑market strategies.
Duty Free Retailing Market -
Operational windows are closing. Airports and concessionaires are finalizing multi‑year deals and concept rollouts through 2026–2028; late entrants face higher entry costs and more complex renegotiation dynamics. Our analysis identifies where to place bets in timing, partner selection and asset allocation.
-
Regulation and partnership dynamics are active. Recent regulatory and concession actions in major hubs have shifted opportunity maps. Five practical use cases in the report explain how to convert these shifts into measurable revenue uplifts.
Headline market trajectory and what it implies
The aggregate market trajectory is a north‑east curve: from a recovery phase in the early 2020s into a sustainable growth regime through the late 2020s and early 2030s. Growth drivers are threefold: (1) renewed international travel volumes and increased per‑passenger spend, (2) product mix optimization led by premium categories and experiential retail, and (3) distribution evolution — from larger format, core‑category shops to gate‑side and lounge‑centric micro retailing.
For strategy teams, this means (a) a renewed focus on per‑capita conversion and basket size engineering, (b) investments in curated brand partnerships that deliver both margin uplift and traffic capture, and (c) rigorous scenario planning for airport dependency and channel diversification. With the market expected to expand materially from 2025 levels under a 6.2% CAGR, the opportunity cost of delayed strategic moves is real: those who act in 2026 can lock in concession terms, co‑develop new retail concepts and secure preferred vendor arrangements that compound returns across the forecast period.
Core strategic levers for 2026
-
Concession design and portfolio optimization: Reassess concession footprints by passenger flow, dwell time, and demographic mix. We show a repeatable decision logic for when to deploy full‑format stores versus pop‑ups and gate‑side concepts.
-
Experience‑led merchandising: Allocate shelf and display economics toward premium and experiential assortments. Our playbook quantifies how small SKU shifts and service enhancements alter average transaction values.
-
Digital augmentation: Implement a phased digital layer — from inventory visibility and click‑and‑collect to pre‑flight personalization and loyalty tie‑ins with airlines. The study includes pragmatic tech investment prioritization based on payback and operational complexity.
-
Partnership and concession strategy: Design concession bids around co‑investment and revenue‑share permutations. We identify which commercial terms produce superior risk‑adjusted returns in high/low passenger scenarios.
-
Supply chain and vendor management: Consolidate strategic suppliers for high‑velocity categories and implement dynamic pricing frameworks to capture FX and duty arbitrage without eroding brand relationships.
Practical, decision‑ready deliverables inside the report
We structured the study to be usable on day one by CEOs, commercial directors, airport retail teams and private equity investors. Highlights include:
-
Actionable market sizing and valuation templates — calibrated to 2025 base year inputs and stress‑tested across multiple travel recovery scenarios.
-
Operational playbooks — 12 tactical initiatives with implementation milestones and expected ROI windows tailored to concessionaires and airport retail operators.
-
Go‑to‑market blueprints — step‑by‑step for launching gate‑side concepts, curated luxury pop‑ups and F&B integrated concessions.
-
Commercial negotiation decks — model term sheets, plausible revenue share permutations and a checklist of non‑financial concession KPIs that vendors typically overlook.
-
Digital transformation roadmap — prioritized features, vendor selection criteria and an estimated capex/opex envelope for phased rollouts.
-
Scenario modelling suite — downloadable worksheets that let you stress test demand and margin sensitivity at the store and portfolio level.
Importantly, while this briefing outlines the macro direction and strategic levers, the report reserves detailed regional and category splits, granular unit economics and full financial models for the full published study — a deliberate choice to ensure the report acts as a strategic “preview” and an operational catalyst.
Competitive landscape — who matters and why
The duty free arena is shaped by a set of well‑capitalized operators with differentiated propositions: integrated concession operators, national champions, airport specialists and regionally focused groups. Market concentration is noteworthy — the top three and top five operators together hold a substantial portion of industry revenues — which tightens access to premium airport slots and influences supplier dynamics.
-
Avolta AG (Switzerland): Avolta continues to expand via long‑term concession wins and integrated service models that blend luxury retail with F&B. Recent multi‑year contracts and store openings in key intercontinental hubs underscore its strategy of anchoring premium passenger flows with experiential formats.
-
DFS Group Limited (China) and China Duty Free Group : Both remain influential in shaping premium luxury exposure, particularly for brands that view travel retail as a channel for high‑frequency, high‑spend international shoppers. Their network scale provides negotiating leverage with top global brands.
-
Gebr. Heinemann and Lagardère Travel Retail (Germany and France): These European incumbents pair strong airport relationships with aggressive concept innovation. Lagardère’s recent concept launches and multi‑year concession awards reflect a playbook focused on localized experiences and partnership with airport authorities.
-
Lotte , Shilla , King Power , Dubai Duty Free and other regional leaders: These operators combine domestic retail strength with tourism channel access to capture inbound high‑value travelers. They are primary competitors for gateway concessions and brand showcases.
-
Airports and new operator partnerships : Recent partnerships — for example, new operator arrangements and concession redesigns at major hubs — reveal a trend: airports are becoming active co‑creators of retail experiences, selecting partners who can deliver traffic conversion, architectural fit and differentiated tenant mixes.
Recent industry moves to watch (signal vs. noise)
-
Major concession wins and long‑term contracts have been concentrated in 2025–2026, with operators securing 10+ year arrangements and investing in store reimagination. These deals raise the bar for entrants and restructure competitive advantage around airport relationships.
-
Localized concept launches — including gate‑side and lounge‑centric stores — demonstrate a shift from purely destination shopping toward convenience and impulse capture. Early pilots indicate higher conversion in curated micro‑formats when combined with strong digital pre‑engagement.
-
Strategic airport‑operator partnerships (redesign projects and curated curation strategies) point to a future where airports co‑invest in retail experiences as part of passenger experience KPIs, not just as rent generators.
-
Regulatory and policy reporting (regional economic impact studies and local campaign initiatives) are increasingly influential in shaping concession award criteria and community‑centric KPIs that operators must meet.
How to use this briefing in your 2026 planning cycle
-
Board and investor briefings: Use the headline market trajectory and concentration metrics to re‑calibrate portfolio allocation and to frame capital asks.
-
Commercial strategy workshops: Deploy our concession negotiation decks and store concept blueprints to accelerate bid timelines and reduce execution risk.
-
Operational pilots: Select two to three initiatives (e.g., gate‑side micro‑format, digital pre‑order, premium concierge services) for rapid prototyping with clear success metrics and 6–12 month go/no‑go criteria.
-
M&A and partnership screening: Apply our target assessment templates to prioritize bolt‑on acquisitions that fill capability gaps (digital, F&B, brand curation) rather than merely adding square meters.
Next steps
This briefing provides the directional logic and high‑level evidence to influence executive choices in 2026. For teams preparing concession bids, optimizing store portfolios, or evaluating investment in travel‑retail platforms, the full PW Consulting Duty Free Retailing Market Report contains the granular segment economics, regional and category splits, downloadable scenario models and implementation tools required to move from strategy to execution. Access to those detailed data sets and templates is available through the full report.
PW Consulting stands ready to support scenario planning, concession bid preparation, and post‑acquisition integration for clients seeking to convert the sector’s growth trajectory into sustained commercial performance. Contact our travel retail practice to book a tailored briefing and workshop based on the full study.
For detailed analysis of this topic, please visit the official page: Duty Free Retailing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com