

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Submarine Optical Fiber Cable Market Poised for 12.6% CAGR to 2032

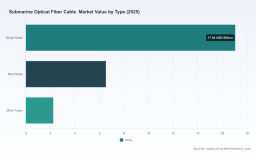
Submarine Optical Fiber Cable Market: Strategic Imperatives for 2026 — Preview
As global bandwidth demand accelerates and geopolitical friction reframes critical infrastructure strategy, submarine optical fiber cables have moved from a niche telecom procurement to a central pillar of national and corporate resilience. This preview synthesizes the directional findings of PW Consulting’s full Submarine Optical Fiber Cable Market study (base year 2025), highlighting the strategic value our research delivers to executives planning capital allocation, supply-chain positioning, and competitive moves in 2026. The purpose here is to demonstrate analytical depth and practical orientation while preserving the granular segment intelligence and proprietary models that are available in the full report.
Submarine Optical Fiber Cable Market
Market trajectory you need to understand now
The market has been on a sustained expansion path through the 2020–2025 historical window and into the forecast horizon (2026–2032). Our topline analysis shows the market expanding at a robust compound annual growth rate of 12.6% across the forecast period, reflecting a confluence of capacity upgrades, new cross-border trunk builds, and an acceleration in regional interconnect projects driven by cloud and content-provider demand.
Submarine Optical Fiber Cable Market
To put this in practical terms for boardrooms and CFOs: the industry’s scale more than doubled over the historical period leading to 2025, and the projection to 2032 suggests continued, material addressable opportunity for network owners, system integrators, and equipment manufacturers. This macro momentum supports commitments to multi-year manufacturing investments, vessel time-charter agreements, and extended vendor partnerships — provided those commitments are stress-tested against supply-chain, regulatory, and cost volatility embedded in our scenario workstreams.
Submarine Optical Fiber Cable Market
Why this matters for 2026 decision cycles
- CapEx prioritization: With multi-year procurement lead times and production capacity constraints becoming the norm, procurement teams must anchor 2026 CapEx plans in probabilistic timelines. Our models translate market growth into expected demand windows for manufacturing slots, ship availability, and cable delivery schedules — enabling CFOs to avoid last-minute premium pricing and schedule slippage.
- Supplier selection and de‑risking: The market exhibits clear concentration dynamics among tier‑one suppliers. Tender strategies that previously emphasized lowest-L1 price now require multi-dimensional evaluation: manufacturing footprint, vessel access, proven high-count fiber systems, and security posture. Our vendor scorecards and weighting frameworks in the full report are designed to convert qualitative supplier claims into quantitative procurement outcomes.
- Network design and demand aggregation: Operators and hyperscalers can translate forecasted growth into an optimized mix of new builds versus capacity upgrades. We provide scenario-based ROI thresholds that identify when a greenfield subsea route is preferable to capacity augmentation — a decision that materially alters landing-party agreements, regulatory filings, and financing structures.
- Regulatory and geopolitical readiness: Recent regulatory action in key jurisdictions has introduced both facilitation measures and supply‑chain controls. Our regulatory risk matrix helps legal and government-affairs teams prioritize engagement and compliance steps that materially impact project timelines and choice of partners.
Competitive landscape — practical takeaways
The supply ecosystem is anchored by a mix of established global contractors and emerging regional players. Key firms addressed by our analysis include manufacturers and system integrators such as SubCom, Alcatel Submarine Networks, HMN Technologies, NEC Corporation, Prysmian Group, and Nexans. Each brings differentiated strengths that translate into contrasting strategic options for buyers and investors:
- SubCom — Operates a vertically integrated production model with specialized cable-laying vessels and a large manufacturing campus. Recent expansions underscore their intent to scale production capacity and shorten lead times for large-system builds, which can be a decisive advantage for projects with tight deployment windows.
- Alcatel Submarine Networks (ASN) — Brings a deep installed base and technological pedigree in long-haul, high-capacity systems. Their extensive global footprint makes them a strong partner where track record and operational continuity matter most for complex, multi-landing routes.
- HMN Technologies — Represents an example of an Asia‑anchored contractor winning regional projects and advancing competitive pricing and delivery timelines in emerging markets, evidenced by recent award activity.
- NEC Corporation — Focused on high-count fiber pair systems and route-specific engineering excellence, NEC is well-positioned where advanced system design and interoperability with terrestrial assets are prioritized.
- Prysmian Group and Nexans — As major cable manufacturers with broad product portfolios, they offer resilience in supply and opportunities for integrated terrestrial-subsea solutions, especially where consolidated supplier strategies reduce interface risk.
In short, procurement strategy in 2026 should be predicated on a nuanced view of vendor tradeoffs: fastest delivery versus optimized lifecycle cost versus national security and localization requirements. The full report’s vendor matrix converts those tradeoffs into procurement-ready ranking and negotiation anchors.
Cost structure and supply-chain dynamics
Two pragmatic cost realities shape every supplier selection and financial model:
- Raw material and engineering choices produce wide per‑kilometer cost dispersion — a single-day procurement mistake on armor specification or fiber count can multiply project cost and complicate future upgrades. Industry references indicate a material per-kilometer cost range driven by fiber-pair counts and armoring needs; these ranges should be modeled explicitly in investment appraisals.
- Localization of manufacturing — exemplified by recent factory investments targeted at supply sovereignty — can yield meaningful import and freight savings and reduce lead‑time risk. Scenario modeling in our study quantifies the P&L sensitivity to a 10–15% supply-cost swing from onshore production shifts, a change that is strategically actionable for operators focused on near-shore builds or national initiatives.
Regulatory and national-security considerations
Regulators are tightening the rulebook at both procedural and strategic levels. Recent measures aimed at streamlining permitting and increasing scrutiny over foreign technology sources change project risk profiles and the cadence of approvals. Legislative developments that impose export controls and supply‑chain constraints require cross-functional governance: procurement, legal, and security teams must align on vendor acceptance criteria and contingency plans. The full report includes a jurisdictional heatmap and a decision-tree tool to prioritize markets for investment based on regulatory friction and project-critical timelines.
Risks, mitigations, and scenario playbooks
Our approach brings a scenario-led engineering discipline to what is often an intuition-driven procurement process. The full study delivers three pragmatic playbooks:
- “Time-to-Service” playbook — for sponsors who must meet aggressive service-activation windows; emphasizes procurement of fast-ship materials, chartering strategy for cable vessels, and modular system designs.
- “Cost‑Optimization” playbook — for operators seeking lowest lifecycle cost; balances fiber-count choices, redundancy architectures, and phased implementation to defer capital without sacrificing service continuity.
- “Sovereignty & Security” playbook — for governments and national carriers; aligns supplier selection with local manufacturing targets, import substitution incentives, and compliance with evolving export-control regimes.
Each playbook includes time-bound milestones, negotiation checklists, and financing templates calibrated to the market growth trajectory and the operating realities of the key vendors covered in our competitive analysis.
What the full PW Consulting report contains (high‑value, operational modules)
The full report is designed as an implementable decision-support tool rather than a purely academic survey. Deliverables include:
- Proprietary demand model covering 2026–2032 with scenario variants tied to cloud‑capacity, content distribution, and national broadband initiatives.
- Vendor scorecards and procurement weighting matrices that convert technical and geopolitical criteria into selection ranks.
- Regulatory heatmaps and a timeline impact model for permitting and security clearances across major jurisdictions.
- Detailed cost-driver analysis and sensitivity tables (material, labor, vessel availability) to stress-test bid assumptions.
- Implementation playbooks (time-to-service, cost-optimization, sovereignty) with contracting templates, KPIs, and negotiation levers.
Note: This preview intentionally omits the detailed segmented financials, region/application breakdowns, and the vendor-level bidding benchmarks, which are core assets reserved for clients of the full report. Those elements are precisely the intelligence that converts market understanding into defensible procurement and investment decisions.
Immediate next steps for executives (practical checklist for 2026)
- Run a scenario workshop with finance and network engineering using a conservative and an aggressive demand case informed by the 12.6% market CAGR — align on go/no-go thresholds before issuing RFPs.
- Prioritize vendor dialogues that secure manufacturing slots and vessel commitments; treat “time-to-ship” as a primary commercial term alongside price.
- Engage government affairs and legal teams early to map regulatory paths and to pre-clear suppliers where export-control exposure exists.
- Model the P&L impact of localized manufacturing options and incorporate potential import‑cost reductions into total-cost-of-ownership (TCO) analyses.
Conclusion — why PW Consulting’s study matters in 2026
By 2026, the submarine optical fiber cable market is no longer just about capacity — it’s about timing, resilience, and geopolitical alignment. Our study transforms a fast-growing but complex market into an actionable roadmap that supports procurement rigor, capital discipline, and strategic risk mitigation. For decision-makers who must commit capital, sign long-term supplier contracts, or design national infrastructure programs in 2026, the full report provides the quantified scenarios, vendor playbooks, and negotiation tools required to convert market opportunity into sustainable advantage.
To access the full dataset, segmented financials, vendor-weighted procurement matrices, and the interactive scenario model, please visit our report page and request the complete Submarine Optical Fiber Cable Market study. The preview above outlines what to expect and why the contained intelligence is mission-critical for 2026 strategies — the deeper, executable analytics are available in the full deliverable.
For detailed analysis of this topic, please visit the official page: Submarine Optical Fiber Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com