

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Duty-Free Retail Market to Reach USD 83.91B by 2032 at 6.2% CAGR

Duty Free Retailing Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As global travel re-normalizes and retail models continue to converge with travel experiences, duty free retailing stands at an inflection point. Our latest PW Consulting market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — quantifies a clear recovery and structural growth path. The global duty free market has expanded from the post‑pandemic trough and reached an estimated USD 55.0 billion in 2025, with a projected compound annual growth rate (CAGR) of 6.2% through 2032. By the end of the forecast window, the market is expected to approach the high‑$80s billion range, reflecting resilient demand, retail innovation and strategic airport partnerships.
Duty Free Retailing Market
Why this study matters for 2026 strategy
-
Timing is strategic. The market’s mid‑single‑digit CAGR translates into substantial incremental revenues over a seven‑year horizon — enough to justify capital investments in store formats, digital infrastructure and concession long‑term contracts if deployed with precision.
Duty Free Retailing Market -
Market concentration matters. The sector demonstrates moderate to high concentration at the top, with the largest players commanding a significant share of revenues. This creates differentiated competitive dynamics that influence pricing power, supplier negotiations and route‑to‑market strategies.
Duty Free Retailing Market -
Operational windows are closing. Airports and concessionaires are finalizing multi‑year deals and concept rollouts through 2026–2028; late entrants face higher entry costs and more complex renegotiation dynamics. Our analysis identifies where to place bets in timing, partner selection and asset allocation.
-
Regulation and partnership dynamics are active. Recent regulatory and concession actions in major hubs have shifted opportunity maps. Five practical use cases in the report explain how to convert these shifts into measurable revenue uplifts.
Headline market trajectory and what it implies
The aggregate market trajectory is a north‑east curve: from a recovery phase in the early 2020s into a sustainable growth regime through the late 2020s and early 2030s. Growth drivers are threefold: (1) renewed international travel volumes and increased per‑passenger spend, (2) product mix optimization led by premium categories and experiential retail, and (3) distribution evolution — from larger format, core‑category shops to gate‑side and lounge‑centric micro retailing.
For strategy teams, this means (a) a renewed focus on per‑capita conversion and basket size engineering, (b) investments in curated brand partnerships that deliver both margin uplift and traffic capture, and (c) rigorous scenario planning for airport dependency and channel diversification. With the market expected to expand materially from 2025 levels under a 6.2% CAGR, the opportunity cost of delayed strategic moves is real: those who act in 2026 can lock in concession terms, co‑develop new retail concepts and secure preferred vendor arrangements that compound returns across the forecast period.
Core strategic levers for 2026
-
Concession design and portfolio optimization: Reassess concession footprints by passenger flow, dwell time, and demographic mix. We show a repeatable decision logic for when to deploy full‑format stores versus pop‑ups and gate‑side concepts.
-
Experience‑led merchandising: Allocate shelf and display economics toward premium and experiential assortments. Our playbook quantifies how small SKU shifts and service enhancements alter average transaction values.
-
Digital augmentation: Implement a phased digital layer — from inventory visibility and click‑and‑collect to pre‑flight personalization and loyalty tie‑ins with airlines. The study includes pragmatic tech investment prioritization based on payback and operational complexity.
-
Partnership and concession strategy: Design concession bids around co‑investment and revenue‑share permutations. We identify which commercial terms produce superior risk‑adjusted returns in high/low passenger scenarios.
-
Supply chain and vendor management: Consolidate strategic suppliers for high‑velocity categories and implement dynamic pricing frameworks to capture FX and duty arbitrage without eroding brand relationships.
Practical, decision‑ready deliverables inside the report
We structured the study to be usable on day one by CEOs, commercial directors, airport retail teams and private equity investors. Highlights include:
-
Actionable market sizing and valuation templates — calibrated to 2025 base year inputs and stress‑tested across multiple travel recovery scenarios.
-
Operational playbooks — 12 tactical initiatives with implementation milestones and expected ROI windows tailored to concessionaires and airport retail operators.
-
Go‑to‑market blueprints — step‑by‑step for launching gate‑side concepts, curated luxury pop‑ups and F&B integrated concessions.
-
Commercial negotiation decks — model term sheets, plausible revenue share permutations and a checklist of non‑financial concession KPIs that vendors typically overlook.
-
Digital transformation roadmap — prioritized features, vendor selection criteria and an estimated capex/opex envelope for phased rollouts.
-
Scenario modelling suite — downloadable worksheets that let you stress test demand and margin sensitivity at the store and portfolio level.
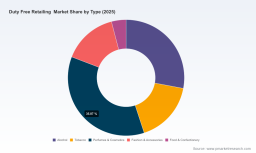
Importantly, while this briefing outlines the macro direction and strategic levers, the report reserves detailed regional and category splits, granular unit economics and full financial models for the full published study — a deliberate choice to ensure the report acts as a strategic “preview” and an operational catalyst.
Competitive landscape — who matters and why
The duty free arena is shaped by a set of well‑capitalized operators with differentiated propositions: integrated concession operators, national champions, airport specialists and regionally focused groups. Market concentration is noteworthy — the top three and top five operators together hold a substantial portion of industry revenues — which tightens access to premium airport slots and influences supplier dynamics.
-
Avolta AG (Switzerland): Avolta continues to expand via long‑term concession wins and integrated service models that blend luxury retail with F&B. Recent multi‑year contracts and store openings in key intercontinental hubs underscore its strategy of anchoring premium passenger flows with experiential formats.
-
DFS Group Limited (China) and China Duty Free Group : Both remain influential in shaping premium luxury exposure, particularly for brands that view travel retail as a channel for high‑frequency, high‑spend international shoppers. Their network scale provides negotiating leverage with top global brands.
-
Gebr. Heinemann and Lagardère Travel Retail (Germany and France): These European incumbents pair strong airport relationships with aggressive concept innovation. Lagardère’s recent concept launches and multi‑year concession awards reflect a playbook focused on localized experiences and partnership with airport authorities.
-
Lotte , Shilla , King Power , Dubai Duty Free and other regional leaders: These operators combine domestic retail strength with tourism channel access to capture inbound high‑value travelers. They are primary competitors for gateway concessions and brand showcases.
-
Airports and new operator partnerships : Recent partnerships — for example, new operator arrangements and concession redesigns at major hubs — reveal a trend: airports are becoming active co‑creators of retail experiences, selecting partners who can deliver traffic conversion, architectural fit and differentiated tenant mixes.
Recent industry moves to watch (signal vs. noise)
-
Major concession wins and long‑term contracts have been concentrated in 2025–2026, with operators securing 10+ year arrangements and investing in store reimagination. These deals raise the bar for entrants and restructure competitive advantage around airport relationships.
-
Localized concept launches — including gate‑side and lounge‑centric stores — demonstrate a shift from purely destination shopping toward convenience and impulse capture. Early pilots indicate higher conversion in curated micro‑formats when combined with strong digital pre‑engagement.
-
Strategic airport‑operator partnerships (redesign projects and curated curation strategies) point to a future where airports co‑invest in retail experiences as part of passenger experience KPIs, not just as rent generators.
-
Regulatory and policy reporting (regional economic impact studies and local campaign initiatives) are increasingly influential in shaping concession award criteria and community‑centric KPIs that operators must meet.
How to use this briefing in your 2026 planning cycle
-
Board and investor briefings: Use the headline market trajectory and concentration metrics to re‑calibrate portfolio allocation and to frame capital asks.
-
Commercial strategy workshops: Deploy our concession negotiation decks and store concept blueprints to accelerate bid timelines and reduce execution risk.
-
Operational pilots: Select two to three initiatives (e.g., gate‑side micro‑format, digital pre‑order, premium concierge services) for rapid prototyping with clear success metrics and 6–12 month go/no‑go criteria.
-
M&A and partnership screening: Apply our target assessment templates to prioritize bolt‑on acquisitions that fill capability gaps (digital, F&B, brand curation) rather than merely adding square meters.
Next steps
This briefing provides the directional logic and high‑level evidence to influence executive choices in 2026. For teams preparing concession bids, optimizing store portfolios, or evaluating investment in travel‑retail platforms, the full PW Consulting Duty Free Retailing Market Report contains the granular segment economics, regional and category splits, downloadable scenario models and implementation tools required to move from strategy to execution. Access to those detailed data sets and templates is available through the full report.
PW Consulting stands ready to support scenario planning, concession bid preparation, and post‑acquisition integration for clients seeking to convert the sector’s growth trajectory into sustained commercial performance. Contact our travel retail practice to book a tailored briefing and workshop based on the full study.
For detailed analysis of this topic, please visit the official page: Duty Free Retailing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com