

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Disposable Ostomy Bags Market to reach USD 306.8M by 2032 at 5.4% CAGR

Disposable Ostomy Bags Market — Strategic Insights for 2026 Decision‑Makers
The disposable ostomy bags market is entering the mid‑2020s with steady expansion, structural change and policy exposures that will determine winners and laggards through the next planning cycle. Our latest PW Consulting market study (base year 2025; historical window 2020–2025; forecast 2026–2032) shows the global market expanding from roughly USD 163 million in 2020 to USD 215 million in 2025, and projecting to reach approximately USD 307 million by 2032 at a compounded annual growth rate (CAGR) of 5.4%. This growth is meaningful for device manufacturers, suppliers, payers and health systems planning capital allocation, manufacturing footprints, or M&A for 2026 and beyond.
Disposable Ostomy Bags Market
Why this study matters for 2026 strategic planning
- Predictable expansion, evolving risk profile. The market’s mid‑single digit CAGR masks pockets of defensible revenue and persistent cost pressure — a dynamic that rewards disciplined margin management, regulatory readiness, and service differentiation.
- Concentration creates strategic leverage. The market is moderately concentrated: the top three players account for a clear majority of industry sales, and the top five widen that control further. That concentration shapes competitive behavior (pricing, channel access, clinical partnerships) and raises the bar for new entrants and niche players seeking scale.
- Policy and procurement are near‑term value levers. Recent regulatory and reimbursement developments (sterilization rules, bidding program inclusions and coverage clarifications) materially affect product cost structures and hospital procurement strategies in 2026 — making proactive payer engagement and tender playbooks essential.
- Operational resilience is now strategic. Single‑use disposables rely on medical‑grade materials and validated sterilization processes; supply chain fragility or compliance lapses translate quickly to commercial disruption.
Market dynamics and regulatory context — implications for operations and product strategy
- Sterilization compliance. New occupational exposure and engineering control expectations for ethylene oxide sterilization (EO) impose capital and O&M costs on sterilization-dependent suppliers. Firms must evaluate alternative sterilants, invest in EO engineering controls, or transfer sterilization to compliant third parties to maintain supply continuity and liability mitigation.
- Reimbursement and procurement shifts. Medicare policy clarifications and the inclusion of ostomy supplies within competitive bidding frameworks in 2026 alter purchasing behavior. Suppliers should anticipate tender price pressure, formulary negotiations and variability across local coverage determinations — requiring a coordinated reimbursement and contracting response.
- Regulatory product standards. Single‑use ostomy systems demand medical‑grade materials and quality systems (including ISO 13485 certification). Compliance is table stakes for market access and institutional procurement.
- Cost and material volatility. Raw material price swings, sterilization cost inflation and logistics constraints can erode margins. Firms that implement hedging, alternative material development and flexible manufacturing will protect profitability.
Competitive landscape — what the market structure means for strategic moves
The competitive field combines established global manufacturers with agile regional specialists. Major, globally recognized firms leverage broad brand portfolios, clinician relationships and integrated commercial channels; regional and niche players compete on service responsiveness, cost, or product specialization.
Disposable Ostomy Bags Market
- Global leaders. Established manufacturers with comprehensive one‑piece and two‑piece portfolios benefit from scale, established clinical trust and wide distribution networks. Their strategic advantages include deep clinical evidence libraries, global supply footprints and long‑standing reimbursements contracts.
- Regional challengers and specialists. Several UK-, European- and Asia‑based firms differentiate via targeted product ergonomics, regional reimbursement expertise and specialized accessory lines. These players are often more nimble in local tenders and clinician training programs.
- Private label and contract manufacturing. Growing pressure from procurement and tenders is elevating the role of private label and white‑label suppliers. Contract manufacturers that can offer regulatory certificates and sterilization pathways are increasingly attractive partners.
- Strategic implications. With the top three firms commanding a large share of the market and the top five extending that dominance, opportunities for consolidation, bolt‑on acquisitions, or exclusive distribution agreements are high‑value plays for firms seeking scale or market entry.
What PW Consulting’s report delivers (practical, decision‑grade content)
- Proprietary market model (2020–2032) with scenario modules calibrated to regulatory, reimbursement and supply chain stress tests.
- Demand drivers and adoption curve analysis — clinical drivers, patient demographics, and post‑surgical care pathway impacts.
- Regulatory and reimbursement playbook — practical checklists and a timeline of near‑term policy catalysts that will affect procurement and device design decisions in 2026.
- Supply chain and manufacturing risk map — sterilization pathway assessment, supplier concentration scoring, and cost‑to‑serve modelling.
- Competitive profiling and commercial benchmarking — strategic positioning, portfolio strengths, innovation vectors and go‑to‑market tactics for the leading and regional players.
- Actionable commercial strategies — tender playbooks, payer engagement templates, pricing elasticity analysis and product portfolio rationalisation frameworks.
- M&A and partnership shortlist methodology — target characteristics, valuation heuristics and integration risk checklists tailored to ostomy supply dynamics.
- Executive dashboards and KPIs — recommended metrics for board‑level monitoring and investor diligence in 2026.
Seven practical actions for executives to prioritize in 2026
- Confirm sterilization capacity and compliance paths. Conduct a rapid EO impact assessment, identify alternative sterilization partners or technologies, and quantify required capex or outsourcing costs. Prioritize assets that can be certified under new EO controls or shifted to compliant third parties.
- Rework reimbursement and tender playbooks. Model the financial impact of competitive bidding and local coverage variations; develop flexible pricing ladders and tender support packages (clinical training, bundled services) to protect margins.
- Segment‑led portfolio rationalisation (without guesswork). Use usage‑based profitability models to identify SKUs for premium positioning, cost optimisation or discontinuation — focusing R&D and marketing spend where clinical differentiation and payer willingness‑to‑pay align.
- Hedge supply risk. Establish multi‑sourcing for critical materials and negotiate longer‑term contracts with sterilization providers; consider regional contract manufacturing to shorten lead times for priority markets.
- Invest in clinician and patient support services. Differentiate beyond the pouch with digital adherence, product education and remote monitoring solutions that increase stickiness and justify premium pricing.
- Prepare M&A and partnership playbooks. Target regional leaders that offer distribution shortcuts or niche product portfolios; prioritize targets with clean regulatory pedigrees, ISO 13485 certification and validated sterilization pathways.
- Establish a regulatory horizon team. Track policy updates in sterilization, occupational safety and reimbursement; feed scenarios into quarterly commercial and CAPEX planning cycles.
Key metrics and watchlist for the next 12–18 months
- Global market growth vs. forecast (quarterly pace vs. the 5.4% CAGR baseline).
- Average selling price (ASP) movements and margin compression from tenders.
- Sterilization compliance spend and supplier capacity utilisation rates.
- Payer policy changes: competitive bidding outcomes, local coverage determinations and Medicare guidance updates.
- Supply chain red flags: single‑source materials, lead‑time spikes, and logistics costs.
- Clinical adoption indicators: hospital formulary insertions, clinical guideline updates and nurse/caregiver preference surveys.
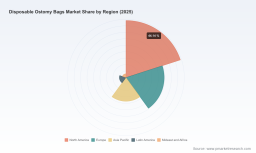
PW Consulting’s analysis is designed to be pragmatic and action‑ready. We surface the macro trajectory (from about USD 163 million in 2020 to ~USD 215 million in 2025 and a projected ~USD 307 million by 2032), the competitive realities, and the operational and regulatory fault lines that will determine 2026 outcomes — while deliberately reserving granular subsegment tables, regional splits and proprietary company market shares for the full report.
Disposable Ostomy Bags Market
For decision‑makers preparing budgets, M&A pipelines, or manufacturing roadmaps for 2026, the premium value is in the layered scenarios, procurement playbooks and compliance checklists that translate market trends into executable initiatives. Access the full PW Consulting Disposable Ostomy Bags Market report for the detailed datasets, scenario outputs and tailored templates that will enable confident, evidence‑based decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Disposable Ostomy Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com