

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
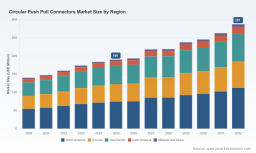
PW Consulting: Circular Push-Pull Connectors Market to Reach USD 287M by 2032 at 5.8% CAGR

Circular Push‑Pull Connectors Market: Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, this briefing distills the strategic imperatives from our full Circular Push‑Pull Connectors Market study (base year 2025, historical period 2020–2025, forecast 2026–2032). The market is expanding on a steady trajectory—with a compound annual growth rate (CAGR) of 5.8% into the forecast window—and the total addressable market is projected to move from roughly USD 190 million in 2025 toward an expected market sizing in the high‑two‑hundreds by 2032. Below we map the high‑value decisions that should be made in 2026 and explain how our full report equips executives to act with confidence.
Circular Push Pull Connectors Market
Why this research matters for 2026
-
Timing matters: 2026 is a pivot year. Macro infrastructure and regulatory moves are catalyzing demand in specific end markets (compute, medical disposables, industrial automation), while raw‑material shocks and localized supply risks are compressing supplier margins and creating tactical windows for procurement optimization.
Circular Push Pull Connectors Market -
Actionable orientation: The full PW Consulting study is designed to convert market intelligence into executable workstreams—supplier scorecards, pricing levers, integration checklists, and prioritized product roadmaps—so leaders can translate insight into measurable cost avoidance, revenue capture, and reduced time‑to‑market.
Circular Push Pull Connectors Market -
Teaser principle: this briefing demonstrates our analytical depth and directional findings while reserving core segment and company‑level scorecard data for subscribers—ensuring your team gains competitive advantage by accessing the full dataset and Excel models.
High‑level market dynamics you must internalize
-
Growth profile: After consistent expansion through 2020–2025, the market keeps expanding under a mid‑single‑digit CAGR. That growth is driven by the intersection of data‑center expansion, medical device innovation (including single‑use disposables), and industrial automation upgrades that favor quick‑connect, ruggedized circular interfaces.
-
Demand shock vectors: Global AI infrastructure investments topped half a trillion dollars in 2025, and power demand for data centers is projected to rise materially by 2030—both creating copper‑intensive, high‑reliability connector demand. Simultaneously, policy moves accelerating data‑center permitting and grid interconnection transparency materially shorten project lead times and raise near‑term volumes in specific procurement pipelines.
-
Input cost pressure: Precious‑metal price spikes in early 2026 (notably for gold and silver) and volatility in other conductor materials are compressing margins and forcing design trade‑offs. Manufacturers that deploy material substitution strategies, strategic hedges, or design optimization will preserve margins; others will be forced into reactive price increases.
-
Market structure: The competitive landscape remains relatively unconcentrated—no dominant oligopoly—creating opportunities for focused players to scale by specialization, channel partnerships, or bolt‑on M&A. This fragmentation favors nimble entrants that can pair product differentiation with manufacturing agility.
Competitive landscape — themes and recent moves
Our benchmarking of incumbent and emergent suppliers highlights three strategic playbooks in market competition: premium performance specialization, ruggedized/high‑volume industrial scale, and low‑cost/customized manufacturing. Representative firms and directional moves observed through primary research include:
-
High‑performance specialists: LEMO (Switzerland) and Fischer Connectors (Switzerland) continue to push into medical and extreme‑environment data/power segments with product innovations focused on ergonomics, sterilization compatibility, and high‑speed data ratchet locking. Recent 2026 launches (e.g., LEMO’s disposable REDEL Series and Fischer’s ratcheted USB‑C UltiMate) show deliberate moves into higher‑value medical and high‑speed data niches.
-
Robust industrial leaders: ODU (Germany), HARTING (Germany), Amphenol (US), and Rosenberger (Germany) are iterating on high‑current, IP‑rated, and quick‑connect solutions tailored to robotics, factory automation, and transport systems. ODU’s 2026 high‑current safety modules and HARTING’s push‑pull D‑Sub adaptations illustrate how incumbents defend share by deepening system integration.
-
Volume and specialized OEM partners: A broad cohort of suppliers—including NEUTRIK, Binder, JAE Electronics, Hirose, TE Connectivity, and regional manufacturers in Asia—serve specific OEM ecosystems (audio/video, instrumentation, telecom, medical). Chinese and European custom suppliers are increasingly competitive on certification and rapid customization.
-
Emerging dynamics: Product innovation is converging on three technical vectors—higher current density, sealed ratchet/push‑pull interfaces for faster serviceability, and multi‑fiber/multi‑signal variants for smart infrastructure. The companies that marry these capabilities with validated supply chains and low product qualification time will capture the largest near‑term share gains.
What the full report contains (practical modules)
We designed the deliverables to support board‑level strategy down to procurement playbooks and engineering acceptance criteria. Key actionable modules include:
-
Market model and forecasts (2020–2032) with scenario sensitivity and demand drivers mapped to end‑market project pipelines.
-
Supplier benchmarking and capability matrix—engineering performance, production footprint, certifications, and time‑to‑qualify metrics.
-
Product and price benchmarking across form factors (metal, plastic, hybrid) and critical attributes (IP, current rating, data throughput).
-
Supply‑chain risk heatmaps: single‑source dependencies, raw‑material exposure, factory concentration, and mitigation levers.
-
Regulatory impact assessment with scenario implications for permitting and interconnection costs.
-
Commercial playbooks: bid‑strategy templates, contract clauses for commodity pass‑throughs, and distributor/channel optimization.
-
M&A and partnership shortlists with financial heuristics and integration checklists for bolt‑on manufacturing or IP acquisition.
-
Executive dashboards and a downloadable Excel model to test your own assumptions against our base case and two stress scenarios.
Recommended 2026 playbook (immediate to strategic)
-
Immediate (0–6 months): Conduct supplier stress tests for raw‑material exposure, implement short‑term hedges where appropriate, and fast‑track design reviews to reduce precious‑metal usage in non‑critical contacts. Negotiate conditional volume discounts tied to modularity and standardization.
-
Near‑term (6–18 months): Prioritize product launches for segments with accelerated demand windows—data center interconnects and disposable medical connectors—while creating dedicated supplier qualification lanes to shave months off time‑to‑market. Evaluate capacity options in lower‑cost geographies while preserving IP protection through split manufacturing and localized final assembly.
-
Strategic (18–36 months): Consider bolt‑on acquisitions to obtain high‑speed data or high‑current IP, or form JV manufacturing hubs near major data‑center corridors. Build multi‑tier supplier relations with explicit SLAs, and invest in predictive procurement systems that link material prices to contract triggers.
Key risks and monitoring triggers
-
Precious metal volatility: sustained high gold and silver prices will force design and procurement change—monitor price bands and supplier pass‑through clauses.
-
Regulatory acceleration: policy changes accelerating data‑center permitting and interconnection can create concentrated procurement spikes; keep a watch on federal and regional permitting updates.
-
Concentration risk: the market’s moderate fragmentation implies both opportunity and vulnerability—single‑source dependencies or capacity shortfalls among specialist suppliers are principal operational risks.
How PW Consulting helps you act
The full Circular Push‑Pull Connectors Market study is built for 2026 execution: it pairs a rigorously audited market model (2020–2032), validated supplier intelligence, and playbook templates so teams can immediately convert insight into RFPs, design changes, and M&A screening. We intentionally withhold segmented dashboards and supplier scorecards here to protect our subscribers’ competitive advantage—access to the complete dataset unlocks pricing curves, region‑and‑application breakdowns, and downloadable procurement and scenario models that are indispensable for transaction and sourcing decisions.
For teams that must prioritize limited bandwidth in 2026, the most value‑dense actions typically are: (1) lock conditional supply frameworks for mission‑critical product families; (2) accelerate product variants targeted at data‑center and single‑use medical applications; and (3) deploy supply‑risk monitoring tied to raw‑material indices. Our report provides the templates and validated data to execute each of these at scale.
Next step
If you are preparing capital allocation, procurement restructuring, or product‑roadmap decisions in 2026, the full PW Consulting market study provides the granular segmentation, supplier scorecards, and scenario models required to move from strategy to measurable outcomes. Visit our source page to access the full report, downloadable models, and the supplier shortlists that power tactical negotiations and M&A diligence.
For detailed analysis of this topic, please visit the official page: Circular Push Pull Connectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com