

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Mobile Photo Printer Market Poised for 7.6% CAGR Through 2032
By pmarketresearch, 2026-07-13
Mobile Photo Printer Market — Strategic Outlook and Decision Playbook for 2026
As senior strategy advisor and lead industry analyst at PW Consulting, I present a concise yet substantive preview of our newest Mobile Photo Printer Market research — a practical briefing crafted to inform board-level choices and commercial plans in 2026. This is a “trailer” of the full study: we surface the analytical approach, the actionable implications and the competitive dynamics you must internalize now, while reserving the granular segment tables and proprietary model outputs for the full report.
Mobile Photo Printer Market
Market snapshot: a recovery story that requires calibrated strategy
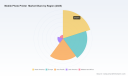
The market shows a distinct inflection as it moves out of the 2020–2025 period and into our 2026–2032 forecast window. After a period of volatility in the early 2020s, our base year for analysis is 2025. The market is projected to reaccelerate from 2026 onward at a compound annual growth rate (CAGR) of 7.6% over the 2026–2032 forecast period, reaching materially higher revenue by 2032. This trajectory reflects a compound of product refresh cycles, renewed consumer interest in printed keepsakes, and growth in event- and brand-driven use cases where physical prints enhance engagement.
Mobile Photo Printer Market
Two facts underpin this shape: (1) the near-term trough and subsequent rebound are driven less by a structural decline in demand for physical prints than by a combination of supply-side shocks (consumables and component cost pressure), regulatory adjustments around chemistry and recyclable materials, and a rebalancing of distribution channels; and (2) the long-term growth engine is a renewed monetization path that combines hardware upgrades with recurring consumables and digital value-added services.
Mobile Photo Printer Market
Why this report matters for 2026 decision-making
- Alignment of portfolio investments: the market’s post-2025 acceleration demands selective R&D and SKU rationalization — knowing where to invest (pocket vs. compact vs. novelty formats) is decisive for margin impact.
- Go-to-market timing: product introductions and channel campaigns in 2026 should anticipate a rising consumables cycle and leverage renewed retail traffic and experience-driven events.
- Supply chain and procurement playbook: rising paper roll and specialty component costs, coupled with geopolitical tariff pressure on assemblies, require renegotiated contracts and alternate-sourcing roadmaps now rather than later.
- Sustainability and regulatory compliance: shifting chemical rules and packaging mandates in major markets convert into both compliance costs and competitive differentiators; early movers capture brand premium.
- M&A and partnership screening: the market concentration metrics indicate a field dominated by a few large incumbents, creating openings for bolt-on acquisitions that complement software, consumables or niche form factors.
Competitive landscape — what the leading vendors signal
Market concentration is meaningful: the top three firms control a dominant share, and the top five extend that dominance substantially. This structure drives three practical realities for competitors and investors: (a) incumbents set pricing and channel norms, (b) scale matters for consumables distribution and service networks, and (c) differentiation increasingly comes from ecosystem plays (apps, consumables subscriptions, and event integrations) rather than hardware specs alone.
- Fujifilm Holdings (Japan) — Known for the instax mini Link line, Fujifilm continues to invest in app feature sets and product refinement. A January 2026 launch refreshed their smartphone printer experience, underscoring a strategy that pairs tactile retro appeal with modern connectivity and software features.
- Canon Inc. (Japan) — Canon’s SELPHY and IVY series represent the compact dye-sublimation strategy: performance-focused devices optimized for print fidelity and simple wireless workflows. Canon’s strengths lie in image-processing heritage and channel reach in both retail and professional segments.
- HP Inc. (United States) — The Sprocket pocket printers exemplify a volume, lifestyle-oriented play. HP leverages broad consumer brand recognition and global distribution to push lower-price, high-turnover units and consumables bundles.
- Kodak (United States) — Kodak’s STEP and Mini series straddle the thermal and dye-sublimation approaches. Kodak’s brand equity in instant imaging and licensing opportunities (nostalgia & co-branding) produces unique marketing plays even for smaller device players.
- Polaroid (United States) — Polaroid has doubled down on portable Bluetooth printers with a clear focus on brand-driven experiences and premium consumables, aiming to capture lifestyle-oriented buyers.
- Seiko Epson (Japan) — Epson’s portable lines emphasize reliable print mechanics and integration with professional imaging workflows; their supply chain scale and component know-how are differentiators for B2B and hybrid propositions.
- Phomemo (China) — As a price-competitive and fast-innovation manufacturer, Phomemo’s mini thermal printers and sticker formats illustrate how modular, low-cost manufacturing can capture niche and emerging markets rapidly.
Across incumbents and challengers, we observe a bifurcation: established imaging manufacturers pursue premium, service-linked experiences, while nimble entrants compete on cost, novelty formats and rapid channel experimentation.
Industry dynamics: regulatory, supply and materials risk
- Regulation & sustainability: Stricter regulations on photo-chemical composition and packaging in key markets are pushing suppliers toward water-based inks, recyclable substrates and reduced hazardous waste footprints. These are not only compliance issues; they shape procurement, partner selection and R&D priorities.
- Consumables pressure: Paper roll and specialty substrate costs have experienced upward pressure due to raw material availability and logistics. This amplifies the profitability importance of consumables subscriptions and vertical integration options.
- Standards & safety: ISO standards for electronics and batteries apply and will become gating factors for entry into certain retail and travel channels; design cycles should integrate certification timelines early.
- Geopolitical & tariff risk: Tariff actions on electronic assemblies in some import markets have material effects on landed costs. Manufacturers that diversify assembly footprints or localize critical components will be less exposed to periodic tariff shocks.
What PW Consulting’s full report delivers (action-oriented)
This study is built to be operationally actionable for executive teams. Highlights of deliverables include:
- Proprietary market model (2020–2032) with downloadable scenarios: baseline, accelerated-adoption and downside stress cases — allowing you to run custom inputs for pricing, channel shifts and consumables margins.
- Consolidated vendor benchmarking: capability scorecards across product, software, channel, service and sustainability for the leading suppliers, plus a shortlist of high-potential challengers and OEM/manufacturing partners.
- Commercial playbooks: three modular go-to-market templates (consumer-lifestyle, event-experience, and B2B/passport/identity niches) with sample P&L levers, channel commission frameworks and promotional calendars for 12–24 months.
- Supply chain and sourcing playbook: a supplier-risk heatmap, cost-driver decomposition for consumables, and tactical contract clauses to mitigate tariff and raw-material shocks.
- Product roadmap and feature prioritization matrix: a discrete decision framework to rank R&D investments in print fidelity, app features, battery life, and sustainable consumables based on ROI and competitive defensibility.
- M&A and partnership screening tool: a short-list of archetypal targets and a valuation framework for bolt-on acquisitions (software, consumables, last-mile distribution), plus integration risk checklists.
- Regulatory compliance tracker and sustainability roadmap: prioritized technical changes to meet near-term chemical and packaging regulations and a three-step plan to monetize sustainability claims.
We intentionally avoid listing the confidential segment-level revenue tables here. The full report contains the precise regional, type and application splits, together with elasticity coefficients and break-even analyses for new product SKUs — critical inputs for capital allocation and commercial rollout plans.
Practical strategic recommendations for 2026
- Prioritize consumables strategy: Negotiate multi-year supply agreements for paper and specialized substrates; pilot a subscription model in two pilot markets and run A/B tests on bundling tactics.
- Invest in rapid-certification and sustainable materials: Reallocate a portion of R&D spend to water-based inks and recyclable packaging to capture early-mover pricing and avoid future compliance costs.
- Differentiate through software and experiences: Bundle app features, AR overlays and event-integration APIs to drive higher attach rates for consumables and increase customer lifetime value.
- De-risk assembly and components: Establish alternative assembly partners outside tariff-exposed corridors and evaluate partial nearshoring for key subassemblies.
- Revisit pricing and channel economics: The rebound in demand requires dynamic pricing models — pilots should measure elasticity by channel and product tier to optimize mix for margin recovery.
- Scan for M&A that fills capability gaps: Targeted acquisitions that add software, subscription fulfillment capacity, or regional consumable distribution can deliver quick scale efficiencies in a concentrated market.
How to use this analysis
Board members and product leaders should use the findings to: (1) set realistic 2026 investment envelopes informed by scenario-driven demand curves, (2) align procurement and certification roadmaps with launch timetables, and (3) prioritize initiatives that create recurring revenue alongside hardware refresh cycles.
Commercial teams should deploy the playbooks and vendor scorecards to accelerate retail rollouts and test pricing bundles. Finance and corporate development teams will find the M&A screening and valuation frameworks immediately actionable for deal sourcing over the next 12 months.
Next steps — access the complete dataset and models
This introduction highlights the critical strategic lines you should act on in 2026. For executives who need to convert these themes into executable plans, the complete PW Consulting Mobile Photo Printer Market report provides the full datasets, segment-level forecasts, unit economics models and supplier scorecards referenced here. Visit our report page to download the full study, the interactive forecast model and the vendor benchmarking workbook — these contain the precise figures and operational templates that power confident investment and commercial choices.
At PW Consulting, we pair sector expertise with pragmatic tools — enabling you to turn a forecasted 7.6% CAGR and a clearly re-emerging market into a robust execution plan for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Mobile Photo Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gear Cutting Machines Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Gear Cutting Machines Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of the Gear Cutting Machines market designed to inform capital allocation, product strategy, and supply-chain choices through 2026 and beyond. This briefing highlights the macro trajectory, strategic inflection points, competitive dynamics, and the practical intelligence that our full study delivers — while preserving the granular segmentation and proprietary datasets that subscribers use for procurement, M&A, and plant‑level retrofit decisions.
Gear Cutting Machines Market
Market snapshot: a durable expansion anchored in modernization
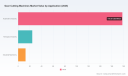
At the macro level, the Gear Cutting Machines market has shown steady expansion through the recent half‑decade and is entering a phase of accelerated modernization. Using 2025 as the analytical base year, the market grew from approximately USD 163 million in 2020 to roughly USD 215 million in 2025. Under the baseline forecasting scenario, the market is projected to continue on a compound annual growth rate of 6.98% across the 2026–2032 horizon, reaching roughly USD 345 million by 2032.
Gear Cutting Machines Market
Those headline numbers reflect two concurrent forces: a sustained replacement and capacity‑build cycle in mature metal‑forming industries, and a faster‑moving upgrade dynamic driven by energy‑efficiency imperatives, automation integration, and an expanding set of high‑precision applications (notably in electrified powertrains, aerospace, and advanced industrial equipment). For executives, the important implication is that capital deployed in 2026 will be evaluated against both near‑term productivity returns and multi‑year regulatory and energy savings that compound equipment ROI.
Gear Cutting Machines Market
Why this preview matters for 2026 decisions
- CapEx timing and sizing: With a market on a near‑7% CAGR, manufacturers face the classic trade‑off between early adoption to capture efficiency differentials and waiting for second‑generation smart tools. Our research frames the risk/reward curve for both greenfield capacity and targeted retrofit programs.
- Technology selection: Decisions between hobbing, shaping, shaving, skiving, and grinding workflows are no longer purely technical — they map to digitalization pathways, energy consumption profiles, and downstream finishing requirements. The report equips buyers with a decision matrix linking process choice to part complexity, tolerances, cycle time, and lifetime energy cost.
- Supply‑chain resilience: Long lead times for specialized spindles and high‑performance hobs, plus concentrated tooling inputs, mean procurement strategy drives delivery risk. Our analysis quantifies supplier concentration and proposes tactical sourcing options, including inventory buffers, second‑tier suppliers, and local service partnerships.
- Regulatory and cost pressure: Energy and building performance standards in key jurisdictions are shifting the operating model for precision machining shops — influencing not only the machine purchase decision but also layout, cooling systems, and waste‑heat recovery investments. The report models the impact of these regulations on TCO and payback periods.
Practical content included in the full study
The full PW Consulting study is constructed to be immediately usable by strategy teams, plant managers, and procurement officers. Highlights include:
- Executive dashboard with macro KPIs and scenario outputs for conservative, base, and aggressive adoption pathways;
- CapEx/TCO templates that model acquisition cost, energy consumption, tooling replacement, service contracts, and residual value over lifecycle horizons tailored to common use cases;
- Technology‑fit decision trees and process maps that translate product specifications and part tolerances into recommended machine classes and automation levels;
- Supplier evaluation framework combining technical capability, geographic footprint, aftermarket service metrics, and financial health to support vendor short‑lists;
- Regulatory impact matrix that quantifies likely compliance costs and identifies cost‑offsetting opportunities from energy‑efficient machines and process redesign;
- Use cases and case studies showing time‑to‑value from recent retrofit projects, including data on cycle time reductions, scrap rate improvements, and energy savings;
- Proprietary datasets and interactive charts (historical 2020–2025 and forecasts 2026–2032) enabling executives to drill from macro market sizing down to machine class and application scenarios.
Competitive landscape — what to watch in vendor strategy
The gear‑machining vendor space remains technologically rich and commercially competitive. Our competitive chapter profiles leaders and challengers, distilling implications for OEM buyers and aftermarket service partners. A few directional observations:
- Broad‑portfolio OEMs with system capabilities: European and North American manufacturers offering integrated gear production lines retain an advantage for customers who prioritize single‑supplier responsibility for cycle time optimization and quality assurance. Their value proposition is strongest where customers seek end‑to‑end capability for high‑volume or high‑precision production.
- Specialists and performance niches: Companies focused on particular machine types — such as high‑speed hobbing, super‑dry cutting, or bevel gear technologies — continue to win on technical performance and tooling ecosystems. For buyers, adopting niche technology can yield material productivity gains but requires careful aftermarket and tooling alignment.
- Service and aftermarket as differentiators: As machines become more software‑enabled and energy‑optimized, the ability of a supplier to provide rapid, data‑driven support and local spares determines long‑term uptime. This is where smaller, service‑oriented players can compete effectively against larger OEMs.
Representative firms profiled in the report include established gear‑machining names across Europe, North America, and Asia, each evaluated on machine portfolios, innovation pipeline, geographic service coverage, and recent market activity. The profiles are designed to help sourcing teams construct negotiations strategies that account for warranty structures, retrofit packages, and software/service bundling.
Recent industry signals shaping 2026 strategy
- Conferences and trade fairs: Global gear technology events in 2026 have accelerated exposure to new processes and live demonstrations. These venues are proving important for validating vendor claims and accelerating adoption of techniques such as skiving and advanced dry cutting.
- Tooling and materials: High‑performance hobs—manufactured from PM high‑speed steels and advanced powders with PVD coatings—are central to delivering longer tool life and improved surface integrity. Tooling suppliers now play a bigger role in the total cost equation than in the prior decade.
- Regulatory momentum: Energy efficiency standards and building performance codes in several industrial jurisdictions are translating into quantifiable plant‑level requirements, making energy metrics a first‑order selection criterion for new equipment.
- Exhibition activity: Leading OEMs are using major fairs to launch or showcase machine series optimized for dry cutting, higher automation, and integrated quality measurement — signaling the product directions that buyers should evaluate in 2026 purchasing cycles.
Key strategic implications and recommended actions for 2026
- Adopt a staged modernization approach: Prioritize retrofit of bottleneck cells and equipment that offer the fastest payback through energy savings and reduced downstream rework. Use the report’s TCO templates to validate vendor ROI claims.
- Sink or swim on digital enablement: Require potential suppliers to demonstrate data‑integration capabilities (MTConnect/OPC UA), predictive maintenance offerings, and clear KPIs for uptime and energy consumption as part of contract terms.
- Reassess procurement for resilience: Build dual‑sourcing strategies for critical spindles and hobs, and negotiate spare‑part consignment or local stocking agreements to reduce lead‑time exposure.
- Leverage incentives and compliance windows: Identify jurisdictional energy incentives and phase‑in periods for building codes to align machine purchases with grant and rebate opportunities, thereby improving net project economics.
Conclusion — the strategic value of the full PW Consulting study
For executive teams deciding on equipment spend, supplier selection, or M&A plays in 2026, the value of rigorous, actionable market intelligence cannot be overstated. This preview outlines the macro trajectory (base year 2025, forecast 2026–2032) and the structural dynamics that will determine winners and losers. The complete PW Consulting Gear Cutting Machines Market report supplies the proprietary segmentation, vendor scorecards, downloadable TCO models, and region‑specific scenarios that leaders use to convert market insight into confident capital and operational decisions.
To move from strategy to execution, access the full study for the detailed datasets, machine‑level comparisons, and step‑by‑step procurement playbooks that are intentionally excluded from this preview. Our research is designed to accelerate 2026 decision cycles — not to replace the supplier diligence and site‑level benchmarking that should follow.
For detailed analysis of this topic, please visit the official page: Gear Cutting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solketal (CAS 100-79-8) Market to Hit USD 107M by 2032 at 3.5% CAGR
By pmarketresearch, 2026-07-13
Solketal (CAS 100-79-8) Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise, decision-focused preview of our comprehensive Solketal market study. This briefing illustrates the strategic value of the full report for corporate boards, procurement leads, R&D heads and M&A teams planning moves in 2026. In keeping with our “trailer” principle, this piece demonstrates analytical depth and actionable frameworks while intentionally withholding the detailed segment tables and micro-level splits that are available in the full report.
Solketal (CAS 100-79-8) Market
Why Solketal matters now — the strategic headline
-
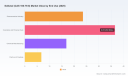
Market momentum: After steady expansion during 2020–2025, the Solketal market reached an estimated USD 83.7 Million in our 2025 base year. Our forecasts show continued expansion through the 2026–2032 horizon under a moderate-growth trajectory (CAGR ~3.5%). By the end of the forecast window the market approaches the low triple-digit million USD range, reflecting both product maturation and broadening industrial use cases.
Solketal (CAS 100-79-8) Market -
Concentration and bargaining power: The market exhibits a high degree of supplier concentration; the leading producers control a substantial share of available volume. That concentration creates asymmetric bargaining power, but also a relatively predictable supply base for strategic partnerships and targeted capacity investments.
Solketal (CAS 100-79-8) Market -
Regulatory and feedstock forces: Two converging trends—regulatory consolidation around classification and labeling, and stronger commercial emphasis on renewable feedstocks—are reshaping supplier value propositions and creating entry points for sustainability-led differentiation.
What the full PW Consulting Solketal report delivers (practical highlights)
-
Integrated market model (historical 2020–2025; detailed forecasts 2026–2032) with scenario sensitivity to feedstock price, regulatory shifts and end-market demand elasticity.
-
Primary-research validated demand drivers by end-use and application, accompanied by a demand-by-channel model suitable for business planning and revenue targets.
-
Supply-side mapping: global capacity, lead times, conversion routes and feedstock dependencies, plus a supplier scorecard covering quality, sustainability credentials, and commercial terms.
-
Commercial playbooks: go-to-market options for suppliers and buyers, contract structures to de-risk supply and price volatility, and a ready-to-use negotiation checklist for 12–24 month agreements.
-
Regulatory matrix and compliance tracker: current status across major jurisdictions, likely near-term regulatory moves, and compliance implications for labeling, transport and formulation.
-
Investment and M&A screening: target list of strategic and tuck‑in opportunities, valuation sensitivity, and a short-list of integration risks that matter most in this market.
Key market dynamics and the strategic levers for 2026
-
Feedstock sourcing as a strategic axis. Commercial producers are increasingly aligning upstream strategy to glycerol availability and quality. One supplier in the market today emphasizes production exclusively from renewable, plant-based glycerin (a biodiesel byproduct), a material choice that reduces lifecycle GHG intensity and appeals to sustainability-oriented formulators. For buyers and investors, traceability of glycerol and verified chain-of-custody will be decisive selection criteria in 2026.
-
Regulatory alignment is table stakes. Market participants are already asserting compliance under European classification and labeling frameworks; for example, certain Solketal grades have been documented as meeting REACH/CLP criteria under the classification rules referenced by suppliers. Those supplier statements shorten qualification lead times for customers but require independent verification for regulated end-uses (pharmaceutical intermediates, certain cosmetics channels).
-
Concentration-driven competitive dynamics. With the top three and top five suppliers accounting for a large majority of market volume, commercial dynamics are dominated by a few strategic players. This structure favors long-term offtake agreements and joint investments in conversion or capacity rather than spot procurement for significant volume needs.
-
Application-level evolution. Demand growth is being sustained by multiple, distinct end-use buckets — solvents and surface-care formulations, pharmaceutical intermediates, and emerging roles in biofuel and specialty chemical blends. Each bucket has different commercial and regulatory constraints; a single pricing or distribution strategy will not fit all.
Competitive landscape — signals that matter to executives
-
Solvay SA (Brussels, Belgium; see their Augeo brand materials) offers bio-based solvent grades and has been framing its Solketal-derived solutions for surface care, coatings and leather applications. Their approach combines product positioning with broad channel reach and formulation support—a model that works well where customers value application know-how and global distribution.
-
GLACONCHEMIE GmbH (Germany) positions a renewable-only feedstock pathway as a core differentiator. Their GLYCASOL® Solketal produced from plant-based glycerin is an example of a vertically integrated sustainability play. That feedstock narrative has commercial leverage with formulators seeking certifiable biosourced inputs.
-
Implication for buyers and partners: assess not only unit economics and lead times but the depth of supplier sustainability claims, chain-of-custody documentation, and critical formulation support. For potential acquirers, the premium often sits in application expertise and verified feedstock access rather than basic molecule production.
Scenario planning — practical trajectories to use in 2026 planning
-
Base case (our central forecast): moderate growth consistent with market maturation and incremental new use-cases. Under this trajectory, prudent companies should secure multi-year supply arrangements for core volumes, prioritize cost-to-serve improvements, and invest selectively in formulation support to capture higher-margin niches.
-
Upside case: faster substitution in higher-value end-uses (e.g., specialty solvents and pharma intermediates) coupled with glycerol oversupply driving feedstock cost improvements. In this scenario, accelerated market share capture is feasible through investment in application development teams and targeted M&A to add formulation IP.
-
Downside case: feedstock constraints, regulatory tightening, or significant new entrants compressing margins. Here, focus shifts to flexibility—alternative feedstock qualification, dual-sourcing strategies, and short-cycle product innovation to preserve margin.
Concrete recommendations for 2026 (0–36 months)
-
Immediate (0–12 months): perform a supplier stress-test using our supplier scorecard; secure hybrid contracts (fixed-volume + index-linked tranche) to stabilize costs while retaining upside flexibility; and validate supplier sustainability claims through third-party audits or certification evidence.
-
Near term (12–24 months): invest in formulation engineering to expand into adjacent premium applications, and consider strategic equity or supply partnerships with suppliers that control renewable glycerin streams.
-
Medium term (24–36 months): if pursuing M&A, prioritize targets with strong application IP and verified feedstock access rather than pure-play volume assets; integrate regulatory monitoring into product launch gates to avoid late-stage rework.
Risk matrix — what keeps boards awake
-
Regulatory surprises: tighter classification or transport restrictions can add compliance costs and restrict certain end-uses; ongoing monitoring and contingency labeling budgets are essential.
-
Feedstock volatility: dependence on biodiesel-linked glycerol creates exposure to biofuel policy swings and agricultural cycles; diversification or secured feedstock contracts mitigate this.
-
Concentration risk: reliance on a few suppliers risks supply interruption; diversification strategies and contractual protections should be built into procurement playbooks.
-
Substitution and disruptive chemistries: advances in green solvent technology could reconfigure end-use economics—active scanning of adjacent chemistries is required.
How PW Consulting helps — the practical next step
-
The full Solketal market report provides the proprietary, downloadable market model, supplier scorecards, and the granular segmentation tables we intentionally omit here. It also contains interactive scenario worksheets that let clients re-run the forecast using custom input assumptions for feedstock cost, offtake timing and regulatory outcomes.
-
For 2026, our most requested engagements are: (1) rapid supplier due diligence and contract renegotiation support; (2) go‑to‑market and licensing strategies for manufacturers seeking to move up the value curve; and (3) M&A target screening with a seven-point integration checklist specific to specialty solvent assets.
Final note: this preview provides the strategic rationale, high-level market trajectory and decision frameworks you need to orient 2026 plans. For the detailed, transaction‑grade tables, per-region and per-application splits, supplier-level volume data, and the interactive forecast workbook—access the full PW Consulting Solketal report. The granular intelligence there converts the strategic imperatives outlined above into executable workplans tailored to your risk posture, supply commitments and growth ambition.
Selected source signals referenced in this preview: supplier public brand materials (e.g., Solvay’s Augeo portfolio), supplier disclosures on renewable glycerin feedstocks, and supplier statements on classification/labeling compliance. In the full report we annotate every supplier claim to primary sources and provide verification status for each statement used in our model.
For detailed analysis of this topic, please visit the official page: Solketal (CAS 100-79-8) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Offshore AUV Market to Reach USD 5,207M by 2032 at 10.8% CAGR
By pmarketresearch, 2026-07-13
Offshore AUV Market — 2026 Strategic Primer
As offshore energy and defense operators recalibrate capital plans for the second half of the decade, the autonomous underwater vehicle (AUV) sector is moving from niche experimentation to operational scale. PW Consulting’s Offshore AUV Market study (base year: 2025; historical window: 2020–2025; forecast: 2026–2032) synthesizes market dynamics, vendor positioning, procurement signal, and practical adoption playbooks to guide executive decisions in 2026. This primer distills the study’s strategic value while preserving the granular tables and segmented forecasts that are reserved for subscribers.
Offshore AUV Market
Market Trajectory — What the topline means for 2026 choices
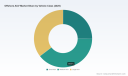
The sector’s macro momentum is clear: the market expanded from approximately USD 1.6 billion in 2020 to about USD 2.55 billion in 2025, reflecting a multi-year acceleration in commercial and defense deployments. Under our baseline forecast (2026–2032) the market is expected to grow at a compound annual growth rate of roughly 10.8%, pushing industry revenues into the multi‑billion dollar range by the early 2030s.
Offshore AUV Market
For decision-makers this trajectory creates three immediate imperatives for 2026 planning:
Offshore AUV Market
- Prioritize optionality in fleet and capability investments: the environment favors modular platforms and upgradable autonomy stacks that can be re-purposed across inspection, survey, and light intervention missions.
- Lock early contractual levers for recurring services (data, analytics, managed operations) rather than treating AUVs solely as capital expenditures; recurring revenue models will capture disproportionate long‑term value.
- Embed resilience into procurement: diversified supplier relationships and validated integration roadmaps mitigate lead‑time and testing risks as demand spikes for both commercial energy and naval applications.
Key demand signals shaping 2026 strategies
Several secular and event‑driven factors underpin the forecast and should be front-of-mind when setting 2026 budgets:
- Asset integrity on legacy infrastructure: extensive pre-2010 pipeline networks and aging subsea assets create sustained inspection and repair demand that is both predictable and capital‑intensive.
- Renewable energy expansion: offshore wind and associated cable networks increase requirements for frequent, high‑resolution seabed mapping and cable inspection missions, favoring medium‑ to long‑endurance AUVs and rapid‑deployment workflows.
- Defense dual‑use momentum: naval procurement programs and defense innovation initiatives are moving AUVs into scaled operational roles (including mine-countermeasure and persistent surveillance), stimulating investment in dual‑mode platforms and hardened autonomy.
- Commercialization of data services: customers increasingly value processed outputs (anomaly detection, digital twins, predictive integrity indices) over raw sensor logs—creating service layer economics adjacent to vehicle sales.
Competitive landscape — who matters and why
The Offshore AUV space remains moderately fragmented: incumbent OEMs, specialist integrators, and defense-focused builders coexist with a rising set of scale‑up vendors. Market concentration metrics indicate meaningful room for competitive maneuver — the top few vendors do not dominate to the extent seen in more mature marine subsectors, leaving opportunity for entrants with targeted differentiation.
Core vendors profiled in our study illustrate distinct strategic postures:
- Kongsberg Maritime (Norway) — a leader in long‑endurance deep‑water survey AUVs, with a product lineage optimized for high-availability subsea inspection and mapping missions. Recent fleet deliveries and acceptance tests highlight enterprise‑grade reliability demanded by defense and commercial customers.
- Oceaneering International (USA) — positions AUVs as part of integrated service offerings, coupling vehicle platforms with onshore remote operations centers and life‑cycle service contracts; recent contract awards underscore defense and national oil company demand for turnkey solutions.
- Teledyne Marine (USA) — offers a portfolio targeting seabed mapping and cable inspection, appealing to offshore wind and energy survey workflows; their product ecosystem is often purchased as part of larger survey packages.
- Exail Technologies and ECA Group (France) — combine defense pedigree with commercial expansion, enabling technology transfer from military to civil inspection markets; their focus on autonomy and mission assurance is notable for buyers requiring certified performance.
- ISE Ltd, Cellula Robotics, Kraken Robotic Systems, Bluefin Robotics, Saab Seaeye — these firms illustrate the spectrum of specialist and hybrid approaches: from compact, rapid‑deployment scouts to hybrid AUV/ROV systems that promise 360‑degree maneuverability and light intervention capability.
Strategic takeaways for suppliers and buyers in 2026:
- OEMs: double down on modular payload ecosystems and invest in on‑vessel and cloud‑native data pipelines—buyers will increasingly procure solutions, not just platforms.
- Integrators and service providers: capture early share via managed services and outcomes‑based contracts; demonstrate end‑to‑end reliability and data assurance to justify premium pricing.
- Buyers (operators/national customers): evaluate total cost of ownership over multi‑year horizons, including training, spares, and data licensing; consider dual procurement tracks for near‑term capability and medium‑term platform consolidation.
Recent market moves and what they signal
Our study tracks a range of developments that validate the market narrative: sizable defense contracts for dual‑mode and mine‑countermeasure AUVs; commercial contracts supporting offshore wind farm inspections and hydrocarbon field surveys; and multi‑year production agreements linking large shipbuilders with AUV manufacturers. Collectively, these events indicate accelerating operationalization of AUVs across both government and commercial buyers, with corresponding growth in aftermarket services and remote operations capabilities.
What PW Consulting’s full study delivers (practical, actionable content)
The report was developed with a practitioner audience in mind. Highlights include:
- Top‑line market sizing and forecast (2026–2032) with scenario sensitivity to price declines, autonomy improvements, and service adoption rates.
- Demand‑signal mapping across procurement cohorts (operators, service companies, navies), including the decision criteria that drive fast adoption versus conservative pilots.
- Commercial playbooks: proof‑of‑value pilot templates, contracting templates for managed services, and go‑to‑market approaches for OEMs and system integrators.
- Vendor assessment framework: easy‑to‑apply scoring for platform maturity, data capabilities, regulatory posture, and after‑sales support (detailed vendor scorecards included for subscribers).
- Total cost of ownership models comparing CAPEX and OPEX levers under alternate operational profiles, with sensitivity to maintenance regimes, battery performance, and crew/time‑on‑site economics.
- Technology and product roadmaps: where autonomy, energy density, and hybrid AUV/ROV concepts create stepping stones for new mission sets.
- Regulatory and procurement risk register: emerging certification pathways, naval procurement trends, and export control considerations with mitigation recommendations.
Use cases and deployment patterns that will shape 2026 budgets
Operational experience from pilot programs and early fleet rollouts highlights productive deployment archetypes: recurring pipeline inspection campaigns, seasonal wind‑farm cable inspections, combined survey‑inspection sweeps during decommissioning, and defense persistent surveillance patrols. Each archetype has distinct vehicle endurance, payload, and operations-center requirements—our report maps these to procurement templates to accelerate decision cycles.
Decision checklist for 2026 executives
- Define desired outcomes first (e.g., risk reduction, increased inspection cadence, lower incident response time), then identify which mix of AUV, ROV, and surface assets achieves that outcome most cost‑effectively.
- Require demonstrable integration between vehicle platforms and data analytics—proof points should include automated anomaly detection and an audit trail for regulatory compliance.
- Negotiate stepwise scaling in contracts—start with pilot gating metrics and explicit options for fleet expansion tied to demonstrated KPIs.
- Build alliances with vendors that can offer lifecycle services (spares, onshore remote ops, crew training), not just one‑time hardware sales.
- Reserve dedicated funding for cybersecurity and OT/IT convergence; as AUVs shift toward remote operations, attack surfaces expand.
Why this study is strategically valuable in 2026
In 2026, organizations need a market view that combines credible macro forecasts with actionable procurement and integration guidance. PW Consulting’s Offshore AUV Market study delivers both: a defensible topline trajectory (with historical context and a 10.8% forecast CAGR), a vendor‑level assessment of who can deliver at scale, and the operational playbooks operators and suppliers need to move from pilots to repeatable revenue streams. The analysis identifies where competitive advantage will accrue—often not from vehicle hardware alone but from bundled services, data differentiation, and integration competency.
Next steps
This primer outlines the strategic contours that will influence capital allocation and partner selection in 2026. The full report contains the detailed segmentation, vendor scorecards, contract databases, and financial models that underpin these conclusions. For executive summaries tailored to your role (operator, OEM, investor, or integrator) and for access to the full dataset and models, contact PW Consulting’s Offshore Energy practice or visit our report portal to obtain the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Offshore AUV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hepatitis A Vaccine Market Poised for 11.6% CAGR (2026–2032) — PW Consulting
By pmarketresearch, 2026-07-13
Hepatitis A Vaccine Market 2026: Strategic Snapshot for Executive Decision-Making
As governments, manufacturers, and procurement bodies recalibrate immunization priorities in a post-pandemic landscape, Hepatitis A vaccine demand is entering a phase of accelerated expansion and re‑pricing. PW Consulting’s latest market study — grounded in a 2025 base year and a 2026–2032 forecast window — quantifies that trajectory and translates it into actionable strategy for 2026 decision cycles. This preview outlines the high‑level market dynamics, competitive topology, and the practical levers executives must consider, while reserving the full segment-level intelligence for report subscribers.
Hepatitis A Vaccine Market
Why this research matters for 2026 decisions
Two operational realities make 2026 pivotal. First, our modelling shows the global Hepatitis A vaccine market passing a pronounced inflection point in the first forecast year (2026) and sustaining a robust compound annual growth rate (CAGR) of 11.59% through 2032. In numeric terms, the market base measured in 2025 and the projected market size by 2032 make clear that the sector is on track to roughly double in scale within the forecast horizon. Second, shifting public health guidance and procurement modalities are changing who buys, how they buy, and what suppliers can sustainably deliver. The intersection of these trends generates concentrated windows for product launches, contract wins, manufacturing investments, and strategic M&A in 2026.
Hepatitis A Vaccine Market
Market trajectory: growth, scale and concentration
-
Scale and momentum: From the historical series underlying our base-year assessment (2020–2025), the market has expanded steadily and enters 2026 at a materially higher run‑rate than five years prior. The forecast path through 2032 is characterized by accelerating absolute revenues and rising unit demand across multiple channels.
Hepatitis A Vaccine Market -
Market structure: The market exhibits a relatively high level of concentration — our concentration metrics show that the top three players control a dominant share, with the top five consolidating an even larger portion of the market. That structure creates durable advantages for incumbents but also creates targeted opportunities for challengers with differentiated technology, cost or geographic access.
-
Implication: Buyers and investors should treat Hepatitis A as a growth market with competitive scarcity — planning horizons must prioritize supply security and scalable production capacity.
Demand drivers and policy shifts
-
Policy recalibration: Public health bodies have adjusted Hepatitis A vaccination recommendations in response to shifting epidemiology and budget priorities. Notably, as of January 2026, certain major advisory bodies have focused routine recommendations toward higher‑risk cohorts or shared decision‑making models rather than universal childhood schedules. That policy pivot compresses some traditional demand channels while enlarging opportunities in targeted adult and travel/occupational vaccination programs.
-
Programmatic funding and procurement evolution: Donor programs, sovereign tenders and middle‑income market procurement strategies are increasingly sophisticated—favoring suppliers that can demonstrate stable long‑term supply, regulatory acceptance (including WHO prequalification where applicable), and capacity for bundled supply across vaccine portfolios.
-
Private‑sector dynamics: Private immunization demand remains a significant and often higher‑margin component of overall volumes, but is sensitive to pricing transparency and list‑price versus contract price differentials. The resulting commercial dynamics place premium value on tender intelligence, tiered pricing strategies and commercial contracting expertise.
Supply-side landscape and competitive positioning
The competitive map is anchored by established vaccine manufacturers with globally deployed Hepatitis A products and varying configurations (single-antigen and combination vaccines). In our assessment, incumbent manufacturers maintain entrenched positions through long-standing programmatic supply, regulatory dossiers and global commercial footprints — yet the field is not static.
-
Global incumbents: Manufacturers with legacy Hepatitis A brands continue to supply the majority of institutional programs and private markets. Their advantages include brand recognition, pediatric and adult formulations, and regulatory approvals across multiple jurisdictions.
-
Regional champions: Companies that secured early regulatory recognition in key emerging markets — and those with WHO prequalification — are converting regional dominance into international supply contracts. Recent contract activity underscores this trend.
-
2026 developments to watch: In early 2026 a leading Chinese manufacturer secured an exclusive public‑sector supply contract in a Middle Eastern market for 2026–2027, highlighting how regionally credible suppliers are penetrating public programs. Meanwhile, a major European vaccine manufacturer received renewed regulatory approvals in mid‑2026 for both its monovalent Hepatitis A product and a combined Hepatitis A/B formulation — events that will influence product eligibility in tenders and private markets.
-
Implication: For suppliers and buyers alike, 2026 is a year for structural plays — either to shore up market access via regulatory lifecycle management and supply agreements, or to pursue tactical wins where incumbents face manufacturing or contractual bottlenecks.
Pricing, procurement and risk
-
Price dispersion: The market exhibits meaningful dispersion between public contract levels and private list prices. This gap creates both arbitrage and risk: procurers can realize savings through centralized contracting, but suppliers face margin pressure unless they capture volume and cost improvements.
-
Procurement sophistication: Buyers increasingly use multi‑year agreements, capacity reservation clauses and performance‑based penalties to ensure supply continuity. Advanced purchasers are also integrating supply‑chain resilience metrics into contract evaluation, such as dual‑sourcing thresholds and inventory buffers.
-
Manufacturing and regulatory risk: Single‑source production lines and legacy facilities remain vulnerability points. Regulatory approvals, including updates to product labels and combination vaccine dossiers, materially affect manufacturer competitiveness — as demonstrated by the mid‑2026 regulatory update for a major manufacturer in our coverage universe.
What this means for strategic choices in 2026
Executives must move beyond tactical tender responses and adopt an integrated, 24‑month playbook that aligns commercial, regulatory and manufacturing levers. Key imperatives include:
-
Supply security first: Secure multi‑year contracts with clearly defined delivery windows and fail‑over options; where feasible, invest in contract clauses that enable on‑shoring or third‑party fill‑finish partners to reduce disruption risk.
-
Portfolio sequencing: For manufacturers, prioritize regulatory filings (including combination formulations and label extensions) that unlock large programmatic buyers; similarly, buyers should map licensure timelines into procurement windows to capture favorable competition.
-
Pricing telemetry and segmentation: Build models that incorporate public contract dynamics and private market elasticity to optimize price points by channel and geography. Price alone is not the sole determinant; delivery reliability and regulatory coverage often tip procurement decisions.
-
Partnerships and M&A: Identify inorganic targets that deliver either capacity expansion or strategic market entry — particularly suppliers with WHO prequalification and proven public‑sector contracting experience.
-
Evidence and advocacy: Fund real‑world evidence generation that demonstrates vaccine performance in adult and special‑risk cohorts to influence policy direction and expand eligible populations in countries re‑assessing routine recommendations.
What PW Consulting’s full report delivers (practical, operational content)
The full study is designed as an operational guide for 2026 execution. Subscribers will gain:
-
Detailed market sizing and forecast tables (2020–2032) with scenario runs and sensitivity cases;
-
Country‑level tender calendars and a heatmap of procurement risk across priority markets;
-
Competitive battlecards for the leading manufacturers, including regulatory status, product portfolios, manufacturing footprints and contract position estimates;
-
Procurement playbooks and tender evaluation templates that align with buyer objectives (cost, supply security, and regulatory coverage);
-
Price‑elasticity and margin models to stress‑test commercial strategies without exposing confidential contract details in this preview;
-
Manufacturing capacity maps, recommended de‑risking actions, and M&A target screening criteria;
-
Actionable go‑to‑market roadmaps for new entrants and disruption scenarios for incumbents.
These deliverables translate market projections and qualitative intelligence into time‑bound actions for 2026 — from boardroom investment decisions to tender response playbooks and regulatory prioritization.
Quick strategic checklist for leaders preparing 2026 plans
-
Confirm capacity commitments and establish alternative fill‑finish agreements where possible.
-
Run scenario planning against our base forecast and upside/downside cases to stress capital allocation decisions.
-
Prioritize regulatory filings that unlock the largest institutional buyers in your target markets.
-
Negotiate multi‑year agreements with price review mechanisms tied to CPI and raw material indices.
-
Operationalize real‑world evidence initiatives to influence shared‑decision policy shifts and expand addressable populations.
Conclusion — why the 2026 window is decisive
Hepatitis A vaccines are moving from steady demand into a phase of accelerated commercial activity and strategic repositioning. The combination of a strong underlying CAGR, concentrated supplier positions, regulatory updates and differentiated procurement approaches makes 2026 the year to lock in supply and to realign portfolios. PW Consulting’s full report provides the granular segment intelligence, tender‑level insights and executable templates that senior teams need to translate market growth into competitive advantage — while preserving the discreet data that underpins confident contracting and capital deployment.
To access the comprehensive datasets, market maps and operational playbooks referenced in this preview, consult the full Hepatitis A Vaccine Market report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Hepatitis A Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pentaerythritol Market to Hit USD 304.6M by 2032 at 5.15% CAGR
By pmarketresearch, 2026-07-13
Pentaerythritol (CAS 115-77-5) Market — Strategic Imperatives for 2026
As companies reset priorities for 2026, the pentaerythritol value chain requires a fresh strategic lens. PW Consulting’s latest Pentaerythritol Market study (base year 2025, forecast 2026–2032) synthesizes a complex mix of demand resilience, concentrated supply, feedstock volatility and regulatory friction into an executable playbook. The market, which has expanded from the low hundreds of millions in 2020 to USD 215.0 Million in 2025, is projected to continue growing at a compound annual growth rate of 5.15% through 2032, reaching roughly USD 304.6 Million by the end of the forecast horizon. These headline dynamics deserve careful interpretation: steady aggregate growth masks significant regional, application and cost-driven fissures that will determine winners and losers in 2026 and beyond.
Pentaerythritol (CAS 115-77-5) Market
Why this study matters to corporate leaders in 2026
-
Capital allocation and capacity timing: The market’s mid-single-digit CAGR creates opportunities for selective capacity additions, but timing and location will determine margin recovery versus overcapacity risk.
Pentaerythritol (CAS 115-77-5) Market -
Commercial contracting and pricing strategy: With a market structure that is meaningfully consolidated at the top, price-setting power and contract design (indexation to feedstock, flex clauses) will be differentiators.
Pentaerythritol (CAS 115-77-5) Market -
Feedstock integration and procurement: Formaldehyde-linked cost swings remain the primary margin lever; procurement strategies and backward integration options must be stress-tested across realistic scenarios.
-
Sustainability and product differentiation: Renewable and ISCC-certified grades are emerging as commercial premiums — influencing offtake structures and customer segmentation.
-
Trade, tariff and regulatory planning: Recent tariff measures and HS-classification nuances have created new trade frictions that alter regional arbitrage economics.
Key market signals and what they imply
-
Resilient aggregate demand. Between 2020 and 2025 the market climbed from roughly USD 163 Million to USD 215 Million. That trajectory — and the forecast out to 2032 — shows a market with durable end-use demand despite episodic price variance.
-
Concentrated supplier structure. The market concentration ratio for the top three and top five producers indicates a landscape where a handful of players capture a substantial share of supply. That concentration creates both stability and strategic vulnerability: coordinated commercial behaviour becomes possible, but congestion around feedstock, logistics and regulatory approvals can quickly compress margins for marginal producers.
-
Feedstock risk dominantes costs. Formaldehyde is the single largest cost input and its volatility is the dominant short-term margin driver. Procurement strategies that ignore feedstock linkage expose producers to outsized earnings volatility.
-
Regulatory and trade noise is non-trivial. Recent duties and classification specificities have created new barriers to traditional trade flows and will shape near-term arbitrage and stock build behaviour.
Competitive landscape — leaders, challengers, and niche specialists
-
Large global producers with strategic upgrades: Established multinational producers have been active with strategic capacity moves and new product grades that target sustainability-conscious buyers. These companies combine global sourcing, branded specialty grades and technical service, which gives them leverage in high-value downstream segments.
-
Regional scale players in Asia: Several larger regional producers have been accelerating domestic investments and feedstock integration strategies to capture local demand and export opportunities. This creates a dual effect: intensified local competition and potential for export-led pricing pressure where logistics and duties allow.
-
Specialty and niche suppliers: A cohort of smaller specialty producers focuses on industrial or pharmaceutical-grade pentaerythritol and technical service. These players defend margins through formulation support, tighter service level agreements and localized supply assurance.
-
Strategic implications: For incumbents, the playbook is to protect margin via product differentiation (renewable/ISCC grades), secure feedstock access and optimize global footprint against tariff and shipping cost differentials. For entrants, niche focus, technical excellence and downstream partnerships offer the fastest path to commercial traction.
Recent industry developments that signal structural shifts
-
Capacity additions and technology upgrades have continued into 2024–2025, with recent plant starts and line launches positioned to capture demand in coatings, lubricants and higher-purity applications. These moves accelerate the push toward specialty grades and renewables.
-
Price volatility in late 2025 demonstrated how rapidly margins can swing; month-over-month volatility and notable year-over-year movements have been observed in key markets.
-
Policy interventions — including new import measures in specific markets introduced in 2024 — are already shaping trade patterns. Commercial and trade teams must incorporate these changes into route-to-market and sourcing strategies immediately.
Raw-material and regulatory levers you cannot ignore
-
Formaldehyde remains the critical input: it typically represents the single largest portion of operating cost and is therefore the primary exposure to monitor. Scenario modelling in our study quantifies P&L sensitivity across a range of formaldehyde price paths and feedstock supply disruptions.
-
Import duty regimes and HTS classifications materially alter landed economics. Companies should treat tariff announcements as strategic events — prompting immediate reviews of contract terms, hedging, and regional sourcing shifts.
-
Environmental and sustainability credentials (e.g., ISCC certification) are increasingly monetizable. Investment in renewable feedstock-compatible process routes is no longer only a compliance exercise — it is a revenue management decision.
Actionable 2026 playbook — recommended moves by function
-
Executive leadership: Re-run capital prioritization with three scenarios (soft, base, upside) for 2026–2028. Prioritize flexibility (brownfield debottlenecking vs large greenfield) and include contractual flex with offtakers.
-
Commercial teams: Renegotiate indexation clauses to formaldehyde benchmarks where possible, introduce rolling offtake options for strategic customers, and segment customers by willingness-to-pay for specialty/renewable grades.
-
Procurement: Implement layered hedging, secure alternative formaldehyde sources, and evaluate backward integration or long-term tolling partnerships to de-risk feedstock exposure.
-
M&A and business development: Target bolt-on acquisitions that provide feedstock integration, access to specialty grades or regional offtake. Smaller strategic acquisitions can be value-accretive faster than large greenfield projects.
-
R&D and sustainability: Fast-track product lines that capture premiums for renewable-certified pentaerythritol equivalents and invest in technical service capability to lock in premium channels (e.g., high-performance coatings, specialty lubricants).
What PW Consulting’s full study delivers (practical and actionable)
-
Reconciled market sizing and transparent forecast methodology covering 2020–2032, enabling board-level validation of market assumptions.
-
Demand-driver diagnostics by application with scenario-based volumetric models and elasticity sensitivities suitable for commercial planning.
-
Supply-side mapping and a granular, anonymized production roster that highlights capacity vintages, technology profiles and probable steam/energy intensity — indispensable for operations and investment teams.
-
Price modelling that links feedstock benchmarks, freight and duty permutations to producer margin outcomes under multiple macro scenarios.
-
Regulatory and trade impact assessment with action checklists for trade teams and procurement.
-
Deal and valuation guidance for M&A, including precedent transactions, valuation frameworks and integration risk matrices.
-
Ready-to-use executive summaries, slide decks and a downloadable data appendix to accelerate decision-making.
How to use this insight in Q1–Q2 2026
-
Embed the study’s scenarios into capital expenditure approvals and rolling three-year operating plans.
-
Use the supply mapping to stress-test existing offtake agreements and prioritize suppliers for renegotiation based on resilience and sustainability credentials.
-
Prioritize short-list M&A targets that offer feedstock security or high-margin specialty channels; run accelerated diligence that focuses on cash-flow resilience under feedstock stress tests.
-
Align commercial incentives with price realizations: create sales compensation that balances volume growth with margins on premium grades.
Closing — why Pentaerythritol is a timely strategic focus
Pentaerythritol sits at the intersection of traditional chemical commodity dynamics and emergent specialty value creation. Aggregate growth is steady and predictable at the market level; the real value for 2026 decision-makers lies in navigating feedstock volatility, regulatory shifts and the premiumization wave. PW Consulting’s study converts these macro forces into near-term operational priorities and medium-term strategic options. We surface where margins will be protected, where pricing pressure is likely, and which capability bets offer the highest return on invested capital — while preserving the detailed segmentation and unit-economics analysis behind our conclusions for clients who require the underlying datasets.
To access the full model, detailed segmentation, supplier-by-supplier maps and scenario-specific P&L impact tables, visit the report page or contact PW Consulting’s head of practice for the Pentaerythritol study. The executive summary above highlights what to act on now — the full study gives you the play-by-play to execute.
For detailed analysis of this topic, please visit the official page: Pentaerythritol (CAS 115-77-5) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Anti-Vibration Rubber Mounts Market: PW Consulting Forecasts 2.1% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Anti Vibration Rubber Mounts Market — Strategic Outlook for 2026 Decision‑Making
Executive snapshot
As businesses prepare strategic plans for 2026, understanding the near‑term trajectory of the anti vibration rubber mounts market is non‑negotiable. PW Consulting’s latest market study benchmarks the sector across a full historical window (2020–2025) with a seven‑year forecast (2026–2032). At a macro level the market has shown steady expansion, registering a compound annual growth rate (CAGR) of 2.1% over the forecast period and reaching an estimated market size in the mid‑teens (USD Million) by the 2025 base year. By 2032 the market is projected to re‑approach the high‑teens (USD Million), reflecting modest but resilient demand driven by industrial replacement cycles, regulatory-driven retrofit programmes, and incremental growth in key OEM sectors.
Anti Vibration Rubber Mounts Market
Why this study matters for 2026 strategy
-
Actionable timing: 2026 is a pivot year for many buyers and suppliers — capex budgets, platform refresh cycles and regulatory audits converge. Our study converts those calendar pressures into strategic windows for procurement, product launches, and M&A.
Anti Vibration Rubber Mounts Market -
Risk calibration: with primary materials and feedstock exposed to commodity swings, near‑term cost volatility and sourcing concentration are core risks. The report quantifies these exposures and models scenario P&L impacts for OEMs and tier suppliers.
Anti Vibration Rubber Mounts Market -
Competitive posture: the market’s competitive footprint is moderately fragmented; the top three and five players account for a minority share of industry revenue, indicating scope for consolidation, focused differentiation and niche leadership plays.
Market dynamics — what is driving outcomes into 2026
-
Replacement and retrofit demand: Across heavy industrial and transportation sectors, existing installations are entering mid‑life service cycles, creating predictable replacement volumes. These steady aftermarket flows underpin a low‑double digit basis for suppliers even as OEM project wins fluctuate.
-
Material cost sensitivity: Natural rubber and synthetic rubber feedstocks remain a primary cost driver. In 2026 natural rubber price oscillation and quarterly volatility were material considerations for pricing strategy. Synthetic feedstock costs continue to track crude oil movements, and a significant proportion of manufacturers report supply cost instability — a dynamic that amplifies margin pressure for vertically integrated producers and contract manufacturers alike.
-
Regulation and certification as market gates: Certifications and industry standards (railway, aerospace and environmental management certifications among others) are practical entry barriers in several end markets. Firms that can demonstrate IRIS, EN 9100, ISO and ASTM alignment often gain privileged access to procurement lists and long‑term contracts.
-
Technology in product development: Simulation and AI‑enabled design platforms are accelerating time‑to‑validation for complex isolators. The adoption of advanced CAE platforms by leading component manufacturers is shortening design cycles for bespoke solutions — an advantage for suppliers seeking OEM co‑design engagements.
Competitive landscape — who to watch in 2026
The market is served by a mix of specialised independents and multinational engineering groups. Several players consistently feature in strategic dialogues for customers and investors:
-
GMT Rubber‑Metal‑Technic Ltd (UK) — strong in bonded rubber‑to‑metal solutions across rail, defence and aerospace, with established certifications that support regulated contracts.
-
Polymax Ltd (India/UK) — high SKU breadth and bespoke manufacturing capabilities, positioned for rapid fulfilment and custom designs.
-
AV Industrial Products Ltd (UK) — known for bespoke hydro and cone mounts tailored to off‑highway and marine customers.
-
Trelleborg AB (Sweden) — global engineering reach with comprehensive anti‑vibration portfolios and materials engineering scale.
-
Dynemech Systems, Vibrasystems, Minor Rubber Company and regional manufacturers such as Delta Rubber — these firms provide critical regional capacity, specialised product ranges and aftermarket service footprints.
Recent strategic moves underline two forces shaping competition in 2026: technology adoption and geographic footprint expansion. Examples include large OEMs and system suppliers adopting simulation platforms to accelerate design validation, and acquisitive moves to consolidate regional capability and access end‑market clients.
Supply chain and cost considerations for procurement and manufacturing
-
Raw material volatility: Natural rubber exhibited meaningful intra‑year fluctuation; buyers should expect periodic cost pass‑through negotiations and consider hedging or alternative compound specifications where feasible.
-
Feedstock sensitivity to oil markets: Synthetic rubber components remain exposed to crude price corridors. Purchasing strategies that blend natural and synthetic inputs, or that secure longer‑term contracts with indexation clauses, mitigate short‑term margin shocks.
-
Certification and supply continuity: Suppliers holding key certifications and diversified production footprints demonstrate higher resilience in regulated tenders and in events of supply chain disruption.
What the PW Consulting report contains — operational value for 2026
Recognising that executives need precise, executable intelligence rather than academic summaries, our study delivers practitioner‑level outputs designed for boardroom and procurement teams:
-
Methodology and verified market sizing: transparent modelling assumptions for historical and forecast windows, with sensitivity cases for commodity shocks and demand shifts.
-
Segment and channel playbooks: end‑use, product‑type and distribution channel analysis that translate into go‑to‑market recommendations, pricing tactics and customer segmentation frameworks. (Note: detailed segment revenue tables are available in the full report.)
-
Supplier scorecards: capability matrices and certification audits that support supplier selection, dual‑sourcing plans and qualification roadmaps.
-
Price modelling tools: scenario templates that map raw material price paths to component costs and margin outcomes—suitable for procurement negotiation and financial planning.
-
M&A and investment thesis: target archetypes, valuation levers and integration risks for buyers seeking inorganic scale or capability fills in 2026.
-
Commercial playbooks: product launch timing, specification trade‑offs (cost vs. performance), and case studies showing successful OEM co‑development tracks.
Strategic recommendations for 2026 leaders
-
Prioritise certification and quality evidence in bidding: for players targeting regulated sectors, fast‑tracking certifications or making transparent compliance commitments materially improves win rates.
-
Lock flexible supply arrangements: pursue hybrid contracts (short‑term buy + long‑term indexed agreements) to manage cost volatility while preserving supply security.
-
Invest selectively in simulation and digital validation: adopting or partnering for advanced design tools reduces prototype cycles and accelerates customer qualification, a differentiator in competitive OEM projects.
-
Explore bolt‑on M&A in regional markets: given the market’s moderate fragmentation, targeted acquisitions can quickly expand geographic access and aftermarket service capabilities.
-
Design modular product families: modularity reduces SKU proliferation for contract manufacturers while enabling OEMs to offer differentiated specifications without large NPI costs.
Use cases where the report is immediately applicable
-
Procurement teams preparing 2026 supplier RFQs and hedging strategies will find the price modelling and supplier scorecards directly implementable.
-
Corporate development teams evaluating bolt‑on acquisitions or partnership targets will benefit from the M&A thesis and target archetype framework.
-
R&D and product managers preparing OEM tenders can use the simulation adoption benchmark and go‑to‑market playbooks to de‑risk development timelines.
Closing — what to expect next
The anti vibration rubber mounts market entering 2026 is one of steady, structural demand with episodic cost and supply shocks. Strategic winners will be those who translate market visibility into procurement resilience, certification‑led market access and technology‑enabled product differentiation. PW Consulting’s full study provides the granular segment economics, regional breakdowns, and model files that underpin the executive recommendations summarized here — curated so your leadership team can execute confidently in 2026 and beyond.
To access the full datasets, proprietary segmentation tables, and downloadable scenario models, refer to the complete PW Consulting report and supporting materials.
For detailed analysis of this topic, please visit the official page: Anti Vibration Rubber Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lignin market set to reach USD 1,568 Million by 2032 at 4.9% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
Lignin and Lignin-Based Products: Strategic Intelligence Briefing for 2026 Decision-Making
As corporate leaders position portfolios for a low-carbon, circular materials economy, lignin has moved from laboratory promise to a commercially investible platform. PW Consulting’s forthcoming market study, with a 2025 base year and a 2026–2032 forecast horizon, quantifies a market that has expanded from under USD 900 million in 2020 to roughly USD 1.12 billion in 2025 and is projected to reach approximately USD 1.57 billion by 2032 — a compound annual growth rate (CAGR) of about 4.9%. This briefing explains why that trajectory matters for board-level strategy in 2026, highlights where value pools and risks are concentrated, and outlines the pragmatic actions senior teams should prioritize this year.
Lignin and Lignin-Based Products Market
Why 2026 Is an Inflection Point
-
Regulatory acceleration. New policy commitments in major markets — including the European Union’s aggressive packaging and bioeconomy mandates and intensified public funding programs in the U.S. — are converting aspirational demand for bio-based substitutes into enforceable procurement and recycling requirements. These changes compress time-to-market expectations for industrialized lignin applications (e.g., packaging, pigments, adhesives).
Lignin and Lignin-Based Products Market -
Commercial maturity of key applications. Over the past five years the industry has seen a broadening of commercially validated use-cases: dispersants and concrete admixtures now operate at scale; resin and binder replacements are moving through pilot to early commercial adoption; and novel use-cases—carbon-negative pigments and lignin thermoplastics—have emerged with credible tech-paths to industrial economics.
Lignin and Lignin-Based Products Market -
Consolidation and concentration. The competitive structure shows meaningful concentration at the top of the value chain, with a relatively small set of players controlling a disproportionate share of industrial-scale supply and proprietary process technologies. This concentration creates both barriers and partnership opportunities for new entrants and incumbents seeking to vertically integrate.
What the Market Numbers Mean for Strategy
-
Measured but resilient growth: a ~4.9% CAGR through 2032 signals steady expansion rather than explosive disruption. For corporates this translates into a dual imperative: preserve optionality across multiple technology and product paths while committing selectively to near-term, revenue-generating deployments.
-
Scale matters: the path from demonstration to profitable production is capital- and feedstock-intensive. Firms that can secure predictable lignocellulosic feedstock — either via upstream integration with pulp mills or long-term offtake contracts — will enjoy structural cost advantages.
-
Timing of investment: 2026 is the year to move beyond studies. The market size and forecast demonstrate sufficient addressable demand to justify pilots with industrial partners, small-scale commercial runs, and customer co-development for packaging, adhesives, pigments and construction chemicals.
Core Report Offerings — What PW Consulting Delivers
-
Proprietary market model: multi-year historical reconstruction (2020–2025) and scenario-based forecasts to 2032, with sensitivity to feedstock pricing, regulatory variables, and end-market adoption rates.
-
Go-to-market playbooks: product-market fit analysis for high-potential segments, recommended pilot designs, channel strategies, and first-customer acquisition frameworks.
-
Operational economics: plant-level cost curves and build-versus-buy TEA (techno-economic analysis) showing capex/Opex break-evens for common conversion routes and capacity scales — designed for use in board-level capital allocation debates.
-
Commercial due diligence kits: target-screening matrices, synergy assessments, and red-flag checklists tailored for M&A, JV, and licensing negotiations.
-
Policy and circularity playbook: regulatory impact maps, compliance timelines, and consumer-recycling guidance to support defensible sustainability claims and compliance planning.
-
Risk register and mitigation matrix: feedstock security, process upsets, customer acceptance barriers, IP exposure, and recycling system integration risks — each paired with pragmatic mitigation steps.
Competitive Landscape — Strategic Implications
The industry map is a mix of large forest-product incumbents, specialized chemical suppliers, innovators commercializing new lignin chemistries, and technology enablers. Key profiles and strategic takeaways include:
-
Borregaard LignoTech (Sarpsborg, Norway) — Global leader in Kraft lignin capacity and commercial product lines (resins, dispersants). Their recent launch of a lignin-based laundry powder underscores a shift from ingredient supply to finished-product innovation; expect them to push for premium positioning on sustainability claims and rapid scale-up of consumer-facing applications.
-
Stora Enso (Helsinki, Finland) — Strong integration with pulp operations and established lignin-derived resin products. Their capabilities make them a preferred partner for companies seeking secure feedstock and industrial co-development.
-
UPM Biochemicals (Helsinki, Finland) — Differentiates through novel, traceable lignin-derived pigments and carbon-negative product claims. Their NIR-detectable pigment launch highlights the growing importance of circularity and recyclability in product design.
-
Domtar, West Fraser, Rayonier Advanced Materials — These players represent the effective industrial base for high-purity Kraft lignin production; strategic partners for downstream firms seeking reliable volumes.
-
Ingevity, Domsjö, Changzhou Shanfeng — Specialized chemical companies strong in dispersants, binders and bulk lignosulfonate markets. They compete on formulation expertise and global distribution networks.
-
Smaller innovators — Lignin Industries AB, Lignolix, MetGen — These players are critical sources of disruptive product technology: thermoplastic granules, organosolv lignin streams, and enzymatic valorization services respectively. Recent funding and product launches indicate a wave of commercialization potential that larger incumbents may seek to acquire or partner with.
Taken together, the competitive picture suggests multiple valid strategic postures in 2026: (1) integrate upstream to secure feedstock and margin; (2) partner with technology specialists to accelerate product differentiation; or (3) pursue M&A to consolidate access to industrial-scale capacity. Execution choice should be guided by capital availability, time-to-market goals, and downstream customer relationships.
Recent Industry Signals to Monitor Closely
-
Productization momentum: commercial launches of lignin-derived consumer products and pigments are beginning to test end-user acceptance and recycling-system compatibility — early wins here will set reference pricing and brand narratives.
-
Policy tailwinds: EU packaging and bioeconomy mandates and sustained DOE funding in the U.S. materially affect payback timelines for capital investments and increase the strategic value of traceable, recyclable lignin solutions.
-
Capital formation: venture and growth capital flows into lignin technologies (e.g., thermoplastics, organosolv processes) are creating acquisition targets for incumbents seeking technological leapfrogs rather than building in-house R&D from scratch.
Practical 2026 Playbook — Priorities for Executives
-
Rapidly validate a 12–24 month commercialization pathway for one or two lignin-based products aligned to your customer base. Design pilot metrics that map directly to unit economics at modest scale (tens to low hundreds of tonnes).
-
Secure feedstock optionality. Negotiate flexible offtake agreements with pulp mills or consider minority stake arrangements in lignin production assets to protect margin and supply continuity.
-
Lock in traceability and circularity credentials early. Invest in chain-of-custody systems and material detection capabilities (e.g., NIR-identifiable additives) to reduce regulatory and market risk for packaging and consumer applications.
-
Prioritise partnership over solo-build in high-uncertainty domains. For high-value, high-technology pathways (organosolv lignin, enzymatic upgrading), strike collaborative R&D or licensing arrangements with specialist technology firms.
-
Embed policy scenario planning in capex decisions. Use downside-protected investment structures (stepwise build, capacity options) tied to regulatory milestones and offtake confirmations.
Limitations and Where to Find the Full Intelligence
This briefing synthesizes the market-level trajectory and strategic implications. PW Consulting’s full study contains the detailed segmentation, pricing curves, regional and application-level demand matrices, plant-level cost models, company-level volume and share estimates, and playbooks formatted for immediate internal use. We intentionally withhold granular subsegment tables and company-specific revenue shares here to preserve the report’s value as an actionable, purchasable deliverable.
If your 2026 capital allocation, innovation roadmap, or M&A pipeline is being shaped right now, PW Consulting’s full Lignin and Lignin-Based Products Market report provides the operational detail, vendor scoring, and negotiated negotiation checklists required to move from strategy to execution with confidence.
For detailed analysis of this topic, please visit the official page: Lignin and Lignin-Based Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com