

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Solketal (CAS 100-79-8) Market to Hit USD 107M by 2032 at 3.5% CAGR

Solketal (CAS 100-79-8) Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise, decision-focused preview of our comprehensive Solketal market study. This briefing illustrates the strategic value of the full report for corporate boards, procurement leads, R&D heads and M&A teams planning moves in 2026. In keeping with our “trailer” principle, this piece demonstrates analytical depth and actionable frameworks while intentionally withholding the detailed segment tables and micro-level splits that are available in the full report.
Solketal (CAS 100-79-8) Market
Why Solketal matters now — the strategic headline
-
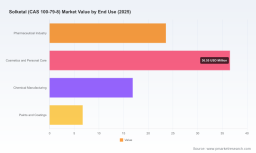
Market momentum: After steady expansion during 2020–2025, the Solketal market reached an estimated USD 83.7 Million in our 2025 base year. Our forecasts show continued expansion through the 2026–2032 horizon under a moderate-growth trajectory (CAGR ~3.5%). By the end of the forecast window the market approaches the low triple-digit million USD range, reflecting both product maturation and broadening industrial use cases.
Solketal (CAS 100-79-8) Market -
Concentration and bargaining power: The market exhibits a high degree of supplier concentration; the leading producers control a substantial share of available volume. That concentration creates asymmetric bargaining power, but also a relatively predictable supply base for strategic partnerships and targeted capacity investments.
Solketal (CAS 100-79-8) Market -
Regulatory and feedstock forces: Two converging trends—regulatory consolidation around classification and labeling, and stronger commercial emphasis on renewable feedstocks—are reshaping supplier value propositions and creating entry points for sustainability-led differentiation.
What the full PW Consulting Solketal report delivers (practical highlights)
-
Integrated market model (historical 2020–2025; detailed forecasts 2026–2032) with scenario sensitivity to feedstock price, regulatory shifts and end-market demand elasticity.
-
Primary-research validated demand drivers by end-use and application, accompanied by a demand-by-channel model suitable for business planning and revenue targets.
-
Supply-side mapping: global capacity, lead times, conversion routes and feedstock dependencies, plus a supplier scorecard covering quality, sustainability credentials, and commercial terms.
-
Commercial playbooks: go-to-market options for suppliers and buyers, contract structures to de-risk supply and price volatility, and a ready-to-use negotiation checklist for 12–24 month agreements.
-
Regulatory matrix and compliance tracker: current status across major jurisdictions, likely near-term regulatory moves, and compliance implications for labeling, transport and formulation.
-
Investment and M&A screening: target list of strategic and tuck‑in opportunities, valuation sensitivity, and a short-list of integration risks that matter most in this market.
Key market dynamics and the strategic levers for 2026
-
Feedstock sourcing as a strategic axis. Commercial producers are increasingly aligning upstream strategy to glycerol availability and quality. One supplier in the market today emphasizes production exclusively from renewable, plant-based glycerin (a biodiesel byproduct), a material choice that reduces lifecycle GHG intensity and appeals to sustainability-oriented formulators. For buyers and investors, traceability of glycerol and verified chain-of-custody will be decisive selection criteria in 2026.
-
Regulatory alignment is table stakes. Market participants are already asserting compliance under European classification and labeling frameworks; for example, certain Solketal grades have been documented as meeting REACH/CLP criteria under the classification rules referenced by suppliers. Those supplier statements shorten qualification lead times for customers but require independent verification for regulated end-uses (pharmaceutical intermediates, certain cosmetics channels).
-
Concentration-driven competitive dynamics. With the top three and top five suppliers accounting for a large majority of market volume, commercial dynamics are dominated by a few strategic players. This structure favors long-term offtake agreements and joint investments in conversion or capacity rather than spot procurement for significant volume needs.
-
Application-level evolution. Demand growth is being sustained by multiple, distinct end-use buckets — solvents and surface-care formulations, pharmaceutical intermediates, and emerging roles in biofuel and specialty chemical blends. Each bucket has different commercial and regulatory constraints; a single pricing or distribution strategy will not fit all.
Competitive landscape — signals that matter to executives
-
Solvay SA (Brussels, Belgium; see their Augeo brand materials) offers bio-based solvent grades and has been framing its Solketal-derived solutions for surface care, coatings and leather applications. Their approach combines product positioning with broad channel reach and formulation support—a model that works well where customers value application know-how and global distribution.
-
GLACONCHEMIE GmbH (Germany) positions a renewable-only feedstock pathway as a core differentiator. Their GLYCASOL® Solketal produced from plant-based glycerin is an example of a vertically integrated sustainability play. That feedstock narrative has commercial leverage with formulators seeking certifiable biosourced inputs.
-
Implication for buyers and partners: assess not only unit economics and lead times but the depth of supplier sustainability claims, chain-of-custody documentation, and critical formulation support. For potential acquirers, the premium often sits in application expertise and verified feedstock access rather than basic molecule production.
Scenario planning — practical trajectories to use in 2026 planning
-
Base case (our central forecast): moderate growth consistent with market maturation and incremental new use-cases. Under this trajectory, prudent companies should secure multi-year supply arrangements for core volumes, prioritize cost-to-serve improvements, and invest selectively in formulation support to capture higher-margin niches.
-
Upside case: faster substitution in higher-value end-uses (e.g., specialty solvents and pharma intermediates) coupled with glycerol oversupply driving feedstock cost improvements. In this scenario, accelerated market share capture is feasible through investment in application development teams and targeted M&A to add formulation IP.
-
Downside case: feedstock constraints, regulatory tightening, or significant new entrants compressing margins. Here, focus shifts to flexibility—alternative feedstock qualification, dual-sourcing strategies, and short-cycle product innovation to preserve margin.
Concrete recommendations for 2026 (0–36 months)
-
Immediate (0–12 months): perform a supplier stress-test using our supplier scorecard; secure hybrid contracts (fixed-volume + index-linked tranche) to stabilize costs while retaining upside flexibility; and validate supplier sustainability claims through third-party audits or certification evidence.
-
Near term (12–24 months): invest in formulation engineering to expand into adjacent premium applications, and consider strategic equity or supply partnerships with suppliers that control renewable glycerin streams.
-
Medium term (24–36 months): if pursuing M&A, prioritize targets with strong application IP and verified feedstock access rather than pure-play volume assets; integrate regulatory monitoring into product launch gates to avoid late-stage rework.
Risk matrix — what keeps boards awake
-
Regulatory surprises: tighter classification or transport restrictions can add compliance costs and restrict certain end-uses; ongoing monitoring and contingency labeling budgets are essential.
-
Feedstock volatility: dependence on biodiesel-linked glycerol creates exposure to biofuel policy swings and agricultural cycles; diversification or secured feedstock contracts mitigate this.
-
Concentration risk: reliance on a few suppliers risks supply interruption; diversification strategies and contractual protections should be built into procurement playbooks.
-
Substitution and disruptive chemistries: advances in green solvent technology could reconfigure end-use economics—active scanning of adjacent chemistries is required.
How PW Consulting helps — the practical next step
-
The full Solketal market report provides the proprietary, downloadable market model, supplier scorecards, and the granular segmentation tables we intentionally omit here. It also contains interactive scenario worksheets that let clients re-run the forecast using custom input assumptions for feedstock cost, offtake timing and regulatory outcomes.
-
For 2026, our most requested engagements are: (1) rapid supplier due diligence and contract renegotiation support; (2) go‑to‑market and licensing strategies for manufacturers seeking to move up the value curve; and (3) M&A target screening with a seven-point integration checklist specific to specialty solvent assets.
Final note: this preview provides the strategic rationale, high-level market trajectory and decision frameworks you need to orient 2026 plans. For the detailed, transaction‑grade tables, per-region and per-application splits, supplier-level volume data, and the interactive forecast workbook—access the full PW Consulting Solketal report. The granular intelligence there converts the strategic imperatives outlined above into executable workplans tailored to your risk posture, supply commitments and growth ambition.
Selected source signals referenced in this preview: supplier public brand materials (e.g., Solvay’s Augeo portfolio), supplier disclosures on renewable glycerin feedstocks, and supplier statements on classification/labeling compliance. In the full report we annotate every supplier claim to primary sources and provide verification status for each statement used in our model.
For detailed analysis of this topic, please visit the official page: Solketal (CAS 100-79-8) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com