

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hepatitis A Vaccine Market Poised for 11.6% CAGR (2026–2032) — PW Consulting

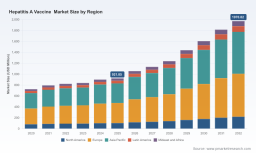
Hepatitis A Vaccine Market 2026: Strategic Snapshot for Executive Decision-Making
As governments, manufacturers, and procurement bodies recalibrate immunization priorities in a post-pandemic landscape, Hepatitis A vaccine demand is entering a phase of accelerated expansion and re‑pricing. PW Consulting’s latest market study — grounded in a 2025 base year and a 2026–2032 forecast window — quantifies that trajectory and translates it into actionable strategy for 2026 decision cycles. This preview outlines the high‑level market dynamics, competitive topology, and the practical levers executives must consider, while reserving the full segment-level intelligence for report subscribers.
Hepatitis A Vaccine Market
Why this research matters for 2026 decisions
Two operational realities make 2026 pivotal. First, our modelling shows the global Hepatitis A vaccine market passing a pronounced inflection point in the first forecast year (2026) and sustaining a robust compound annual growth rate (CAGR) of 11.59% through 2032. In numeric terms, the market base measured in 2025 and the projected market size by 2032 make clear that the sector is on track to roughly double in scale within the forecast horizon. Second, shifting public health guidance and procurement modalities are changing who buys, how they buy, and what suppliers can sustainably deliver. The intersection of these trends generates concentrated windows for product launches, contract wins, manufacturing investments, and strategic M&A in 2026.
Hepatitis A Vaccine Market
Market trajectory: growth, scale and concentration
-
Scale and momentum: From the historical series underlying our base-year assessment (2020–2025), the market has expanded steadily and enters 2026 at a materially higher run‑rate than five years prior. The forecast path through 2032 is characterized by accelerating absolute revenues and rising unit demand across multiple channels.
Hepatitis A Vaccine Market -
Market structure: The market exhibits a relatively high level of concentration — our concentration metrics show that the top three players control a dominant share, with the top five consolidating an even larger portion of the market. That structure creates durable advantages for incumbents but also creates targeted opportunities for challengers with differentiated technology, cost or geographic access.
-
Implication: Buyers and investors should treat Hepatitis A as a growth market with competitive scarcity — planning horizons must prioritize supply security and scalable production capacity.
Demand drivers and policy shifts
-
Policy recalibration: Public health bodies have adjusted Hepatitis A vaccination recommendations in response to shifting epidemiology and budget priorities. Notably, as of January 2026, certain major advisory bodies have focused routine recommendations toward higher‑risk cohorts or shared decision‑making models rather than universal childhood schedules. That policy pivot compresses some traditional demand channels while enlarging opportunities in targeted adult and travel/occupational vaccination programs.
-
Programmatic funding and procurement evolution: Donor programs, sovereign tenders and middle‑income market procurement strategies are increasingly sophisticated—favoring suppliers that can demonstrate stable long‑term supply, regulatory acceptance (including WHO prequalification where applicable), and capacity for bundled supply across vaccine portfolios.
-
Private‑sector dynamics: Private immunization demand remains a significant and often higher‑margin component of overall volumes, but is sensitive to pricing transparency and list‑price versus contract price differentials. The resulting commercial dynamics place premium value on tender intelligence, tiered pricing strategies and commercial contracting expertise.
Supply-side landscape and competitive positioning
The competitive map is anchored by established vaccine manufacturers with globally deployed Hepatitis A products and varying configurations (single-antigen and combination vaccines). In our assessment, incumbent manufacturers maintain entrenched positions through long-standing programmatic supply, regulatory dossiers and global commercial footprints — yet the field is not static.
-
Global incumbents: Manufacturers with legacy Hepatitis A brands continue to supply the majority of institutional programs and private markets. Their advantages include brand recognition, pediatric and adult formulations, and regulatory approvals across multiple jurisdictions.
-
Regional champions: Companies that secured early regulatory recognition in key emerging markets — and those with WHO prequalification — are converting regional dominance into international supply contracts. Recent contract activity underscores this trend.
-
2026 developments to watch: In early 2026 a leading Chinese manufacturer secured an exclusive public‑sector supply contract in a Middle Eastern market for 2026–2027, highlighting how regionally credible suppliers are penetrating public programs. Meanwhile, a major European vaccine manufacturer received renewed regulatory approvals in mid‑2026 for both its monovalent Hepatitis A product and a combined Hepatitis A/B formulation — events that will influence product eligibility in tenders and private markets.
-
Implication: For suppliers and buyers alike, 2026 is a year for structural plays — either to shore up market access via regulatory lifecycle management and supply agreements, or to pursue tactical wins where incumbents face manufacturing or contractual bottlenecks.
Pricing, procurement and risk
-
Price dispersion: The market exhibits meaningful dispersion between public contract levels and private list prices. This gap creates both arbitrage and risk: procurers can realize savings through centralized contracting, but suppliers face margin pressure unless they capture volume and cost improvements.
-
Procurement sophistication: Buyers increasingly use multi‑year agreements, capacity reservation clauses and performance‑based penalties to ensure supply continuity. Advanced purchasers are also integrating supply‑chain resilience metrics into contract evaluation, such as dual‑sourcing thresholds and inventory buffers.
-
Manufacturing and regulatory risk: Single‑source production lines and legacy facilities remain vulnerability points. Regulatory approvals, including updates to product labels and combination vaccine dossiers, materially affect manufacturer competitiveness — as demonstrated by the mid‑2026 regulatory update for a major manufacturer in our coverage universe.
What this means for strategic choices in 2026
Executives must move beyond tactical tender responses and adopt an integrated, 24‑month playbook that aligns commercial, regulatory and manufacturing levers. Key imperatives include:
-
Supply security first: Secure multi‑year contracts with clearly defined delivery windows and fail‑over options; where feasible, invest in contract clauses that enable on‑shoring or third‑party fill‑finish partners to reduce disruption risk.
-
Portfolio sequencing: For manufacturers, prioritize regulatory filings (including combination formulations and label extensions) that unlock large programmatic buyers; similarly, buyers should map licensure timelines into procurement windows to capture favorable competition.
-
Pricing telemetry and segmentation: Build models that incorporate public contract dynamics and private market elasticity to optimize price points by channel and geography. Price alone is not the sole determinant; delivery reliability and regulatory coverage often tip procurement decisions.
-
Partnerships and M&A: Identify inorganic targets that deliver either capacity expansion or strategic market entry — particularly suppliers with WHO prequalification and proven public‑sector contracting experience.
-
Evidence and advocacy: Fund real‑world evidence generation that demonstrates vaccine performance in adult and special‑risk cohorts to influence policy direction and expand eligible populations in countries re‑assessing routine recommendations.
What PW Consulting’s full report delivers (practical, operational content)
The full study is designed as an operational guide for 2026 execution. Subscribers will gain:
-
Detailed market sizing and forecast tables (2020–2032) with scenario runs and sensitivity cases;
-
Country‑level tender calendars and a heatmap of procurement risk across priority markets;
-
Competitive battlecards for the leading manufacturers, including regulatory status, product portfolios, manufacturing footprints and contract position estimates;
-
Procurement playbooks and tender evaluation templates that align with buyer objectives (cost, supply security, and regulatory coverage);
-
Price‑elasticity and margin models to stress‑test commercial strategies without exposing confidential contract details in this preview;
-
Manufacturing capacity maps, recommended de‑risking actions, and M&A target screening criteria;
-
Actionable go‑to‑market roadmaps for new entrants and disruption scenarios for incumbents.
These deliverables translate market projections and qualitative intelligence into time‑bound actions for 2026 — from boardroom investment decisions to tender response playbooks and regulatory prioritization.
Quick strategic checklist for leaders preparing 2026 plans
-
Confirm capacity commitments and establish alternative fill‑finish agreements where possible.
-
Run scenario planning against our base forecast and upside/downside cases to stress capital allocation decisions.
-
Prioritize regulatory filings that unlock the largest institutional buyers in your target markets.
-
Negotiate multi‑year agreements with price review mechanisms tied to CPI and raw material indices.
-
Operationalize real‑world evidence initiatives to influence shared‑decision policy shifts and expand addressable populations.
Conclusion — why the 2026 window is decisive
Hepatitis A vaccines are moving from steady demand into a phase of accelerated commercial activity and strategic repositioning. The combination of a strong underlying CAGR, concentrated supplier positions, regulatory updates and differentiated procurement approaches makes 2026 the year to lock in supply and to realign portfolios. PW Consulting’s full report provides the granular segment intelligence, tender‑level insights and executable templates that senior teams need to translate market growth into competitive advantage — while preserving the discreet data that underpins confident contracting and capital deployment.
To access the comprehensive datasets, market maps and operational playbooks referenced in this preview, consult the full Hepatitis A Vaccine Market report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Hepatitis A Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com