

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mobile Photo Printer Market Poised for 7.6% CAGR Through 2032

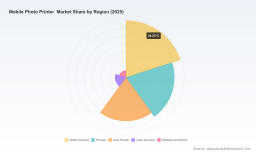
Mobile Photo Printer Market — Strategic Outlook and Decision Playbook for 2026
As senior strategy advisor and lead industry analyst at PW Consulting, I present a concise yet substantive preview of our newest Mobile Photo Printer Market research — a practical briefing crafted to inform board-level choices and commercial plans in 2026. This is a “trailer” of the full study: we surface the analytical approach, the actionable implications and the competitive dynamics you must internalize now, while reserving the granular segment tables and proprietary model outputs for the full report.
Mobile Photo Printer Market
Market snapshot: a recovery story that requires calibrated strategy
The market shows a distinct inflection as it moves out of the 2020–2025 period and into our 2026–2032 forecast window. After a period of volatility in the early 2020s, our base year for analysis is 2025. The market is projected to reaccelerate from 2026 onward at a compound annual growth rate (CAGR) of 7.6% over the 2026–2032 forecast period, reaching materially higher revenue by 2032. This trajectory reflects a compound of product refresh cycles, renewed consumer interest in printed keepsakes, and growth in event- and brand-driven use cases where physical prints enhance engagement.
Mobile Photo Printer Market
Two facts underpin this shape: (1) the near-term trough and subsequent rebound are driven less by a structural decline in demand for physical prints than by a combination of supply-side shocks (consumables and component cost pressure), regulatory adjustments around chemistry and recyclable materials, and a rebalancing of distribution channels; and (2) the long-term growth engine is a renewed monetization path that combines hardware upgrades with recurring consumables and digital value-added services.
Mobile Photo Printer Market
Why this report matters for 2026 decision-making
- Alignment of portfolio investments: the market’s post-2025 acceleration demands selective R&D and SKU rationalization — knowing where to invest (pocket vs. compact vs. novelty formats) is decisive for margin impact.
- Go-to-market timing: product introductions and channel campaigns in 2026 should anticipate a rising consumables cycle and leverage renewed retail traffic and experience-driven events.
- Supply chain and procurement playbook: rising paper roll and specialty component costs, coupled with geopolitical tariff pressure on assemblies, require renegotiated contracts and alternate-sourcing roadmaps now rather than later.
- Sustainability and regulatory compliance: shifting chemical rules and packaging mandates in major markets convert into both compliance costs and competitive differentiators; early movers capture brand premium.
- M&A and partnership screening: the market concentration metrics indicate a field dominated by a few large incumbents, creating openings for bolt-on acquisitions that complement software, consumables or niche form factors.
Competitive landscape — what the leading vendors signal
Market concentration is meaningful: the top three firms control a dominant share, and the top five extend that dominance substantially. This structure drives three practical realities for competitors and investors: (a) incumbents set pricing and channel norms, (b) scale matters for consumables distribution and service networks, and (c) differentiation increasingly comes from ecosystem plays (apps, consumables subscriptions, and event integrations) rather than hardware specs alone.
- Fujifilm Holdings (Japan) — Known for the instax mini Link line, Fujifilm continues to invest in app feature sets and product refinement. A January 2026 launch refreshed their smartphone printer experience, underscoring a strategy that pairs tactile retro appeal with modern connectivity and software features.
- Canon Inc. (Japan) — Canon’s SELPHY and IVY series represent the compact dye-sublimation strategy: performance-focused devices optimized for print fidelity and simple wireless workflows. Canon’s strengths lie in image-processing heritage and channel reach in both retail and professional segments.
- HP Inc. (United States) — The Sprocket pocket printers exemplify a volume, lifestyle-oriented play. HP leverages broad consumer brand recognition and global distribution to push lower-price, high-turnover units and consumables bundles.
- Kodak (United States) — Kodak’s STEP and Mini series straddle the thermal and dye-sublimation approaches. Kodak’s brand equity in instant imaging and licensing opportunities (nostalgia & co-branding) produces unique marketing plays even for smaller device players.
- Polaroid (United States) — Polaroid has doubled down on portable Bluetooth printers with a clear focus on brand-driven experiences and premium consumables, aiming to capture lifestyle-oriented buyers.
- Seiko Epson (Japan) — Epson’s portable lines emphasize reliable print mechanics and integration with professional imaging workflows; their supply chain scale and component know-how are differentiators for B2B and hybrid propositions.
- Phomemo (China) — As a price-competitive and fast-innovation manufacturer, Phomemo’s mini thermal printers and sticker formats illustrate how modular, low-cost manufacturing can capture niche and emerging markets rapidly.
Across incumbents and challengers, we observe a bifurcation: established imaging manufacturers pursue premium, service-linked experiences, while nimble entrants compete on cost, novelty formats and rapid channel experimentation.
Industry dynamics: regulatory, supply and materials risk
- Regulation & sustainability: Stricter regulations on photo-chemical composition and packaging in key markets are pushing suppliers toward water-based inks, recyclable substrates and reduced hazardous waste footprints. These are not only compliance issues; they shape procurement, partner selection and R&D priorities.
- Consumables pressure: Paper roll and specialty substrate costs have experienced upward pressure due to raw material availability and logistics. This amplifies the profitability importance of consumables subscriptions and vertical integration options.
- Standards & safety: ISO standards for electronics and batteries apply and will become gating factors for entry into certain retail and travel channels; design cycles should integrate certification timelines early.
- Geopolitical & tariff risk: Tariff actions on electronic assemblies in some import markets have material effects on landed costs. Manufacturers that diversify assembly footprints or localize critical components will be less exposed to periodic tariff shocks.
What PW Consulting’s full report delivers (action-oriented)
This study is built to be operationally actionable for executive teams. Highlights of deliverables include:
- Proprietary market model (2020–2032) with downloadable scenarios: baseline, accelerated-adoption and downside stress cases — allowing you to run custom inputs for pricing, channel shifts and consumables margins.
- Consolidated vendor benchmarking: capability scorecards across product, software, channel, service and sustainability for the leading suppliers, plus a shortlist of high-potential challengers and OEM/manufacturing partners.
- Commercial playbooks: three modular go-to-market templates (consumer-lifestyle, event-experience, and B2B/passport/identity niches) with sample P&L levers, channel commission frameworks and promotional calendars for 12–24 months.
- Supply chain and sourcing playbook: a supplier-risk heatmap, cost-driver decomposition for consumables, and tactical contract clauses to mitigate tariff and raw-material shocks.
- Product roadmap and feature prioritization matrix: a discrete decision framework to rank R&D investments in print fidelity, app features, battery life, and sustainable consumables based on ROI and competitive defensibility.
- M&A and partnership screening tool: a short-list of archetypal targets and a valuation framework for bolt-on acquisitions (software, consumables, last-mile distribution), plus integration risk checklists.
- Regulatory compliance tracker and sustainability roadmap: prioritized technical changes to meet near-term chemical and packaging regulations and a three-step plan to monetize sustainability claims.
We intentionally avoid listing the confidential segment-level revenue tables here. The full report contains the precise regional, type and application splits, together with elasticity coefficients and break-even analyses for new product SKUs — critical inputs for capital allocation and commercial rollout plans.
Practical strategic recommendations for 2026
- Prioritize consumables strategy: Negotiate multi-year supply agreements for paper and specialized substrates; pilot a subscription model in two pilot markets and run A/B tests on bundling tactics.
- Invest in rapid-certification and sustainable materials: Reallocate a portion of R&D spend to water-based inks and recyclable packaging to capture early-mover pricing and avoid future compliance costs.
- Differentiate through software and experiences: Bundle app features, AR overlays and event-integration APIs to drive higher attach rates for consumables and increase customer lifetime value.
- De-risk assembly and components: Establish alternative assembly partners outside tariff-exposed corridors and evaluate partial nearshoring for key subassemblies.
- Revisit pricing and channel economics: The rebound in demand requires dynamic pricing models — pilots should measure elasticity by channel and product tier to optimize mix for margin recovery.
- Scan for M&A that fills capability gaps: Targeted acquisitions that add software, subscription fulfillment capacity, or regional consumable distribution can deliver quick scale efficiencies in a concentrated market.
How to use this analysis
Board members and product leaders should use the findings to: (1) set realistic 2026 investment envelopes informed by scenario-driven demand curves, (2) align procurement and certification roadmaps with launch timetables, and (3) prioritize initiatives that create recurring revenue alongside hardware refresh cycles.
Commercial teams should deploy the playbooks and vendor scorecards to accelerate retail rollouts and test pricing bundles. Finance and corporate development teams will find the M&A screening and valuation frameworks immediately actionable for deal sourcing over the next 12 months.
Next steps — access the complete dataset and models
This introduction highlights the critical strategic lines you should act on in 2026. For executives who need to convert these themes into executable plans, the complete PW Consulting Mobile Photo Printer Market report provides the full datasets, segment-level forecasts, unit economics models and supplier scorecards referenced here. Visit our report page to download the full study, the interactive forecast model and the vendor benchmarking workbook — these contain the precise figures and operational templates that power confident investment and commercial choices.
At PW Consulting, we pair sector expertise with pragmatic tools — enabling you to turn a forecasted 7.6% CAGR and a clearly re-emerging market into a robust execution plan for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Mobile Photo Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com