

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Anti-Vibration Rubber Mounts Market: PW Consulting Forecasts 2.1% CAGR (2026–2032)

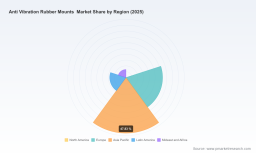
Anti Vibration Rubber Mounts Market — Strategic Outlook for 2026 Decision‑Making
Executive snapshot
As businesses prepare strategic plans for 2026, understanding the near‑term trajectory of the anti vibration rubber mounts market is non‑negotiable. PW Consulting’s latest market study benchmarks the sector across a full historical window (2020–2025) with a seven‑year forecast (2026–2032). At a macro level the market has shown steady expansion, registering a compound annual growth rate (CAGR) of 2.1% over the forecast period and reaching an estimated market size in the mid‑teens (USD Million) by the 2025 base year. By 2032 the market is projected to re‑approach the high‑teens (USD Million), reflecting modest but resilient demand driven by industrial replacement cycles, regulatory-driven retrofit programmes, and incremental growth in key OEM sectors.
Anti Vibration Rubber Mounts Market
Why this study matters for 2026 strategy
-
Actionable timing: 2026 is a pivot year for many buyers and suppliers — capex budgets, platform refresh cycles and regulatory audits converge. Our study converts those calendar pressures into strategic windows for procurement, product launches, and M&A.
Anti Vibration Rubber Mounts Market -
Risk calibration: with primary materials and feedstock exposed to commodity swings, near‑term cost volatility and sourcing concentration are core risks. The report quantifies these exposures and models scenario P&L impacts for OEMs and tier suppliers.
Anti Vibration Rubber Mounts Market -
Competitive posture: the market’s competitive footprint is moderately fragmented; the top three and five players account for a minority share of industry revenue, indicating scope for consolidation, focused differentiation and niche leadership plays.
Market dynamics — what is driving outcomes into 2026
-
Replacement and retrofit demand: Across heavy industrial and transportation sectors, existing installations are entering mid‑life service cycles, creating predictable replacement volumes. These steady aftermarket flows underpin a low‑double digit basis for suppliers even as OEM project wins fluctuate.
-
Material cost sensitivity: Natural rubber and synthetic rubber feedstocks remain a primary cost driver. In 2026 natural rubber price oscillation and quarterly volatility were material considerations for pricing strategy. Synthetic feedstock costs continue to track crude oil movements, and a significant proportion of manufacturers report supply cost instability — a dynamic that amplifies margin pressure for vertically integrated producers and contract manufacturers alike.
-
Regulation and certification as market gates: Certifications and industry standards (railway, aerospace and environmental management certifications among others) are practical entry barriers in several end markets. Firms that can demonstrate IRIS, EN 9100, ISO and ASTM alignment often gain privileged access to procurement lists and long‑term contracts.
-
Technology in product development: Simulation and AI‑enabled design platforms are accelerating time‑to‑validation for complex isolators. The adoption of advanced CAE platforms by leading component manufacturers is shortening design cycles for bespoke solutions — an advantage for suppliers seeking OEM co‑design engagements.
Competitive landscape — who to watch in 2026
The market is served by a mix of specialised independents and multinational engineering groups. Several players consistently feature in strategic dialogues for customers and investors:
-
GMT Rubber‑Metal‑Technic Ltd (UK) — strong in bonded rubber‑to‑metal solutions across rail, defence and aerospace, with established certifications that support regulated contracts.
-
Polymax Ltd (India/UK) — high SKU breadth and bespoke manufacturing capabilities, positioned for rapid fulfilment and custom designs.
-
AV Industrial Products Ltd (UK) — known for bespoke hydro and cone mounts tailored to off‑highway and marine customers.
-
Trelleborg AB (Sweden) — global engineering reach with comprehensive anti‑vibration portfolios and materials engineering scale.
-
Dynemech Systems, Vibrasystems, Minor Rubber Company and regional manufacturers such as Delta Rubber — these firms provide critical regional capacity, specialised product ranges and aftermarket service footprints.
Recent strategic moves underline two forces shaping competition in 2026: technology adoption and geographic footprint expansion. Examples include large OEMs and system suppliers adopting simulation platforms to accelerate design validation, and acquisitive moves to consolidate regional capability and access end‑market clients.
Supply chain and cost considerations for procurement and manufacturing
-
Raw material volatility: Natural rubber exhibited meaningful intra‑year fluctuation; buyers should expect periodic cost pass‑through negotiations and consider hedging or alternative compound specifications where feasible.
-
Feedstock sensitivity to oil markets: Synthetic rubber components remain exposed to crude price corridors. Purchasing strategies that blend natural and synthetic inputs, or that secure longer‑term contracts with indexation clauses, mitigate short‑term margin shocks.
-
Certification and supply continuity: Suppliers holding key certifications and diversified production footprints demonstrate higher resilience in regulated tenders and in events of supply chain disruption.
What the PW Consulting report contains — operational value for 2026
Recognising that executives need precise, executable intelligence rather than academic summaries, our study delivers practitioner‑level outputs designed for boardroom and procurement teams:
-
Methodology and verified market sizing: transparent modelling assumptions for historical and forecast windows, with sensitivity cases for commodity shocks and demand shifts.
-
Segment and channel playbooks: end‑use, product‑type and distribution channel analysis that translate into go‑to‑market recommendations, pricing tactics and customer segmentation frameworks. (Note: detailed segment revenue tables are available in the full report.)
-
Supplier scorecards: capability matrices and certification audits that support supplier selection, dual‑sourcing plans and qualification roadmaps.
-
Price modelling tools: scenario templates that map raw material price paths to component costs and margin outcomes—suitable for procurement negotiation and financial planning.
-
M&A and investment thesis: target archetypes, valuation levers and integration risks for buyers seeking inorganic scale or capability fills in 2026.
-
Commercial playbooks: product launch timing, specification trade‑offs (cost vs. performance), and case studies showing successful OEM co‑development tracks.
Strategic recommendations for 2026 leaders
-
Prioritise certification and quality evidence in bidding: for players targeting regulated sectors, fast‑tracking certifications or making transparent compliance commitments materially improves win rates.
-
Lock flexible supply arrangements: pursue hybrid contracts (short‑term buy + long‑term indexed agreements) to manage cost volatility while preserving supply security.
-
Invest selectively in simulation and digital validation: adopting or partnering for advanced design tools reduces prototype cycles and accelerates customer qualification, a differentiator in competitive OEM projects.
-
Explore bolt‑on M&A in regional markets: given the market’s moderate fragmentation, targeted acquisitions can quickly expand geographic access and aftermarket service capabilities.
-
Design modular product families: modularity reduces SKU proliferation for contract manufacturers while enabling OEMs to offer differentiated specifications without large NPI costs.
Use cases where the report is immediately applicable
-
Procurement teams preparing 2026 supplier RFQs and hedging strategies will find the price modelling and supplier scorecards directly implementable.
-
Corporate development teams evaluating bolt‑on acquisitions or partnership targets will benefit from the M&A thesis and target archetype framework.
-
R&D and product managers preparing OEM tenders can use the simulation adoption benchmark and go‑to‑market playbooks to de‑risk development timelines.
Closing — what to expect next
The anti vibration rubber mounts market entering 2026 is one of steady, structural demand with episodic cost and supply shocks. Strategic winners will be those who translate market visibility into procurement resilience, certification‑led market access and technology‑enabled product differentiation. PW Consulting’s full study provides the granular segment economics, regional breakdowns, and model files that underpin the executive recommendations summarized here — curated so your leadership team can execute confidently in 2026 and beyond.
To access the full datasets, proprietary segmentation tables, and downloadable scenario models, refer to the complete PW Consulting report and supporting materials.
For detailed analysis of this topic, please visit the official page: Anti Vibration Rubber Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com