

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gear Cutting Machines Market to Reach USD 344.8M by 2032 at 6.98% CAGR

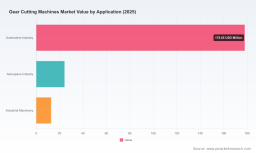
Gear Cutting Machines Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of the Gear Cutting Machines market designed to inform capital allocation, product strategy, and supply-chain choices through 2026 and beyond. This briefing highlights the macro trajectory, strategic inflection points, competitive dynamics, and the practical intelligence that our full study delivers — while preserving the granular segmentation and proprietary datasets that subscribers use for procurement, M&A, and plant‑level retrofit decisions.
Gear Cutting Machines Market
Market snapshot: a durable expansion anchored in modernization
At the macro level, the Gear Cutting Machines market has shown steady expansion through the recent half‑decade and is entering a phase of accelerated modernization. Using 2025 as the analytical base year, the market grew from approximately USD 163 million in 2020 to roughly USD 215 million in 2025. Under the baseline forecasting scenario, the market is projected to continue on a compound annual growth rate of 6.98% across the 2026–2032 horizon, reaching roughly USD 345 million by 2032.
Gear Cutting Machines Market
Those headline numbers reflect two concurrent forces: a sustained replacement and capacity‑build cycle in mature metal‑forming industries, and a faster‑moving upgrade dynamic driven by energy‑efficiency imperatives, automation integration, and an expanding set of high‑precision applications (notably in electrified powertrains, aerospace, and advanced industrial equipment). For executives, the important implication is that capital deployed in 2026 will be evaluated against both near‑term productivity returns and multi‑year regulatory and energy savings that compound equipment ROI.
Gear Cutting Machines Market
Why this preview matters for 2026 decisions
- CapEx timing and sizing: With a market on a near‑7% CAGR, manufacturers face the classic trade‑off between early adoption to capture efficiency differentials and waiting for second‑generation smart tools. Our research frames the risk/reward curve for both greenfield capacity and targeted retrofit programs.
- Technology selection: Decisions between hobbing, shaping, shaving, skiving, and grinding workflows are no longer purely technical — they map to digitalization pathways, energy consumption profiles, and downstream finishing requirements. The report equips buyers with a decision matrix linking process choice to part complexity, tolerances, cycle time, and lifetime energy cost.
- Supply‑chain resilience: Long lead times for specialized spindles and high‑performance hobs, plus concentrated tooling inputs, mean procurement strategy drives delivery risk. Our analysis quantifies supplier concentration and proposes tactical sourcing options, including inventory buffers, second‑tier suppliers, and local service partnerships.
- Regulatory and cost pressure: Energy and building performance standards in key jurisdictions are shifting the operating model for precision machining shops — influencing not only the machine purchase decision but also layout, cooling systems, and waste‑heat recovery investments. The report models the impact of these regulations on TCO and payback periods.
Practical content included in the full study
The full PW Consulting study is constructed to be immediately usable by strategy teams, plant managers, and procurement officers. Highlights include:
- Executive dashboard with macro KPIs and scenario outputs for conservative, base, and aggressive adoption pathways;
- CapEx/TCO templates that model acquisition cost, energy consumption, tooling replacement, service contracts, and residual value over lifecycle horizons tailored to common use cases;
- Technology‑fit decision trees and process maps that translate product specifications and part tolerances into recommended machine classes and automation levels;
- Supplier evaluation framework combining technical capability, geographic footprint, aftermarket service metrics, and financial health to support vendor short‑lists;
- Regulatory impact matrix that quantifies likely compliance costs and identifies cost‑offsetting opportunities from energy‑efficient machines and process redesign;
- Use cases and case studies showing time‑to‑value from recent retrofit projects, including data on cycle time reductions, scrap rate improvements, and energy savings;
- Proprietary datasets and interactive charts (historical 2020–2025 and forecasts 2026–2032) enabling executives to drill from macro market sizing down to machine class and application scenarios.
Competitive landscape — what to watch in vendor strategy
The gear‑machining vendor space remains technologically rich and commercially competitive. Our competitive chapter profiles leaders and challengers, distilling implications for OEM buyers and aftermarket service partners. A few directional observations:
- Broad‑portfolio OEMs with system capabilities: European and North American manufacturers offering integrated gear production lines retain an advantage for customers who prioritize single‑supplier responsibility for cycle time optimization and quality assurance. Their value proposition is strongest where customers seek end‑to‑end capability for high‑volume or high‑precision production.
- Specialists and performance niches: Companies focused on particular machine types — such as high‑speed hobbing, super‑dry cutting, or bevel gear technologies — continue to win on technical performance and tooling ecosystems. For buyers, adopting niche technology can yield material productivity gains but requires careful aftermarket and tooling alignment.
- Service and aftermarket as differentiators: As machines become more software‑enabled and energy‑optimized, the ability of a supplier to provide rapid, data‑driven support and local spares determines long‑term uptime. This is where smaller, service‑oriented players can compete effectively against larger OEMs.
Representative firms profiled in the report include established gear‑machining names across Europe, North America, and Asia, each evaluated on machine portfolios, innovation pipeline, geographic service coverage, and recent market activity. The profiles are designed to help sourcing teams construct negotiations strategies that account for warranty structures, retrofit packages, and software/service bundling.
Recent industry signals shaping 2026 strategy
- Conferences and trade fairs: Global gear technology events in 2026 have accelerated exposure to new processes and live demonstrations. These venues are proving important for validating vendor claims and accelerating adoption of techniques such as skiving and advanced dry cutting.
- Tooling and materials: High‑performance hobs—manufactured from PM high‑speed steels and advanced powders with PVD coatings—are central to delivering longer tool life and improved surface integrity. Tooling suppliers now play a bigger role in the total cost equation than in the prior decade.
- Regulatory momentum: Energy efficiency standards and building performance codes in several industrial jurisdictions are translating into quantifiable plant‑level requirements, making energy metrics a first‑order selection criterion for new equipment.
- Exhibition activity: Leading OEMs are using major fairs to launch or showcase machine series optimized for dry cutting, higher automation, and integrated quality measurement — signaling the product directions that buyers should evaluate in 2026 purchasing cycles.
Key strategic implications and recommended actions for 2026
- Adopt a staged modernization approach: Prioritize retrofit of bottleneck cells and equipment that offer the fastest payback through energy savings and reduced downstream rework. Use the report’s TCO templates to validate vendor ROI claims.
- Sink or swim on digital enablement: Require potential suppliers to demonstrate data‑integration capabilities (MTConnect/OPC UA), predictive maintenance offerings, and clear KPIs for uptime and energy consumption as part of contract terms.
- Reassess procurement for resilience: Build dual‑sourcing strategies for critical spindles and hobs, and negotiate spare‑part consignment or local stocking agreements to reduce lead‑time exposure.
- Leverage incentives and compliance windows: Identify jurisdictional energy incentives and phase‑in periods for building codes to align machine purchases with grant and rebate opportunities, thereby improving net project economics.
Conclusion — the strategic value of the full PW Consulting study
For executive teams deciding on equipment spend, supplier selection, or M&A plays in 2026, the value of rigorous, actionable market intelligence cannot be overstated. This preview outlines the macro trajectory (base year 2025, forecast 2026–2032) and the structural dynamics that will determine winners and losers. The complete PW Consulting Gear Cutting Machines Market report supplies the proprietary segmentation, vendor scorecards, downloadable TCO models, and region‑specific scenarios that leaders use to convert market insight into confident capital and operational decisions.
To move from strategy to execution, access the full study for the detailed datasets, machine‑level comparisons, and step‑by‑step procurement playbooks that are intentionally excluded from this preview. Our research is designed to accelerate 2026 decision cycles — not to replace the supplier diligence and site‑level benchmarking that should follow.
For detailed analysis of this topic, please visit the official page: Gear Cutting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com