

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pentaerythritol Market to Hit USD 304.6M by 2032 at 5.15% CAGR

Pentaerythritol (CAS 115-77-5) Market — Strategic Imperatives for 2026
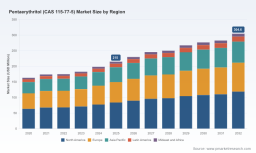
As companies reset priorities for 2026, the pentaerythritol value chain requires a fresh strategic lens. PW Consulting’s latest Pentaerythritol Market study (base year 2025, forecast 2026–2032) synthesizes a complex mix of demand resilience, concentrated supply, feedstock volatility and regulatory friction into an executable playbook. The market, which has expanded from the low hundreds of millions in 2020 to USD 215.0 Million in 2025, is projected to continue growing at a compound annual growth rate of 5.15% through 2032, reaching roughly USD 304.6 Million by the end of the forecast horizon. These headline dynamics deserve careful interpretation: steady aggregate growth masks significant regional, application and cost-driven fissures that will determine winners and losers in 2026 and beyond.
Pentaerythritol (CAS 115-77-5) Market
Why this study matters to corporate leaders in 2026
-
Capital allocation and capacity timing: The market’s mid-single-digit CAGR creates opportunities for selective capacity additions, but timing and location will determine margin recovery versus overcapacity risk.
Pentaerythritol (CAS 115-77-5) Market -
Commercial contracting and pricing strategy: With a market structure that is meaningfully consolidated at the top, price-setting power and contract design (indexation to feedstock, flex clauses) will be differentiators.
Pentaerythritol (CAS 115-77-5) Market -
Feedstock integration and procurement: Formaldehyde-linked cost swings remain the primary margin lever; procurement strategies and backward integration options must be stress-tested across realistic scenarios.
-
Sustainability and product differentiation: Renewable and ISCC-certified grades are emerging as commercial premiums — influencing offtake structures and customer segmentation.
-
Trade, tariff and regulatory planning: Recent tariff measures and HS-classification nuances have created new trade frictions that alter regional arbitrage economics.
Key market signals and what they imply
-
Resilient aggregate demand. Between 2020 and 2025 the market climbed from roughly USD 163 Million to USD 215 Million. That trajectory — and the forecast out to 2032 — shows a market with durable end-use demand despite episodic price variance.
-
Concentrated supplier structure. The market concentration ratio for the top three and top five producers indicates a landscape where a handful of players capture a substantial share of supply. That concentration creates both stability and strategic vulnerability: coordinated commercial behaviour becomes possible, but congestion around feedstock, logistics and regulatory approvals can quickly compress margins for marginal producers.
-
Feedstock risk dominantes costs. Formaldehyde is the single largest cost input and its volatility is the dominant short-term margin driver. Procurement strategies that ignore feedstock linkage expose producers to outsized earnings volatility.
-
Regulatory and trade noise is non-trivial. Recent duties and classification specificities have created new barriers to traditional trade flows and will shape near-term arbitrage and stock build behaviour.
Competitive landscape — leaders, challengers, and niche specialists
-
Large global producers with strategic upgrades: Established multinational producers have been active with strategic capacity moves and new product grades that target sustainability-conscious buyers. These companies combine global sourcing, branded specialty grades and technical service, which gives them leverage in high-value downstream segments.
-
Regional scale players in Asia: Several larger regional producers have been accelerating domestic investments and feedstock integration strategies to capture local demand and export opportunities. This creates a dual effect: intensified local competition and potential for export-led pricing pressure where logistics and duties allow.
-
Specialty and niche suppliers: A cohort of smaller specialty producers focuses on industrial or pharmaceutical-grade pentaerythritol and technical service. These players defend margins through formulation support, tighter service level agreements and localized supply assurance.
-
Strategic implications: For incumbents, the playbook is to protect margin via product differentiation (renewable/ISCC grades), secure feedstock access and optimize global footprint against tariff and shipping cost differentials. For entrants, niche focus, technical excellence and downstream partnerships offer the fastest path to commercial traction.
Recent industry developments that signal structural shifts
-
Capacity additions and technology upgrades have continued into 2024–2025, with recent plant starts and line launches positioned to capture demand in coatings, lubricants and higher-purity applications. These moves accelerate the push toward specialty grades and renewables.
-
Price volatility in late 2025 demonstrated how rapidly margins can swing; month-over-month volatility and notable year-over-year movements have been observed in key markets.
-
Policy interventions — including new import measures in specific markets introduced in 2024 — are already shaping trade patterns. Commercial and trade teams must incorporate these changes into route-to-market and sourcing strategies immediately.
Raw-material and regulatory levers you cannot ignore
-
Formaldehyde remains the critical input: it typically represents the single largest portion of operating cost and is therefore the primary exposure to monitor. Scenario modelling in our study quantifies P&L sensitivity across a range of formaldehyde price paths and feedstock supply disruptions.
-
Import duty regimes and HTS classifications materially alter landed economics. Companies should treat tariff announcements as strategic events — prompting immediate reviews of contract terms, hedging, and regional sourcing shifts.
-
Environmental and sustainability credentials (e.g., ISCC certification) are increasingly monetizable. Investment in renewable feedstock-compatible process routes is no longer only a compliance exercise — it is a revenue management decision.
Actionable 2026 playbook — recommended moves by function
-
Executive leadership: Re-run capital prioritization with three scenarios (soft, base, upside) for 2026–2028. Prioritize flexibility (brownfield debottlenecking vs large greenfield) and include contractual flex with offtakers.
-
Commercial teams: Renegotiate indexation clauses to formaldehyde benchmarks where possible, introduce rolling offtake options for strategic customers, and segment customers by willingness-to-pay for specialty/renewable grades.
-
Procurement: Implement layered hedging, secure alternative formaldehyde sources, and evaluate backward integration or long-term tolling partnerships to de-risk feedstock exposure.
-
M&A and business development: Target bolt-on acquisitions that provide feedstock integration, access to specialty grades or regional offtake. Smaller strategic acquisitions can be value-accretive faster than large greenfield projects.
-
R&D and sustainability: Fast-track product lines that capture premiums for renewable-certified pentaerythritol equivalents and invest in technical service capability to lock in premium channels (e.g., high-performance coatings, specialty lubricants).
What PW Consulting’s full study delivers (practical and actionable)
-
Reconciled market sizing and transparent forecast methodology covering 2020–2032, enabling board-level validation of market assumptions.
-
Demand-driver diagnostics by application with scenario-based volumetric models and elasticity sensitivities suitable for commercial planning.
-
Supply-side mapping and a granular, anonymized production roster that highlights capacity vintages, technology profiles and probable steam/energy intensity — indispensable for operations and investment teams.
-
Price modelling that links feedstock benchmarks, freight and duty permutations to producer margin outcomes under multiple macro scenarios.
-
Regulatory and trade impact assessment with action checklists for trade teams and procurement.
-
Deal and valuation guidance for M&A, including precedent transactions, valuation frameworks and integration risk matrices.
-
Ready-to-use executive summaries, slide decks and a downloadable data appendix to accelerate decision-making.
How to use this insight in Q1–Q2 2026
-
Embed the study’s scenarios into capital expenditure approvals and rolling three-year operating plans.
-
Use the supply mapping to stress-test existing offtake agreements and prioritize suppliers for renegotiation based on resilience and sustainability credentials.
-
Prioritize short-list M&A targets that offer feedstock security or high-margin specialty channels; run accelerated diligence that focuses on cash-flow resilience under feedstock stress tests.
-
Align commercial incentives with price realizations: create sales compensation that balances volume growth with margins on premium grades.
Closing — why Pentaerythritol is a timely strategic focus
Pentaerythritol sits at the intersection of traditional chemical commodity dynamics and emergent specialty value creation. Aggregate growth is steady and predictable at the market level; the real value for 2026 decision-makers lies in navigating feedstock volatility, regulatory shifts and the premiumization wave. PW Consulting’s study converts these macro forces into near-term operational priorities and medium-term strategic options. We surface where margins will be protected, where pricing pressure is likely, and which capability bets offer the highest return on invested capital — while preserving the detailed segmentation and unit-economics analysis behind our conclusions for clients who require the underlying datasets.
To access the full model, detailed segmentation, supplier-by-supplier maps and scenario-specific P&L impact tables, visit the report page or contact PW Consulting’s head of practice for the Pentaerythritol study. The executive summary above highlights what to act on now — the full study gives you the play-by-play to execute.
For detailed analysis of this topic, please visit the official page: Pentaerythritol (CAS 115-77-5) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com