

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Home Audio Equipment Market to Hit USD 47.99B by 2032 at 7.5% CAGR

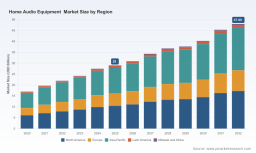
Home Audio Equipment Market — 2026 Strategic Outlook
PW Consulting’s latest Home Audio Equipment Market primer is written for senior leaders who must convert fast-moving market signals into high-confidence 2026 decisions. Built on a base year of 2025 and a detailed historical series from 2020–2025, our research projects the market forward through 2032 at a compound annual growth rate of 7.5%. That trajectory — from roughly USD 29 billion in 2025 to just under USD 48 billion by 2032 — creates both expansion opportunities and strategic inflection points for product, channel, and supply‑chain choices. This article explains the strategic value of the full study, teases its analytical depth, and outlines the practical actions executives should prioritize in 2026. (Note: the report contains full subsegment tables, proprietary scenario models, and granular regional breakdowns — these are intentionally omitted here to direct readers to the full report page.)
Home Audio Equipment Market
Why this research matters for 2026 corporate strategy
Two defining features shape decision-making in 2026: accelerating product convergence and heightened external risk. On the demand side, connectivity, immersive formats, and software-enabled user experiences are re-shaping customer value propositions. On the supply side, tighter controls on e‑waste exports and a renewed policy focus on critical minerals are changing sourcing economics and compliance costs. Our study synthesizes these forces into a single, decision‑ready narrative: the home audio market is large, growing at a steady mid‑single-digit CAGR, and strategically fragmented — meaning that well‑timed investments and partnerships can produce outsized returns if executed with operational and regulatory foresight.
Home Audio Equipment Market
What’s in the report — pragmatic, actionable content
- Forward-looking revenue and unit forecasts (2026–2032) by product family and connectivity architecture, built from bottom‑up adoption curves and top‑down macro scenarios.
- Scenario models that stress-test outcomes against three downside drivers: supply‑side mineral shocks, tightened e‑waste export controls, and a slower-than-expected smart‑home upgrade cycle.
- A competitive playbook with parallel benchmarking: R&D emphasis, software/firmware roadmaps, go‑to‑market strategies, and margin pressure points — enabling quick SWOT synthesis for potential targets.
- Channel and pricing archetypes, including promotional elasticity, subscription bundling levers, and trade vs. direct-to-consumer margin calculus.
- Supply‑chain risk heatmaps and a supplier segmentation matrix that quantify the operational impact of critical‑minerals constraints and export regulations.
- An M&A screening toolkit and integration checklist targeted to buyers hunting scale in software, services, or regional reach.
We present all of the above with the accompanying primary data tables, downloadable financial models, and a decision-scripting appendix to translate analytics into 90/180/360‑day action plans. To preserve the commercial value of those deliverables, detailed subsegment dollars and region/application percentages are accessible through the full report page.
Home Audio Equipment Market
Competitive landscape: who’s shaping the market and why it matters
The market remains strategically fragmented: the top three global players account for a modest share of industry revenue, and the top five only modestly more — a concentration profile that keeps both independent specialists and platform incumbents in play. The leading vendors exemplify divergent routes to growth.
- Bose Corporation — continuing to lean on premium hardware and differentiated audio engineering, Bose combines high‑value wireless speakers and integrated home‑theater systems with software and ANC leadership. For incumbents considering premium lines, Bose’s approach underscores the importance of sustained R&D and brand premiumization.
- Sonos Inc. — Sonos is the market poster child for multi‑room ecosystems and software‑driven value capture. Recent product introductions (including a next‑generation flagship soundbar and refreshed subwoofer and speaker models) reinforce a strategy that mixes product upgrades with platform control and services monetization.
- Harman/JBL — JBL’s deep pro-sound heritage has been translated into high‑power Bluetooth speakers and home theater systems that emphasize performance-to-price ratios. Their posture highlights the opportunity in value-dense audio products that pair mass-market distribution with credible performance claims.
- Klipsch — Klipsch emphasizes efficiency and acoustic design, increasingly coupling premium horn‑loaded speaker architecture with strategic partnerships for powered systems. Their collaboration patterns foreshadow one consolidation pathway: brand-led partnerships to accelerate product refresh cycles.
- Onkyo — Onkyo’s strength in AV receivers and multi‑channel amplification speaks to the enduring relevance of dedicated components for enthusiasts and premium home‑theater buyers. Refreshes announced at recent trade shows signal ongoing demand in higher‑end audio processing hardware.
Recent industry product and warranty moves matter beyond PR: extended warranty programs and collaborative product launches are becoming competitive differentiators. For example, extended warranties by specialist manufacturers and co‑branded hardware partnerships announced at major trade shows change the calculus on post‑sales cost and customer lifetime value — important inputs in our models and deal screens.
Material and regulatory dynamics that will shape supplier strategy
Two policy shifts merit particular attention in 2026 planning:
- As of January 1, 2025, revised Basel Convention practices put prior written consent requirements on international shipments of e‑waste and scrap. That rule raises compliance costs for cross‑border refurbishment, recycling, and downstream manufacturing flows.
- Critical‑minerals listings in 2025 included several materials widely used in audio manufacturing — specifically rare‑earth elements and mainstream semiconductors/raw materials. The presence of these inputs on formal lists increases geopolitical and supply‑chain risk and makes second‑source strategies and materials substitution high‑priority investments.
Operational responses embedded in the report include supplier dual‑sourcing playbooks, design‑for‑recyclability checklists, and a quantified total cost of ownership model that internal teams can use to evaluate nearshoring, vertical integration, or long‑term contracts with guaranteed offtake.
Key strategic imperatives for executives in 2026
- Prioritize software and product‑services: convert hardware buyers into recurring‑revenue customers through subscription services, calibration ecosystems, and firmware‑driven feature tiers.
- Elevate materials strategy: embed critical‑minerals exposure into every sourcing and capital decision, and accelerate design options that reduce reliance on at‑risk inputs.
- Use differentiated warranties and service offers as competitive weapons — longer warranties can justify price premiums but must be net‑modeled against service infrastructure costs.
- Look for M&A targets that add software control points or extend channel reach; in a moderately fragmented market, small bolt‑ons can materially improve gross margin profiles.
- Build export‑compliant refurbishment and recycling pathways now to avoid future disruptions tied to e‑waste controls.
- Tier assortments by connectivity and use‑case: while wireless and smart features are growth drivers, dedicated high‑fidelity hardware still merits investment as a margin anchor.
- Stress‑test pricing under three scenarios in your P&L: base case (steady growth), premiumization acceleration, and a materials‑driven cost shock.
How to use the PW Consulting report to make 2026 choices
Executives approaching 2026 with budget authority will find three immediate uses for our dataset and tools:
- Investment screening: use the included M&A scoring model to compare targets on revenue synergies, product overlap, and integration cost against projected CAGR-driven growth lanes.
- Product roadmapping: align R&D spend with forecasted demand buckets and the report’s adoption curves; accelerate features that support subscription and ecosystem lock‑in.
- Supply‑chain playbooks: apply the supplier risk heatmap and total‑cost model to decide between nearshoring, long‑term contracts, or inventory hedges for critical components.
Each deliverable is accompanied by an executive one‑pager summarizing the strategic implications and a recommended 90‑day action plan for leadership — enabling rapid alignment between strategy teams and operating units.
Conclusion and next step
The home audio market’s steady mid‑single‑digit growth creates an environment where strategic clarity — not guesswork — separates winners from the rest. PW Consulting’s Home Audio Equipment Market report blends scenario‑based forecasting, hands‑on competitive intelligence, and operationally realistic playbooks designed for immediate execution in 2026. If your team needs the granular revenue models, product‑level elasticities, and regional channel projections that guide capital allocation and M&A choices, the full report and interactive model are available at our report page. Contact PW Consulting’s market practice to schedule a walk‑through and tailored brief for your board or investment committee.
For detailed analysis of this topic, please visit the official page: Home Audio Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com