

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Gallic Acid Market to Reach $348M by 2032 at 6.8% CAGR
By pmarketresearch, 2026-07-13
Gallic Acid (CAS 149-91-7) Market — 2026 Strategic Preview
As firms set 2026 priorities against an increasingly volatile raw-material and regulatory backdrop, Gallic Acid has emerged from a niche reagent into a strategically relevant ingredient across food & beverage, pharmaceutical, and personal care value chains. PW Consulting’s latest study (base year 2025) models the market as a structurally growing opportunity: the addressable global market expands from a 2025 baseline of USD 219.6 Million to an anticipated USD 348.04 Million by 2032, reflecting a compound annual growth rate of 6.8% across the 2026–2032 forecast window. This preview synthesizes the report’s high-level implications for corporate decision‑makers in 2026 — demonstrating the type of analytical depth contained in the full publication while reserving the granular segmentation tables that drive transactional action.
Gallic Acid (CAS 149-91-7) Market
Why this market matters to 2026 strategy
-
Cross-sector demand maturation: Gallic Acid’s role has broadened from laboratory reagent to multifunctional ingredient — an antioxidant, preservative, intermediate for API development, and formulation aid in cosmetics. This cross-sector adoption moderates cyclicality but also raises exposure to diverse regulatory regimes and quality expectations.
Gallic Acid (CAS 149-91-7) Market -
Sourcing risk and price elasticity: Production remains anchored in agricultural-derived feedstocks (e.g., tara pods, gallnuts, sumac), so availability and cost are sensitive to climatic variability and crop yields. Suppliers that can de-risk feedstock pipelines or offer vertically integrated bioproduction models will command strategic advantage.
Gallic Acid (CAS 149-91-7) Market -
Standards-driven segmentation: Demand bifurcates by quality and certification requirements — commodity industrial supply versus USP/EP pharmaceutical grades and certified reference materials for analytical use. Quality premiums and buyer willingness to pay vary significantly by application.
-
Consolidation and concentration: Market concentration is meaningful — the top three players collectively control a substantial portion of supply, with the top five exerting an even larger share. This concentration shapes negotiation dynamics and validates both defensive and acquisitive strategies for mid‑sized suppliers and purchasers.
What PW Consulting’s full study delivers (practical components)
-
Proprietary demand model (2020–2032): scenario-ready projections by application class and end-use verticals, designed to be plugged into capex and procurement planning tools.
-
Supplier landscape and heatmap: verified production capacities, ISO/USP/EP certification status, geographic footprint, and export lanes — accompanied by a supplier scorecard that rates technical competence, compliance risk, and commercial responsiveness.
-
Price and margin framework: mechanistic drivers linking feedstock cost shocks, conversion yields, and contract structures to finished-product price trajectories under multiple market stress scenarios.
-
Regulatory and quality playbook: a checklist and implementation roadmap for meeting pharmaceutical (USP/EP) and food-safety requirements, including documentation, audits, and analytical benchmarks.
-
Go-to-market playbooks for suppliers and buyers: differentiated strategies for industrial, food & beverage, pharmaceutical, and cosmetic customers, with tailored channel, pricing and certification recommendations.
-
M&A and partnership scanner: valuation heuristics, integration risks, and target profiles for bolt-on acquisitions or technology partnerships (e.g., fermentation/bioprocessing) to secure predictable supply and higher margins.
-
Executive dashboards and procurement templates: condensed KPIs for quarterly decision cycles, supplier scorecards, and stress-test scenarios for negotiation and contingency planning.
Supply-side dynamics: risks, defensive moves, and innovation
Raw-material volatility remains the dominant near-term supply risk. Where historical suppliers lean on agricultural feedstocks, atypical weather patterns materially affect both availability and unit economics. In response, we see two structural responses emerging: (1) vertical integration and onshoring of key production steps, and (2) investment in bioprocess routes that decouple production from seasonal feedstock flows.
Merck KGaA’s January 2024 non-binding memorandum with Mycenax Biotech is emblematic of the second response: strategic partnerships that target bioprocess scaling and lifecycle control for life-science ingredients. Companies with R&D capacity and downstream quality systems that can deliver USP/EP-compliant material through either traditional extraction or fermentation will be advantaged — both in price stability and in premium markets that prize traceability and reproducibility.
For buyers, defensive sourcing strategies should prioritize supplier diversification across production technologies and regions, dual-sourcing contracts with pre-negotiated price bands, and working-capital structures that absorb seasonality without passing unnecessary cost to end markets.
Demand-side trends and customer segmentation
End users are not homogeneous. Food & beverage formulators increasingly demand “clean‑label” natural antioxidants, favoring suppliers with verifiable traceability and sustainability claims. Pharmaceutical purchasers, by contrast, prioritize compliance and batch-to-batch reproducibility, creating a high-margin niche for USP/EP‑certified producers. Academic and industrial research demand continues to support a parallel market for certified reference materials and high‑purity grades used in analytical contexts.
Strategic takeaway for 2026: segment your customer outreach and pricing strategy to reflect the distinct willingness-to-pay and compliance burdens of each buyer cohort. Investments in certifications and batch-release analytics will pay dividends in regulated channels, while cost-to-serve optimization remains critical for high-volume industrial purchasers.
Competitive landscape — tactical implications
-
Merck KGaA / Sigma-Aldrich: A vertically integrated, reputation‑led supplier focusing on pharmaceutical-grade material and certified reference standards. Their scope and certification depth make them the go-to for regulated buyers; competitors should not attempt to win those accounts on price alone but can target responsiveness, bespoke supply agreements, and local warehousing as differentiators.
-
Gallochem Co., Ltd. & TNJ Chemical: Represent cost-competitive, scale-driven supply from China, targeting food, beverage and industrial applications. These suppliers compete on price and availability; buyers seeking low-cost nodes should implement rigorous QC and supplier‑audit protocols to manage quality drift risk.
-
Cayman Chemical & MedChemExpress: Specialists in high‑purity and certified reference materials for research and analytical use. Their strategies underscore the value of reputation and certification in premium niches — an important model for any supplier seeking to move up the value chain.
-
CDH Fine Chemical & Tokyo Chemical Industry: ISO‑certified exporters with broad distribution networks, supporting global laboratories and industrial customers. They illustrate the strategic edge of combining manufacturing competence with global logistics and regulatory support.
Across these competitors, the market is neither fully fragmented nor fully consolidated — creating room for ambitious mid-market players to scale through targeted investments in certification, traceability, and selective capacity expansions.
Priority strategic actions for 2026
-
Conduct a supplier risk audit Q1–Q2 2026 focused on feedstock exposure, certification gaps, and single‑source dependencies.
-
Lock in hybrid sourcing contracts that combine spot and volume commitments with index-linked price collars to limit upside risk while preserving supply flexibility.
-
Prioritize investment in certification (USP/EP) if targeting pharmaceutical channels; for consumer-facing applications, build traceability and sustainability claims that can command a premium.
-
Evaluate bioprocessing partnerships or minority investments in fermentation capacity as a hedge against agricultural volatility and as a route to predictable unit economics.
-
For investors: screen targets not only by revenue but by certification depth, geographic diversification, and feedstock control — these attributes materially affect valuation under stress scenarios.
-
Revise R&D roadmaps to exploit gallic acid derivatives and high-value formulations; small technical shifts can unlock step-changes in margin.
How to use this intelligence in your 2026 decision calendar
Early 2026: complete high-priority supplier audits and define risk-adjusted sourcing budgets. Mid 2026: finalize certification investments and test pilot partnerships in bioprocessing. Late 2026: activate M&A or JV diligence if capacity or technology gaps remain. Throughout 2026: monitor feedstock indices and regulatory updates; use the PW Consulting dashboards to translate macro scenarios into P&L and working-capital impacts.
Final note — the strategic value of the full PW report
This preview outlines the directional implications and high‑level recommended actions for 2026. The full PW Consulting report contains the granular models, supplier scorecards, validated capacity tables, and scenario P&L outputs that operational teams need to execute on these strategies. We deliberately withhold the detailed segmentation tables in this public preview — the most actionable intelligence (e.g., regional and application-level breakdowns, supplier capacity by grade, and contract-level price sensitivity analyses) resides in the full report and dashboards available through our client portal.
If your 2026 plans involve securing ingredient continuity, moving up the value chain into regulated channels, or making targeted acquisitions, this report is designed to be the analytical backbone for those decisions. PW Consulting’s Gallic Acid market study translates market dynamics into executable steps — from procurement playbooks to M&A checklists — so that you can make decisions in 2026 with conviction and evidence-backed downside protection.
For detailed analysis of this topic, please visit the official page: Gallic Acid (CAS 149-91-7) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Photo Booth Market to Hit USD 1,250M by 2032 at 9.37% CAGR
By pmarketresearch, 2026-07-13
Photo Booth Market 2026: Strategic Preview for Leaders — A PW Consulting Brief
Between 2020 and 2025 the global photo booth market moved from a niche experiential offering toward a scalable event-technology category, expanding from USD 480.0 million (2020) to USD 671.0 million (2025). Our base-year analysis and seven-year forecast show the market continuing to grow through the next planning cycle: with a compound annual growth rate (CAGR) of 9.37% in the 2026–2032 forecast window, the sector is expected to approach about USD 1.25 billion by 2032. For executives making decisions in 2026, that trajectory translates into a compelling combination of growth opportunity and structural complexity — and this preview explains why.
Photo Booth Market
Why this study matters for 2026 decision-making
-
Growth with selective consolidation: the market is expanding consistently, but concentration remains low — the top three and top five providers hold roughly one-third of the industry revenue. That combination favors fast-moving challengers, vertical integrators and platform plays that can capture adjacent value (hardware, software, and fulfillment) without relying on scale-based moats alone.
Photo Booth Market -
Timing matters for product investment: adoption curves for upgraded experiences (360-degree booths, mirror/interactive surfaces, AI-enabled editing) are steepening. Investing in modular technology and software platforms today reduces technical debt and shortens payback windows on rental and SaaS business models.
Photo Booth Market -
Operational resilience is a strategic lever: supply-chain volatility and trade friction have increased component costs and extended lead times, making supplier strategy and inventory policy central to margin protection.
Market dynamics: the drivers shaping 2026 strategy
-
Event demand is re-normalizing and segmenting. Weddings and brand activations continue to be primary revenue anchors, but the dynamics within those applications are evolving — customers now expect integrated digital outputs, social sharing and on-site data capture as standard elements of a booth experience.
-
Technology is shifting value from hardware to SaaS and creative services. Camera automation, generative editing and instant-delivery workflows are creating recurring-revenue opportunities beyond one-time rentals. Recent product activity at major expos signals that AI-enabled creative tooling and video-capable booths will become procurement priorities for rental fleets and in-house event teams alike.
-
Pricing and unit economics are being rewired. Average rental packages in mature markets have converged around mid-hundreds of dollars per event, but there is a broad spectrum depending on equipment sophistication and value-added services. As operators introduce premium video and AI services, they can expand margins through tiered pricing and service bundles.
-
Supply-side pressure: tariffs and longer lead times for China-sourced components have driven component price pressure in the single-digits to low-teens percent range. That makes procurement hedging, alternative sourcing and design for localizability important cost-management levers.
-
Regulatory and safety compliance is non-negotiable. Event licensing, privacy expectations for image capture, and safety standards for on-site equipment are increasingly enforced — compliance capabilities are table stakes in vendor selection for corporations and venues.
Competitive landscape — who to watch and what they signal
The ecosystem combines global network operators, specialty manufacturers, software-platform vendors and full-service rental brands. Key participants illustrate prevailing strategic archetypes:
-
Network consolidators and platform integrators — exemplified by global operators that have grown through acquisitions and network play. Their model emphasizes scale in deployment and footprint economics, and they pursue recurring revenue through managed services and print/fulfillment contracts.
-
Hardware-first manufacturers — companies that design modular, ruggedized booths for rental operators and venues. Their advantage is product reliability and supply continuity, though margin pressure forces them to extend offerings into software and services.
-
Software and experience innovators — vendors focused on UX, AI templates, video capabilities and cloud-driven editing/publishing. Recent launches at industry expos highlight how quickly software differentiation can change the competitive balance.
-
Event-focused full-service brands — operators that combine venue relationships, creative production, and live-event logistics. Their value is experiential control and high-touch sales to corporate clients, though scalability requires platform investments.
Selected companies from our competitive map illustrate these archetypes and the strategic moves to monitor:
-
ME Group International — a strategic consolidator operating international networks of photo booths and having grown footprint through acquisitions. Their approach shows the value of multi-country scale in a capital-intensive segment.
-
Photo Booth Supply Co. and Simple Booth — examples of companies marrying portable hardware with software ecosystems aimed at event operators; these players highlight the margin and lock-in benefits of bundled offerings.
-
Specialist rental networks and full-service providers such as ShutterBooth , Selfie Booth Co. and several regional players demonstrate demand for turnkey event services and localization of creative offerings.
-
Hardware and robotics innovators, including firms experimenting with automated capture and 360-degree rigs, indicate where product premiumization can support higher yield per event.
Technology and product trends that will re-shape vendor economics
-
AI-enabled creative workflows: template-driven editing, generative post-processing and instant social delivery will be the most visible differentiator on the showroom floor. Recent product announcements by software vendors and camera integrators demonstrate that these capabilities are moving from R&D into productization.
-
Hybrid hardware models: modular open-air booths that can be configured for print, digital delivery or video are becoming the default for rental fleets. That modularity supports faster route-to-market for new experiences while reducing capex per incremental feature.
-
Data capture and activation: clients increasingly want audience data as part of the activation — think CRM-ready captures, lead-scoring triggers, and follow-up workflows. Vendors that can offer privacy-compliant capture and integration with marketing stacks will command pricing power with corporate buyers.
Commercial implications and go-to-market priorities for 2026
-
Productize services: Operators should move from one-off event quotes toward subscription and bundled models that include hardware refreshes, content libraries and analytics. This reduces the cyclicality of rental revenues and improves customer lifetime value.
-
Invest in software ecosystems: For hardware manufacturers, prioritizing SDKs, APIs and white-label software reduces churn and opens B2B2C licensing opportunities.
-
Build procurement resilience: Given component-cost volatility and trade friction, dual-sourcing strategies and design choices that minimize long-lead proprietary parts will protect margins.
-
Upgrade compliance and privacy controls: Ensure data capture and image-handling workflows meet increasingly strict privacy regimes and venue insurance requirements — a competitive advantage for operators who can demonstrate governance and auditability.
What PW Consulting’s full report delivers — practical, operational, decision-ready content
Our comprehensive market study is designed for leaders who need to move from insight to action. The core deliverables include:
- Validated historical market sizing and a detailed 2026–2032 forecast model with scenario analysis calibrated for hardware, software and service revenue pools.
- An actionable supplier and component-cost matrix to evaluate procurement risk and identify potential cost-reduction levers under different tariff and lead-time scenarios.
- Competitive diligence on platform, hardware and rental operators, including capability heat maps and go-to-market archetypes for partnership or M&A screening.
- Product-roadmap evaluation criteria and ROI templates to prioritize investments in AI, video and modular hardware across a three-year horizon.
- Commercial playbooks for operators and manufacturers: pricing ladders, bundling strategies, and sample commercial contracts aligned to venue and corporate buyer needs.
- Regulatory and compliance checklist tailored to event operators, venues and manufacturers — covering licensing, safety, and privacy considerations by jurisdiction.
Strategic recommendations — how to act in 2026
-
Define your role in the value chain. Decide whether to be a platform-led player, product specialist or full-service operator — each choice dictates capex intensity, partner profile and go-to-market motion.
-
Prioritize software-first investments that unlock recurring revenue. Even modest software ARPU can materially improve unit economics and justify higher valuation multiples for growth-capital raises.
-
Segment your route-to-market by buyer economics. Corporate activations and venue partnerships require different sales motions and SLA commitments than private-event rentals; tailor product and service levels accordingly.
-
Lock in supply flexibility. Negotiate contingency agreements with key suppliers and design product variants that can be localized with minimal engineering overhead.
-
Experiment with premium experiences. Pilot AI-enabled and video-capable formats in high-visibility activations to validate higher price points and gather performance data for broader roll-out.
Closing: where to go next
The photo booth market in 2026 is neither a fading novelty nor a fully mature appliance market — it is an experiential category undergoing platformification. Growth is robust, but success requires a coordinated approach across product, software, supply chain and commercial strategy. Our full report provides the granular segmentation, supplier-level cost tables, and scenario-modeled forecasts necessary to convert this strategic preview into executable plans. For practitioners making capital allocation, product roadmap or M&A decisions this year, the empirical frameworks and decision templates in the full study will shorten the path from insight to impact.
To access the detailed segmentation, company profiles and the decision-support models referenced in this brief, please consult the full PW Consulting Photo Booth Market report. The full study contains the restricted segmentation detail and appendices that underpin the forecasts and recommendations summarized above.
For detailed analysis of this topic, please visit the official page: Photo Booth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Azimuth Thrusters Market to reach $610.3M by 2032 at 1.49% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
Azimuth Thrusters Market: Strategic Brief for 2026 Decision-Makers
Executive summary
The azimuth thrusters market remains a specialist but strategically important segment of marine propulsion, with a market size that has gravitated around USD 550 million in the mid‑2020s. Using 2025 as the base year, our forecast through 2032 projects a moderate expansion to roughly USD 610 million, reflecting a compound annual growth rate (CAGR) of approximately 1.49% over the 2026–2032 horizon. That growth masks persistent volatility across the prior half‑decade and divergent dynamics by vessel type, propulsion architecture, and regional demand drivers.
Azimuth Thrusters Market
For executives preparing 2026 plans, this market sits at the intersection of decarbonization ambition, tougher electrical and acoustic standards, and tightening upstream material controls. Those forces create both constraint and opportunity: vendors and buyers who align product roadmaps, supply‑chain strategies, and certification roadmaps will capture disproportionate value, while laggards face margin compression and delivery risk.
Azimuth Thrusters Market
Why this research matters for decisions in 2026
-
Timing capital allocation: With a low-single-digit CAGR and limited upside in the near term, investment decisions must prioritize R&D and retrofit solutions that improve lifetime economics (fuel/electricity consumption, maintenance intervals) rather than betting on rapid volume expansion.
Azimuth Thrusters Market -
Product roadmap prioritization: New electrical control certifications (UL 3141, UL 1741) and ISO efficiency/noise mandates mean that product delays are costly. Companies should sequence feature development to secure early certification and first‑mover trust in niche applications (e.g., dynamic positioning, ice operations).
-
M&A and partnership calculus: The market concentration metrics show a moderately consolidated supplier base. Strategic bolt‑ons that fill capability gaps (rim‑drive expertise, retractable mechanisms, power electronics) deliver faster route‑to‑market than greenfield scaling.
-
Supply‑chain resilience: Export controls on critical materials and wage inflation for specialized labor demand near‑term hedging—longer lead times for titanium or rare earth magnets will affect new builds and retrofit schedules.
How to read the high‑level data
Our report uses 2025 as the base year and tracks historical performance from 2020–2025. The path to 2032 reflects scenarios calibrated to demand in key marine segments and the evolving regulatory landscape. The headline figures show mid‑decade stabilization followed by measured growth to ~USD 610 million by 2032 at a 1.49% CAGR. The story behind those numbers is heterogenous: certain vessel classes and propulsion architectures expand faster, others are constrained by capex cycles and supply friction. The report surfaces those drivers without exposing proprietary segmentation data in this preview—download the full dataset for granular regional and application breakdowns.
Report contents — what the full study delivers
-
Market sizing and scenario models: transparent assumptions and sensitivity analyses that let you re‑run forecasts under alternate oil price, regulatory, and supply‑shock scenarios.
-
Go‑to‑market playbooks: commercial strategies tailored for OEMs, system integrators, and shipowners—covering pricing levers, warranty models, and aftermarket services packaging.
-
Supplier scorecards and capability matrices: comparative assessments across design, manufacturing depth, certification maturity, and aftermarket network—presented to inform procurement and M&A diligence.
-
Regulatory and standards impact analysis: practical interpretation of UL and ISO developments and checklist‑style guidance for compliance sequencing across electrical and acoustic subsystems.
-
Cost‑to‑serve and lifecycle economics: OPEX/CAPEX modeling that isolates where efficiency gains or electrification premium pay back under different operating profiles.
-
Risk registers and mitigation playbooks: supply‑chain hedges, sourcing alternatives, and workforce strategies for specialized marine engineering labor.
Competitive landscape — what to watch in 2026
The market exhibits moderate concentration: the top three players control a majority share (CR3 ~55%), with the top five reaching around 65% (CR5 ~65%). That structure favors established vendors with deep engineering benches and global service footprints. Our competitive review highlights product differentiation vectors and strategic moves you should monitor.
-
Kongsberg Maritime (Norway): A technology leader in rim‑drive solutions and high‑voltage permanent magnet platforms. Recent product introductions continue to push the boundaries on shallow‑draft and DP‑capable rim drives; expect Kongsberg to lean into electrified ferries and offshore support sectors.
-
SCHOTTEL Group (Germany): Strong heritage in Z‑drive and L‑drive architectures with broad OEM relationships. SCHOTTEL’s portfolio and marine service network make it a go‑to supplier for conventional commercial vessels and retrofit programs.
-
ZF Marine (Germany): Fast follower with recent AT series launches. ZF’s product refresh cadence signals focus on modularity and simplified integration for shipyards—key when vessel yards manage compressed build schedules.
-
Thrustmaster of Texas (United States): Known for heavy‑duty, high‑power units and configurable propeller arrangements. Their catalogue updates show emphasis on deck‑mounted and mini‑skid solutions for offshore and escort applications.
-
Brunvoll AS & Steerprop (Nordic specialists): Niche innovators—Brunvoll in retractable units for energy‑sector vessels and Steerprop in ice‑class designs. These suppliers win when performance under extreme conditions matters more than unit price.
-
Voith, Veth (Twin Disc), Wärtsilä, Kawasaki, Niigata, IHI: Each plays to specific strengths—whether inline swing designs, shallow‑draft packages for yachts, or high‑reliability systems for riverine and harbor operations. Expect continued role specialization rather than broad convergence.
Recent market signals to track: product launches (e.g., new AT Series and rim‑drive releases), targeted contracts for ocean energy and support vessels, and catalog refreshes emphasizing retractable and compact azimuth units. These moves reflect both tactical replacement demand and longer‑term positioning for electrification and offshore support growth.
Supply chain, regulation and geopolitical dynamics
-
Raw materials and export controls: Controls on titanium and rare earth exports have increased procurement costs and lead times—forcing OEMs to either redesign with alternative alloys or build inventory cushions. Scenario planning for material black‑swan events is now a required line item in procurement forecasts.
-
Standards and certification: New UL certifications for electrical control systems and tighter ISO mandates on efficiency and acoustic emissions raise the compliance bar. Incorporating certification timelines into product launch schedules is essential to avoid market access delays—especially for US and EU flag projects.
-
Labor and manufacturing capability: High‑power rim‑drive and precision titanium blade fabrication require specialized labor. Wage inflation in key manufacturing clusters increases variable costs and shifts the advantage toward firms with automated machining or diversified manufacturing footprints.
Actionable recommendations for executives (2026 planning cycle)
-
Prioritize retrofit and digital services: With fleet renewal slow, aftermarket services and retrofit offers (efficiency upgrades, digital remote diagnostics) deliver quicker ROI and build sticky customer relationships.
-
Lock in certification roadmaps: Start certification programs (UL, ISO) 12–18 months ahead of commercial launch. Allocate cross‑functional resources to anticipate test failures and iterative design changes.
-
De‑risk raw material sourcing: Pursue multi‑sourcing, alternative materials testing, and strategic inventory positions for critical inputs. Where possible, negotiate long‑term offtake or toll‑processing arrangements with suppliers.
-
Consider focused M&A: Target bolt‑on acquisitions that add rim‑drive, retractable mechanisms, or power electronics IP rather than chasing broad geographic expansion. Acquisitions that expand aftermarket presence are particularly accretive.
-
Invest in modular integration: Standardize interfaces (mechanical, electrical, control APIs) to reduce shipyard integration risk and accelerate certification reuse across platforms.
Decision frameworks included in the full study
The report supplies decision tools you can operationalize immediately: NPV and payback templates tailored to thruster retrofit vs newbuild scenarios; a supplier resilience heatmap; a regulatory compliance tracker; and a three‑layer product roadmap template linking R&D investment to certification milestones and go‑to‑market windows. These frameworks are populated with scenario inputs and benchmarking ranges so teams can run rapid sensitivity tests aligned to corporate risk appetite.
Next steps and how to use the full report
Use the full study to ground FY‑2026 budget discussions, set 3‑year product investment priorities, and align procurement strategies across marine and offshore portfolios. This preview highlights the strategic contours—supply friction, certification timetables, and concentrated competition—that will determine winners and losers. For access to the complete datasets, regional/application splits, supplier scorecards, and the downloadable Excel models, please visit the published report page. The detailed segmentation tables and scenario model are intentionally gated to preserve commercial value and provide your team with the practical tools needed to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Azimuth Thrusters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ionomer Market — Strategic Preview for 2026 Decision-Making
As companies prepare plans and capital allocations for 2026, the ionomer market presents a technically nuanced, commercially meaningful opportunity — and a set of operational risks that can materially affect margins and time-to-market. This preview synthesizes the high-level findings from PW Consulting’s Ionomer Market study (base year: 2025; historical scope: 2020–2025; forecast horizon: 2026–2032) to help executives and investors prioritize choices. We demonstrate the analytical depth behind our work while reserving the granular segmentation tables and model outputs for the full report on our site.
Ionomer Market
Market trajectory at a glance
Through 2020–2025 the ionomer market experienced steady expansion from a modest base, with a notable plateau in the mid-period before renewed momentum into 2025. Measured in USD Million (base year 2025), the market reached a mid‑hundreds level by 2025 and is projected to continue expanding through the 2026–2032 forecast window. Our baseline forecast assumes a compound annual growth rate (CAGR) of 6.5% across 2026–2032, reflecting steady demand growth from packaging and specialty end‑uses together with ongoing product innovation that uplifts average selling prices and application penetration.
Ionomer Market
Two observations from the time series are especially important for 2026 planning: first, the market has shown resilience after a temporary demand plateau; second, the coming multi‑year growth is substantial enough that strategic choices made in 2026 — on sourcing, capital allocation, and product positioning — will determine relative competitive standing through the late 2020s.
Ionomer Market
What is driving growth — and what to watch
- End‑use demand mix. Ionomers continue to serve a cross‑section of applications from premium consumer goods to performance packaging and select industrial uses. Innovation in barrier, clarity and tactile properties is enabling ionomers to displace or augment alternatives in high‑value packaging and specialty consumer segments.
- Product premiumization and formulation shifts. Higher‑performance ionomer grades and tailored blends are commanding price and specification premiums. This dynamic supports revenue growth beyond simple volume expansion.
- Regulatory and tariff shocks. Regulatory measures and trade policy are increasingly important near‑term variables. Examples include new registration regimes in major production geographies and recently announced tariff measures affecting resin imports — all of which affect supplier selection and landed costs.
- Feedstock and raw‑material volatility. Feedstock price volatility feeds directly to resin margins. Case in point: an industry reference for ionomer pricing in hydrogen fuel‑cell systems highlights a substantive per‑kilogram cost at modest production scale; more broadly, crude price shocks and potential supply disruptions continue to accelerate feedstock cost pass‑through.
Supply dynamics and cost risk
Our analysis puts supply‑side dynamics at the core of 2026 decisions. Key points:
- Raw material economics are a primary driver of short‑term margin pressure. Public data points and technical cost models indicate that specialized ionomer grades can be costly to produce at small scale and sensitive to feedstock swings. Procurement strategies and contract terms need to reflect this reality rather than assuming stable input prices.
- Regulatory compliance costs are rising. New chemical registration requirements in major production markets require capital and operating expenditures to meet compliance timelines. These costs are uneven across producers and tend to re‑rank supplier competitiveness in procurement RFPs.
- Trade measures and logistics risk are material. Recent tariff moves that affect resin imports have created near‑term landed cost uplifts for affected supply chains. Geopolitical events that threaten critical maritime chokepoints further raise the case for redundancy in supply and for scenario planning in 2026 budget cycles.
Competitive landscape — how incumbents are positioned
The market structure is characterized by a mix of integrated global majors, regional producers, specialty formulators and international distributors. Market concentration metrics indicate that the leading three suppliers account for a meaningful plurality of demand, while the top five approach a clear majority — a structure that creates scale advantages but leaves room for regional players and specialty suppliers to prosper where technical differentiation or local service matters.
- Global integrated producers. Established polymer majors with global manufacturing footprints (e.g., Dow Inc., E. I. du Pont de Nemours and Company, ExxonMobil, Solvay, LyondellBasell) benefit from scale, proprietary grades and extensive channel relationships. Their ability to bundle upstream feedstock procurement and downstream technical service is a decisive competitive edge in several high‑value applications.
- Specialty and regional producers. Companies such as Asahi Kasei, Kuraray, LG Chem and selected Chinese producers combine technical depth with closer customer proximity in key growth markets. These firms often win on local responsiveness, tailored formulations and competitive pricing where logistics or regulatory advantages apply.
- Distributors and formulators. Channel players and specialty formulators (distributors and smaller specialty manufacturers) play an outsized role in converting base ionomers into application‑ready solutions, enabling OEMs and converters to accelerate time‑to‑market without heavy CAPEX.
For 2026 strategy, the implication is clear: scale, proprietary technology and integrated supply chains will define winners at the national and global levels, but targeted investments in formulation, local capacity and regulatory compliance will open corridors for challengers.
Strategic choices for 2026 — an action checklist
Executives should treat 2026 as a pivotal planning year. Key, actionable priorities derived from our study:
- Sourcing resilience. Build dual‑sourced supply chains and include explicit pass‑through and indexation clauses in long‑term contracts to manage feedstock volatility.
- Hedging and procurement sophistication. Use a mix of physical hedging, financial hedges and option provisions for sensitive grades; run quarterly stress tests against price spikes and tariff shocks.
- Localized manufacturing and inventory strategy. Where regulatory or logistical risk is high, evaluate near‑market capacity or toll‑manufacturing partnerships to reduce lead times and landed‑cost exposure.
- R&D and product roadmap alignment. Prioritize low‑cost, high‑performance formulations that lower total system cost for customers; build portfolio choices that allow premium capture in differentiated applications.
- Commercial and contractual repositioning. Revisit pricing architecture, minimum off‑take clauses and force‑majeure language to reflect evolving trade and feedstock risks.
- M&A and JV readiness. Use 2026 to prepare playbooks for opportunistic M&A: target regional capacity, specialty formulation capabilities, or backward integration into key feedstocks.
- Regulatory compliance planning. Budget for registration and testing timelines; align product launches with compliance milestones in major markets.
- Customer segmentation and value capture. Resegment your customers by value‑to‑you rather than by volume alone, and deploy differentiated service and formulation bundles accordingly.
What the PW Consulting report delivers (practical components)
The full Ionomer Market study is designed as a working document for commercial and strategic teams. Key deliverables include:
- Granular, bottom‑up market sizing and demand model (historical and forecast periods) with downloadable model access and scenario toggles.
- Supply‑chain mapping for major grades and geographies, including capacity maps, lead times and logistics cost drivers.
- Price and margin sensitivity analysis under alternative feedstock and tariff scenarios.
- Regulatory impact matrix and compliance roadmaps for key jurisdictions.
- Competitive benchmarking with capability matrices, SWOT summaries and commercial positioning for lead suppliers.
- Practical go‑to‑market playbooks for product launches, conversion wins, and distributor partnerships — including contract archetypes and negotiation levers.
- M&A screening framework and a short‑list of target archetypes (methodology and scoring; individual target data supplied in the full report).
- Primary interview syntheses and supplier call logs that underpin our market intelligence.
To preserve the strategic value of the analysis for our subscribers, the full report contains the detailed regional, type and application split tables, precise price ladders and downloadable forecast models. The excerpts above are intended to orient decision‑makers and highlight the areas where our proprietary data materially changes choices for 2026.
Near‑term scenarios and recommendations
We stress‑test three plausible 2026 scenarios in the full study — baseline growth, elevated cost stress (tariffs + feedstock spike), and accelerated premium adoption — each with actionable triggers for when to implement specific procurement, investment or commercial moves. For most firms, a hybrid approach is optimal: maintain flexibility in sourcing and contracts while selectively accelerating investments in differentiated grades and regional service capability.
Immediate recommended actions for leadership teams preparing 2026 plans:
- Run a rapid vulnerability audit of your ionomer exposure (by grade and supplier) and quantify P&L sensitivity to a 10–30% feedstock cost shock.
- Initiate conditional supply agreements with at least two qualified suppliers in different trade zones, including explicit tariff contingency language.
- Prioritize a pilot program for premium formulations with one lead customer to validate pricing power and incremental margin potential.
- Allocate a modest M&A watchlist budget and shortlist 2–3 regional targets that would materially de‑risk logistics or regulatory exposure.
Closing — why 2026 matters
Market dynamics are aligning such that choices made in 2026 — on sourcing structure, product differentiation and regulatory compliance — will determine whether firms secure durable margin expansion or simply endure cyclical pressures. PW Consulting’s Ionomer Market study is designed to convert macro signals into practical, executable plans. For executives who require the full model, detailed segment tables, and supplier‑level economics that underpin our recommendations, the full report and supporting datasets are available on our website.
Contact PW Consulting to schedule a briefing and receive the model license and proprietary annexes that will enable your 2026 strategy team to move from scenario to action with confidence.
For detailed analysis of this topic, please visit the official page: Ionomer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Holter ECG Market to Expand at 7.52% CAGR (2026–2032) — PW Consulting
By pmarketresearch, 2026-07-13
Holter ECG Monitoring Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
By the end of the base year (2025) the global Holter ECG monitoring market had solidified into a mature-but-growing segment of ambulatory cardiac diagnostics. Our PW Consulting baseline places 2025 market value and projects a steady compound annual growth rate (CAGR) of 7.52% across the 2026–2032 forecast window. Under this trajectory, the market expands meaningfully through 2032, driven by converging forces in device miniaturization, cloud-native analysis platforms, reimbursement clarity for extended monitoring, and an accelerating pipeline of regulatory-cleared wearable and patch technologies.
Holter ECG Monitoring Market
Why this research matters for 2026 corporate strategy
- Timing for portfolio bets: 2026 represents an inflection period where product investments made in 2024–25 begin to compete in volume and software integration. Companies that align R&D, regulatory and commercial teams now can capture share as the installed base upgrades to wireless, cloud-enabled systems.
- Go-to-market segmentation discipline: While headline growth is attractive, value is concentrated. Our analysis identifies where high-margin clinical interpretation services and software-as-a-service (SaaS) models sit relative to commoditized hardware — information that directly informs M&A and pricing decisions.
- Reimbursement arbitrage: Clarified CPT and Medicare dynamics for monitoring durations up to and beyond 48 hours make 2026 the year to optimize clinical pathways and coding strategies for ambulatory monitoring bundles.
- Regulatory and commercialization sequencing: With the FDA maintaining 510(k) pathways for many ambulatory systems and continued emphasis on post-market surveillance for Class II devices, strategic sequencing of clearances, labeling and claims will materially impact adoption velocity.
Market trajectory: What the headline numbers tell you
Over the historical base period (2020–2025) the sector demonstrated resilience and steady expansion. The market’s projected CAGR of 7.52% (2026–2032) underpins a multi-year growth runway — sufficient to support both organic growth strategies and selective bolt-on acquisitions. For 2026 planning, this level of growth implies predictable volume expansion for core hardware while creating outsized upside in software-driven interpretation, remote patient monitoring services, and extended-duration patch monitoring.
Holter ECG Monitoring Market
Report scope — pragmatic, action-oriented deliverables
This study is structured to convert market intelligence into executable actions. Key practical contents include:
Holter ECG Monitoring Market
- Methodology and transparent datasets covering the historical period (2020–2025) and forecasts to 2032 with scenario analyses reflecting conservative, base and accelerated adoption curves.
- Market sizing and topline forecasts (base year 2025) with sensitivity testing around pricing, reimbursement shifts and adoption timelines for wearable/patch systems.
- Commercial opportunity maps identifying high-return end-user segments, procurement cycles, and pricing benchmarks — presented as playbooks for sales and product teams.
- Regulatory and reimbursement compendium: a practical guide to relevant CPT code applications, Medicare local coverage considerations and FDA 510(k) requirements that affect time-to-market and claim packaging.
- Competitive landscaping with strategic profiles of incumbents and emerging challengers, including technology positioning, channel strategies and likely M&A targets.
- Operational benchmarking for OEMs and service providers: margins by business model (device sales vs. SaaS vs. interpretation services), deployment cost curves, and best-practice implementation checklists for clinical partners.
- Scenario-based playbooks for four strategic archetypes: incumbent OEMs, digital-native challengers, hospital systems/integrators, and specialized interpretation-service providers.
Competitive landscape — who matters and why
The competitive set spans legacy medical-device OEMs, device-focused regional players, and software-first incumbents. Market concentration indicates a meaningful share clustered among top players, creating an environment where scale and integrated service offerings matter.
- Large OEMs (platform and channel advantage): Global incumbents bring distribution scale, channel trust and integrated systems. Their priorities are incremental device innovation, backward compatibility, and embedding Holter data streams into broader cardiology informatics suites.
- Specialist device makers (cost and customization): Companies with focused Holter portfolios compete on device reliability, ease of use and local service economics. They are often first adopters of multi-lead and multi-modality recording within regional hospitals and ASC networks.
- Digital-native challengers (software-first disruption): Cloud-native interpretation platforms and patch-based continuous monitors are redefining care pathways. Rapid FDA clearances for end-to-end digital platforms have shortened the route from device deployment to revenue recognition for recurring interpretation services.
Prominent firms analyzed in the report include long-standing OEMs and several high-impact challengers. For corporate strategists, the decision levers are clear: secure clinical validation and reimbursement pathways for new modalities; decide whether to vertically integrate interpretation services or partner with third-party platforms; and prioritize channel investments where adoption is velocity-driven.
Recent regulatory and product developments shaping 2026 adoption
- Several FDA 510(k) clearances in the 2024–2025 window for cloud-native and wireless ambulatory systems have lowered technical barriers to market for new entrants and enabled faster clinical workflows for retrospective analysis.
- U.S. reimbursement frameworks continue to recognize discrete CPT pathways for short and extended-duration external monitoring, with local coverage determinations affirming codes for up to 48 hours and additional codes for monitoring beyond 48 hours. This clarity increases the commercial predictability for extended-monitoring products in clinical pathways such as post-stroke arrhythmia surveillance.
- Regulatory emphasis on post-market surveillance for Class II ambulatory monitors elevates the importance of robust QA, real-world performance data and documentation — a differentiator for vendors with established clinical registries.
Technology and clinical trends to watch
- Patch and single-lead continuous monitoring: Adoption is accelerating where patient comfort, adherence and remote workflows reduce clinic visits. These solutions also enable subscription-based interpretation models.
- AI-assisted interpretation: Cloud-native analytics and validated algorithms are reducing turnaround times for Holter interpretation, enabling near-real-time triage of critical arrhythmias and more scalable interpretation services.
- Hybrid hardware-software business models: Expect more vendors to bundle devices with recurring software and interpretation fees — shifting revenue mix and margin profiles across the industry.
- Integration into care pathways: Hospitals and ambulatory centers increasingly demand end-to-end interoperability with EHRs and cardiac care orchestration platforms, making open APIs and standards compliance commercial prerequisites.
Strategic implications and practical recommendations for 2026
- For incumbents: Prioritize software partnerships or acquisitions that accelerate cloud interpretation capabilities and create recurring revenue streams. Protect installed base through upgrade pathways rather than forcing hardware swaps.
- For challengers and startups: Focus on niche clinical claims where patch or AI advantages produce defensible adoption barriers. Invest early in FDA evidence generation and payer engagement to avoid commercialization delays.
- For hospital systems and ASCs: Negotiate bundled service agreements that align device procurement with interpretation and telemetry services to lower per-patient monitoring costs and ensure coding compliance.
- For investors: Target companies with a clear SaaS monetization path, validated clinical performance and exposure to extended-duration monitoring use cases, which show higher willingness-to-pay.
What you won’t find here — and why you should read the full report
This preview intentionally omits detailed segmentation tables and granular regional/application breakouts that materially influence go-to-market tactics. The full PW Consulting Holter ECG Monitoring Market report contains the granular splits, pricing matrices, detailed competitor benchmarking, and proprietary channel economics that operational teams need to execute with confidence. Those datasets are essential for building precise sales forecasts, negotiating distributor agreements, and sizing acquisition targets.
How to use this research in your 2026 planning cycle
- Align product roadmaps to the identified technology inflection points (patch adoption, AI interpretation, EHR interoperability).
- Map reimbursement windows to launch timelines so device claims and coding enable immediate revenue capture upon commercialization.
- Use the scenario models in the full study to stress-test M&A targets and validate payback periods for R&D investments under different adoption speeds.
- Leverage competitive profiles to identify white-space opportunities where incumbents are weak (e.g., cloud-native interpretation, integrated chronic care bundles).
Closing — a strategic invitation
As 2026 approaches, the Holter ECG monitoring market offers a blend of steady growth and targeted disruption. The headline CAGR and forecast trajectory indicate reliable topline expansion, but the real value lies in the details: product claims, reimbursement sequencing, clinical validation and channel economics. PW Consulting’s full report provides those actionable datasets and strategic playbooks — the essential inputs for executives deciding where to invest, partner or divest in the coming 18–36 months. For the complete intelligence suite and executable scenarios, access the full report.
For detailed analysis of this topic, please visit the official page: Holter ECG Monitoring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fan Coils Market to reach USD 344.8 Million by 2032 at 5.2% CAGR
By pmarketresearch, 2026-07-13
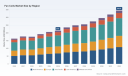
Fan Coils Market: Strategic Intelligence for 2026 Decision-Makers
As organizations prepare capital allocation, product roadmaps, and channel strategies for 2026, the fan coils market represents a steady-growth segment of commercial and residential HVAC with clear risk vectors and identifiable opportunity windows. Our PW Consulting Fan Coils Market study (base year 2025) synthesizes a seven-year historical view and a seven-year forecast to 2032, offering a practical playbook for executives, investors, and technical leaders who must make near-term decisions that compound over product life cycles. The market has recovered and expanded from the early-2020s volatility into a structurally healthier space — with a mid-single-digit compound annual growth rate (CAGR) driving total demand from the 2025 base to a materially larger market by 2032. This study is designed as a decision support tool: deep enough to validate strategic choices, discreet enough to guide you back to the full report for transaction-grade detail.
Fan Coils Market
Market Snapshot and Trajectory
Our analysis captures a seven-year historical window and a 2026–2032 forecast horizon. After modest fluctuations in the early 2020s, the market stabilized into a consistent expansion path. From the 2025 base, the model applies a 5.2% CAGR across the forecast period, reflecting demand driven by retrofit cycles, new commercial building activity tied to healthy service-sector growth, and increasing specification of energy-efficient terminal equipment in both retrofit and new-build programs. The projection shows meaningful compounding through 2032, underlining why strategic choices made in 2026 — on product design, supply chain resilience, and channel deployment — will determine market share trajectories over the next decade.
Fan Coils Market
Why 2026 Is a Strategic Inflection Point
-
Regulatory tightening and compliance complexity: Updated AHRI standards on performance rating and sound testing have changed how products are tested, documented, and marketed. These regime updates increase the burden on product development, testing, and certification cycles — and at the same time create a defensible differentiation for compliant, well-documented designs.
Fan Coils Market -
Component- and commodity-cost volatility: Steel pricing dynamics heading into 2026 — driven by tariffs, mill maintenance, and inventory restocking — mean procurement strategies and product costing frameworks must be revisited. Margin protection will require a combination of supplier contracting, design-for-cost initiatives, and selective risk transfer.
-
Technology parity moves to service parity: Variable-speed drives, electronically commutated motors (ECMs), and noise-optimization techniques are rapidly moving from premium options to expected baselines in many commercial specifications. The business case increasingly hinges on how these features enable serviceability, energy savings during operation, and simpler integration into building controls.
-
Market concentration and competitive dynamics: The sector exhibits moderate concentration at the top end of the market, meaning mid-sized and specialized players can still capture niches through acoustics, hydronic integration, or retrofit-fit designs — provided they deploy the right go-to-market approach.
What the PW Consulting Report Delivers — Actionable, Not Academic
This is a practitioner’s report built to be operated from the executive suite to the product line. Key components include:
-
Proprietary market-sizing and forecast model (2020–2032) with scenario toggles for commodity shocks, accelerated efficiency mandates, and accelerated heat-pump adoption. The model is configurable to test pricing, volume, and mix sensitivities.
-
Go-to-market playbooks for OEMs, distributors, and service providers that translate technical differentiation (e.g., low-noise, ECM, hydronic compatibility) into sales motions, spec strategies, and channel economics.
-
Supplier and supply-chain stress tests, including detailed recommendations on hedging strategies, single-source risk reduction, near-shoring tradeoffs, and inventory policy optimization for 2026 capital planning.
-
Regulatory compliance roadmap: a step-by-step implementation map for AHRI performance and sound standards with recommended testing timelines, lab partnerships, and documentation templates to reduce time-to-market risk.
-
Competitive benchmarking and capability scorecards that compare product families on acoustic performance, motor technology, integration with heat pumps and controls, and serviceability. (High-resolution scorecards and raw benchmarking matrices are available in the full report.)
-
Commercial diligence modules for M&A and JV evaluations: valuation sensitivity, integration risk checklists, and value-creation playbooks specific to fan coils and terminal-unit portfolios.
-
Field-proven case studies and retrofit playbooks demonstrating payback timelines, service contract structuring, and specification edits that have materially improved conversion rates in commercial and multi-residential projects.
Competitive Landscape — Who’s Competing on What
The competitive field blends global conglomerates with regionally specialized manufacturers. Large HVAC OEMs maintain broad product ranges with integrated platform advantages and deep channel networks; they continue to compete on energy efficiency, controls integration, and scale-led cost management. At the same time, agile manufacturers are capturing specification-led niches — acoustics, low-profile horizontal units, hydronic specialty lines, and custom solutions for indoor-air-quality-focused projects.
-
Major global OEMs emphasize integrated system value and digital controls, offering variable-speed and ECM-equipped fan coils that are sold into large commercial portfolios and developer partnerships.
-
Specialized and regional vendors focus on acoustic performance, retrofit-fit geometries, and hydronic product lines that are easier to specify for renovation projects or constrained mechanical rooms.
-
Trade-show activity in early 2026 highlights a two-track innovation pattern: incremental portfolio expansion (hydronic and quiet-operation models) and tighter integration with heat pumps and building automation systems — a signal that manufacturers are aligning with end-users’ energy-efficiency and indoor-comfort priorities.
Recent vendor announcements and showcases illustrate momentum around hydronic range expansions, quiet-operation cassettes, and wall-mounted hydronic solutions — developments that are strategically important because they indicate where specification demand is concentrating. For buyers and OEMs this means watching product announcements for capability gaps rather than simply price.
Strategic Imperatives for 2026 Decision-Makers
From an implementation perspective, the 2026 planning cycle should be guided by five pragmatic imperatives:
-
Prioritize compliance-first product roadmaps. Incorporate AHRI performance and sound testing early in the development cycle to avoid late-stage rework and to facilitate premium positioning for low-noise and high-efficiency SKUs.
-
Design for cost and serviceability. Given commodity risk and rising steel costs, target modular designs that reduce assembly complexity, reduce scrap, and enable faster field service — converting product advantages into higher aftermarket revenue.
-
Fast-follower investments in motor and control tech. Variable-speed drives and ECMs are table stakes in many specifications; invest in embedded controls and open-protocol compatibility to win projects that require BMS integration.
-
Build retrofit-focused commercial offerings. A sizable portion of near-term demand will stem from renovation cycles; developing low-profile, noise-optimized retrofit kits and turn-key installation packages will materially improve conversion rates.
-
Adopt scenario-driven procurement. Use a range-based procurement strategy for 2026 raw material needs, with conditional hedges or framework agreements to insulate margin rather than chasing lowest-spot price.
How Executives and Investors Should Use This Intelligence
-
CEOs and product heads: Use the report to reshape product roadmaps around compliance and service-led differentiation, and to prioritize engineering resources for acoustic and control-system integration.
-
CFOs and procurement leaders: Apply the supply-chain stress tests and scenario model to lock in supplier agreements that protect margins while maintaining flexibility to scale.
-
Private equity and corporate development teams: Leverage the M&A diligence modules and benchmarking matrices to identify bolt-on targets with acoustic or hydronic capability that can be integrated into a scale platform.
-
Distributors and system integrators: Reassess inventory strategies and develop packaged retrofit offerings that reduce installation labor and accelerate adoption among building owners focused on occupant comfort and energy savings.
Next Steps — Where to Find the Data That Drives Decisions
This briefing is intentionally constructed as a high-fidelity trailer: it demonstrates the depth of analysis and operational focus of our full Fan Coils Market research while leaving the detailed segmentation tables, full competitive scorecards, and downloadable model inputs reserved for the complete report. The full deliverable contains all supporting datasets, configurable forecast models, supplier scorecards, primary-interview transcripts, and implementation tools that teams deploy directly into budgeting, product planning, and M&A workflows.
For leaders who must make concrete 2026 decisions—product investment, supplier contracting, M&A prioritization, or channel expansion—the full report provides the transaction-grade granularity and executable playbooks to move from strategic intention to measurable outcomes.
For detailed analysis of this topic, please visit the official page: Fan Coils Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Protocatechuic Acid Market to Reach USD 179.33M by 2032; 6.5% CAGR (PW Consulting)
By pmarketresearch, 2026-07-13
Protocatechuic Acid (CAS 99-50-3) Market — Strategic Outlook and Decision Playbook for 2026
Executive teaser
As industry leaders plan capital allocation, sourcing strategies, and product roadmaps for 2026, a clear, data-driven understanding of the Protocatechuic Acid (PCA) market is indispensable. PW Consulting’s newest market intelligence synthesizes historical performance, near-term inflection points, and actionable scenarios to inform corporate strategy. This introduction previews the analytical depth and practical outputs of the full study while intentionally withholding proprietary sub-segmentation tables and supplier-level volume data to encourage direct access to our complete intelligence.
Protocatechuic Acid (CAS 99-50-3) Market
Market snapshot and trajectory
PCA has evolved from a niche research chemical to a multi-application ingredient spanning pharmaceutical intermediates, nutraceuticals, specialty chemicals and premium cosmetics. Our base-year analysis (2025) confirms a robust expansion phase: the global market expanded from USD 83.5 Million in 2020 to USD 115.0 Million in 2025, and under the base-case assumptions grows at a compound annual growth rate (CAGR) of 6.5% through the forecast window. Under that trajectory the market is projected north of USD 125 Million in 2026, with mid-decade inflection points around 2030–2032 that reflect accelerating adoption in higher-margin end-uses and ongoing supply-side consolidation.
Protocatechuic Acid (CAS 99-50-3) Market
Why this study matters for 2026 corporate decisions
- Capital allocation: With predictable mid-single-digit growth, firms must decide whether to invest in incremental high-purity capacity or pursue capacity-light routes (toll manufacturing, licensing, or strategic partnerships) to preserve return on invested capital.
- Supply security: Diversification of sourcing and inventory strategies is now a value driver as buyers increasingly demand guaranteed ultra-high-purity streams for regulated pharmaceutical and cosmetic applications.
- Product and route selection: Competing production routes — classical organic synthesis, bio-based fermentation, and customized small-batch synthesis — each carry different risk/reward and margin profiles. Choosing the optimal route is a near-term strategic decision with multi-year implications.
- M&A and alliance prioritization: Fragmentation among manufacturers and the rise of specialized bio-process innovators create targeted acquisition and JV opportunities to secure technology, feedstock, or market access.
Core market dynamics
Three systemic factors define PCA’s commercial environment:
Protocatechuic Acid (CAS 99-50-3) Market
- Demand diversification: Historically concentrated in chemical intermediates and research reagents, PCA demand is broadening into nutraceutical and premium personal-care formulations. This shift favors suppliers capable of consistent, regulatory-compliant ultra-high-purity production.
- Supply innovation and sustainability: New bioprocess routes and plant-derived sourcing are emerging alongside established synthetic routes. Bioprocesses improve feedstock sustainability and attract buyers seeking green credentials, but they require scale-up investment and robust quality controls to meet pharmaceutical-grade expectations.
- Regulatory expectations and market access: PCA benefits from favorable listings—e.g., recognized status under certain food-substance inventories and REACH registration compliance—but pharmaceutical and nutraceutical applications impose exacting purity and process controls. For companies targeting regulated markets, alignment with FDA and EMA expectations around consistent ultra-high-purity production is non-negotiable.
Competitive landscape — strategic positions and implications
The supplier landscape is composed of long-tenured synthesis specialists, supplier-research houses, and innovative bio-based entrants. Market concentration remains modest, reflecting a fragmented field with distinct competitive sweet spots rather than a handful of dominant integrators.
- Taizhou Zhongda Chemical Co., Ltd. (China) — Established synthesis capabilities and deep manufacturing experience position this player well for pharmaceutical-intermediate contracts. Their manufacturing scale and packaging capabilities make them a natural partner for customers requiring reproducible supply agreements for active pharmaceutical ingredient (API) intermediates.
- Aktin Chemicals Inc. (China) — Focused on high-purity phytochemicals with GMP and non-GMP facilities, Aktin targets nutraceutical and API customers where quality systems and traceability materially affect purchasing decisions. Their dual-facility model supports both regulated and non-regulated demand streams.
- Green Chemicals Co., Ltd. (Japan) — A noteworthy innovator using modified coryneform bacteria and plant feedstocks to produce PCA via a proprietary bioprocess. Their renewable sourcing and application-focused R&D (e.g., specialty grades for UV-protection in skincare) signal an ability to capture premium segments where sustainability and performance converge.
- BOC Sciences (United States) — As a custom synthesis and biochemical service provider, BOC is strategically positioned for small-batch, application-specific supply and for customers requiring rapid analytical and formulation support. Their business model aligns with early-stage product developers and research-intensive users.
- Sigma-Aldrich (Merck) (United States) — The global reagent catalog and well-established quality systems make Sigma-Aldrich the reference supplier for laboratory and analytical-grade PCA. They remain the default for bench-scale research and regulatory-limited formulations that prioritize traceability and documentation.
- ExtraSynthese (France) — With decades of experience in natural substance synthesis, ExtraSynthese bridges traditional organic routes and specialized purification capabilities, catering to customers who require bespoke grades or small-to-medium scale contract production.
Together these players illustrate three viable go-to-market archetypes: high-volume synthesis incumbents, high-purity/regulatory-focused suppliers, and innovative bioprocess specialists. Each archetype carries different pricing power and margin dynamics.
Recent developments worth watching
- Green Chemicals’ launch of a specialty PCA grade optimized for UV protection underscores the trend toward application-tailored ingredients with integrated claims (performance + sustainability).
- Industry-wide forecast updates reflect accelerating interest from the pharmaceutical and nutraceutical sectors; this is driving premiumization in product specifications and rising demand for traceable, regulated supply chains.
- Regulatory positioning remains supportive at present—PCA’s listing statuses and REACH compliance lower regulatory entry friction—but adherence to pharmacopeial-like standards is increasingly expected by buyers.
What the PW Consulting report contains — practical, transaction-ready outputs
Our full study goes beyond high-level commentary to equip commercial teams, investors, and R&D leaders with concrete tools:
- Rigorous market-sizing and demand-modeling (2020–2032), with scenario variants that stress-test adoption curves across pharmaceutical, nutraceutical, specialty chemical and cosmetic segments.
- Supply-mapping and cost-to-serve frameworks that compare organic synthesis, bioprocess and custom-synthesis economics under multiple feedstock and regulatory scenarios.
- Supplier benchmarking and capability matrices covering quality systems, capacity flexibility, lead times, and compliance footprints — structured for procurement tender design.
- Regulatory and technical playbooks for ultra-high-purity production, including analytical control points, validation checklists, and route-to-market compliance sequences for FDA/EMA-regulated use.
- Commercial playbooks: pricing strategy, contract structures (JIT vs. safety stock), and partnership archetypes (tolling, JVs, strategic procurement alliances).
- Investment and M&A screening: prioritized target lists, valuation sensitivities tied to purity-grade mix, and integration risk checklists.
Note: To preserve the tactical value of our proprietary datasets, the report’s granular regional and application-level splits, supplier volumes, and tabulated unit-economics are accessible in the full downloadable version.
Strategic recommendations for 2026
For executive teams making decisions in 2026, PW Consulting recommends a three-track approach:
- Secure regulated supply first: For companies pursuing pharmaceutical or premium nutraceutical applications, prioritize agreements with suppliers that demonstrate consistent ultra-high-purity delivery and validated GMP pathways. Consider multi-sourcing across synthesis routes to mitigate feedstock or regulatory disruptions.
- Invest selectively in differentiation: If targeting premium personal-care or nutraceutical segments, invest in co-development with bioprocess innovators or suppliers that can deliver application-specific grades (e.g., UV-protection blends). These grades command margin premiums and customer loyalty.
- Design flexible capacity strategies: Use a mix of owned capacity, tolling agreements and long-term supply contracts to balance cost competitiveness and agility. For buyers, implementing quality-by-design procurement metrics reduces overpaying for unneeded specifications.
Scenario planning — three plausible paths through 2032
- Base case (6.5% CAGR): Demand grows steadily, with premiumization supporting margin expansion. Incremental capacity additions keep supply tight but balanced, enabling predictable contract negotiations.
- Accelerated adoption: Faster nutraceutical and cosmetic adoption of bio-based PCA variants fuels above-trend growth; premium grades see outsized price realization and attract venture and strategic capital into bioprocess scale-up.
- Downside / regulatory tightening: Stricter regulatory purity thresholds or feedstock constraints raise entry barriers, increasing premiums for compliant supply but reducing addressable volume for non-compliant producers. This scenario favors incumbent players with validated quality systems.
Conclusion — what action to take next
PCA’s transition from a research chemical to a commercially strategic ingredient creates clear windows for value capture in 2026 and beyond. Whether your objective is to secure regulated supply, pursue premium applications, or evaluate strategic acquisitions, the intelligence in PW Consulting’s full report translates market signals into executable choices. For procurement teams, R&D leaders, and M&A sponsors, the report provides the playbooks, vendor assessments, and scenario models necessary to make confident, defensible decisions.
Access to the complete dataset and the supplier-level analyses — including the granular regional and application splits omitted from this preview — is available through our report portal. PW Consulting stands ready to support custom advisory, supplier negotiations, and transaction diligence informed by this market study.
For detailed analysis of this topic, please visit the official page: Protocatechuic Acid (CAS 99-50-3) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pallet Pooling Rental Market to Reach USD 341.77M by 2032 at 6.9% CAGR — PW Consulting Insight
By pmarketresearch, 2026-07-13
Pallet Pooling (Rental) Market — A Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present this executive preview of our Pallet Pooling (Rental) Market study to help senior executives, procurement leaders, and logistics strategists calibrate decisions for 2026. This piece highlights the report’s strategic value, synthesizes the macro trajectory, outlines actionable playbooks, and profiles competitive dynamics — deliberately framed as a “trailer”: we expose the strategic implications and frameworks that matter, while reserving the granular segment-level figures for subscribers to the full report.
Pallet Pooling (Rental) Market
Why 2026 Is a Pivot Year
- Macro growth and momentum: The pooled pallet market has demonstrated consistent expansion through the 2020–2025 base period and enters 2026 on an accelerated trajectory. Measured in USD Million, total market value rose from the low hundreds in 2020 to roughly the mid‑two hundreds by the 2025 base year, and our 2026–2032 forecast anticipates continued growth to the mid‑three hundreds by 2032, reflecting a compound annual growth rate (CAGR) of approximately 6.9% over the forecast window.
- Regulatory inflection points: International phytosanitary standards (ISPM 15) remain enforced across global trade lanes, while regional circularity and producer‑responsibility initiatives are actively reshaping packaging rules and waste targets. These regulatory vectors materially change the TCO calculus for pooled versus owned pallets.
- Operational stress and optimization pressure: Ongoing supply‑chain volatility, rising inbound inspection scrutiny, and sustainability mandates are prompting manufacturers, retailers, and 3PLs to reassess asset strategies — turning pooled pallets from a cost optimization tactic into a strategic lever for resiliency and compliance.
Market Trajectory (Context, Not a Breakdown)
Understanding the overall size and growth rate is essential to prioritize investments. The market’s historical path and forecast illustrate a resilient, mid‑single‑digit CAGR growth environment, with accelerating adoption driven by environmental policy, logistics outsourcing trends, and technology‑enabled asset management. While this preview intentionally withholds granular sub‑segment figures, the directional signal is clear: total market demand will expand materially between 2026 and 2032, creating capacity and partnership opportunities for incumbent and new entrants alike.
Pallet Pooling (Rental) Market
What the Full Report Delivers — Practical, Transactional, Strategic
Our full study is built around decision‑ready outputs that procurement, supply‑chain, and sustainability teams can apply immediately. Highlights include:
Pallet Pooling (Rental) Market
- Actionable Total Cost of Ownership (TCO) models calibrated for trade lanes, pallet types (wood vs. plastic vs. alternatives), and return logistics — with sensitivity analysis for fuel, labor, and repair rates.
- Contract playbooks and pricing templates for rental and pooling agreements (term structures, damage recovery, reconciliation processes, service level agreements, and indemnities).
- Supplier scorecards and RFP frameworks to compare pooling providers on dimensions that matter: fleet quality, geographic reach, closed‑loop performance, repair network density, tracking capability, and sustainability credentials.
- Implementation guides and pilot blueprints — including metrics, sample KPIs, data collection templates, and integration checklists for WMS/ERP and IoT platforms.
- Scenario planning for regulatory and supply‑chain shocks, with contingency options and decision trees to preserve service levels and margin protection.
- ROI calculators for digital tracking and lifecycle extension programs, plus a carbon accounting module aligned with common reporting standards to quantify Scope 3 impacts from pooling choices.
Competitive Landscape — Strategic Positions and What They Mean for Buyers
The pooling market is commercially active but structurally fragmented. The top three suppliers account for under a quarter of the market, and the top five for roughly a quarter — a concentration profile that signals room for specialization, regional champions, and bespoke partnerships rather than a winner‑take‑all dynamic.
- CHEP (Australia) : The de facto global standard for closed‑loop wooden and plastic pooling. CHEP’s advantage lies in scale, network density, and mature reverse logistics. For multinational retailers and manufacturers seeking global consistency, CHEP remains the default strategic partner; negotiations should focus on service bundling and performance guarantees.
- Loscam (Australia) : Deep regional footprint across Asia‑Pacific and a recognized operator for intermodal flows. Loscam’s model suits firms prioritizing APAC supply‑chain continuity and local compliance expertise.
- PECO Pallet, Inc. (United States) : A North American specialist with emphasis on block pallet quality and service. PECO’s strengths are in regional responsiveness and tailored commercial terms for domestic distribution networks.
- iGPS Logistics LLC (United States) : A technology‑forward provider of sustainable plastic pooling, offering asset tracking and focused lifecycle management. iGPS is a strong match where traceability and plastic substitution strategies are primary objectives.
- Euro Pool Group (Netherlands) and Faber Halbertsma Groep B.V. (Netherlands) : European players focusing on food, beverage, and industrial customers with returnable packaging ecosystems and real‑time fleet visibility tools — attractive for companies seeking compliance with EU circularity goals.
- Demes Logistics (Germany) , Schoeller Arca Time (Italy) , and PPS Midlands (UK) : Regional specialists offering logistics efficiency, asset tracking, and tailored service models for manufacturing and distribution hubs in Europe.
- Contraload NV (Belgium) : Combines digital pooling platforms and IoT‑enabled tracking — a fit for enterprises prioritizing data‑driven asset control and performance analytics.
- Range International Limited (Australia) : Emerging player advancing zero‑waste plastic pallets (Re>Pal) for rental pools. Their March 2026 A$454,000 loan facility to expand fleet signals investor confidence in circular plastic propositions and offers a case study in fast follower scaling.
For decision‑makers, these profiles translate into a simple negotiation taxonomy: global integrators for scale and consistency; regional specialists for tailored service; tech‑first vendors for traceability and CO2 savings; and emerging entrants for disruptive sustainability propositions.
Regulatory and Standards Impact — Immediate and Medium‑Term
- ISPM 15 enforcement continues to govern solid wood packaging in international trade. Pooling providers that centrally control treatment and certification enjoy compliance advantages and lower border friction for customers moving pallets across jurisdictions.
- EU circularity targets and similar regional policies are accelerating adoption of reusable pools. Firms operating in or sourcing to Europe face increasing pressure to demonstrate packaging waste reductions and prefer pooling partners with auditable circularity metrics.
- Recent producer‑responsibility implementations (for example, state‑level EPR regimes) are changing the economics of wooden versus plastic pallets in some markets, nudging a subset of manufacturers and retailers toward plastic pooled solutions where wooden pallets are excluded from certain programs.
Top Risks and Mitigants for 2026
- Supply shocks and repair bottlenecks — mitigate through multi‑supplier sourcing and geographically distributed repair networks.
- Regulatory mismatches across trade lanes — mitigate by selecting pooling providers with proven compliance and phytosanitary capabilities.
- Hidden TCO components (reconciliation losses, relocation costs, damage recovery) — mitigate through rigorous contract SLAs, periodic audits, and embedded reconciliation tools supplied by vendors or third‑party auditors.
- Data integration challenges for IoT/tracking — mitigate with clear API standards and phased integration pilots linked to KPIs.
Practical 90‑Day and 12‑Month Playbooks for Executives
- 90‑Day Sprint: Run a targeted pilot on two strategic lanes. Define baseline TCO and carbon intensity, instrument pallets for visibility, and test supplier reconciliation and repair turnarounds. Use our RFP template to solicit standardized bids.
- 6–12 Months: Negotiate scalable contracts with indexation clauses for fuel and repair cost inflation, implement data feeds into WMS/ERP for real‑time utilization metrics, and establish an internal cross‑functional governance cell to monitor pooling economics and sustainability KPIs.
- 18–36 Months: Evaluate fleet composition optimization (wood vs. plastic), pursue strategic alliances with pooling providers that can deliver network density in priority geographies, and consider co‑investment models for shared pools in high‑volume corridors.
How This Report Supports 2026 Decisions
Executives need three things in 2026: clarity on true lifecycle cost, a defensible sustainability story, and operational options to de‑risk trade‑lane flows. Our study delivers the financial models, compliance frameworks, supplier benchmarking, and implementation tools to meet these needs. It turns abstract benefits — circularity, resiliency, and tracking — into quantifiable metrics you can assign to P&L and sustainability targets.
Next Steps and Access
This preview is designed to show the strategic signal and practical frameworks that matter in 2026. For granular regional and application splits, supplier scorecards, model inputs, and downloadable templates — including the full TCO spreadsheet and pilot blueprints — access to the complete PW Consulting Pallet Pooling (Rental) Market report is required. The full dataset contains the segmented revenue tables, scenario outputs, and supplier benchmarking that underpin the strategic recommendations summarized here.
Contact PW Consulting to schedule a briefing session where we will walk your leadership team through a tailored version of the study and run a live demo of the TCO and carbon calculators designed for direct application in RFPs and contracting negotiations.
For detailed analysis of this topic, please visit the official page: Pallet Pooling (Rental) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com