

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Protocatechuic Acid Market to Reach USD 179.33M by 2032; 6.5% CAGR (PW Consulting)

Protocatechuic Acid (CAS 99-50-3) Market — Strategic Outlook and Decision Playbook for 2026
Executive teaser
As industry leaders plan capital allocation, sourcing strategies, and product roadmaps for 2026, a clear, data-driven understanding of the Protocatechuic Acid (PCA) market is indispensable. PW Consulting’s newest market intelligence synthesizes historical performance, near-term inflection points, and actionable scenarios to inform corporate strategy. This introduction previews the analytical depth and practical outputs of the full study while intentionally withholding proprietary sub-segmentation tables and supplier-level volume data to encourage direct access to our complete intelligence.
Protocatechuic Acid (CAS 99-50-3) Market
Market snapshot and trajectory
PCA has evolved from a niche research chemical to a multi-application ingredient spanning pharmaceutical intermediates, nutraceuticals, specialty chemicals and premium cosmetics. Our base-year analysis (2025) confirms a robust expansion phase: the global market expanded from USD 83.5 Million in 2020 to USD 115.0 Million in 2025, and under the base-case assumptions grows at a compound annual growth rate (CAGR) of 6.5% through the forecast window. Under that trajectory the market is projected north of USD 125 Million in 2026, with mid-decade inflection points around 2030–2032 that reflect accelerating adoption in higher-margin end-uses and ongoing supply-side consolidation.
Protocatechuic Acid (CAS 99-50-3) Market
Why this study matters for 2026 corporate decisions
- Capital allocation: With predictable mid-single-digit growth, firms must decide whether to invest in incremental high-purity capacity or pursue capacity-light routes (toll manufacturing, licensing, or strategic partnerships) to preserve return on invested capital.
- Supply security: Diversification of sourcing and inventory strategies is now a value driver as buyers increasingly demand guaranteed ultra-high-purity streams for regulated pharmaceutical and cosmetic applications.
- Product and route selection: Competing production routes — classical organic synthesis, bio-based fermentation, and customized small-batch synthesis — each carry different risk/reward and margin profiles. Choosing the optimal route is a near-term strategic decision with multi-year implications.
- M&A and alliance prioritization: Fragmentation among manufacturers and the rise of specialized bio-process innovators create targeted acquisition and JV opportunities to secure technology, feedstock, or market access.
Core market dynamics
Three systemic factors define PCA’s commercial environment:
Protocatechuic Acid (CAS 99-50-3) Market
- Demand diversification: Historically concentrated in chemical intermediates and research reagents, PCA demand is broadening into nutraceutical and premium personal-care formulations. This shift favors suppliers capable of consistent, regulatory-compliant ultra-high-purity production.
- Supply innovation and sustainability: New bioprocess routes and plant-derived sourcing are emerging alongside established synthetic routes. Bioprocesses improve feedstock sustainability and attract buyers seeking green credentials, but they require scale-up investment and robust quality controls to meet pharmaceutical-grade expectations.
- Regulatory expectations and market access: PCA benefits from favorable listings—e.g., recognized status under certain food-substance inventories and REACH registration compliance—but pharmaceutical and nutraceutical applications impose exacting purity and process controls. For companies targeting regulated markets, alignment with FDA and EMA expectations around consistent ultra-high-purity production is non-negotiable.
Competitive landscape — strategic positions and implications
The supplier landscape is composed of long-tenured synthesis specialists, supplier-research houses, and innovative bio-based entrants. Market concentration remains modest, reflecting a fragmented field with distinct competitive sweet spots rather than a handful of dominant integrators.
- Taizhou Zhongda Chemical Co., Ltd. (China) — Established synthesis capabilities and deep manufacturing experience position this player well for pharmaceutical-intermediate contracts. Their manufacturing scale and packaging capabilities make them a natural partner for customers requiring reproducible supply agreements for active pharmaceutical ingredient (API) intermediates.
- Aktin Chemicals Inc. (China) — Focused on high-purity phytochemicals with GMP and non-GMP facilities, Aktin targets nutraceutical and API customers where quality systems and traceability materially affect purchasing decisions. Their dual-facility model supports both regulated and non-regulated demand streams.
- Green Chemicals Co., Ltd. (Japan) — A noteworthy innovator using modified coryneform bacteria and plant feedstocks to produce PCA via a proprietary bioprocess. Their renewable sourcing and application-focused R&D (e.g., specialty grades for UV-protection in skincare) signal an ability to capture premium segments where sustainability and performance converge.
- BOC Sciences (United States) — As a custom synthesis and biochemical service provider, BOC is strategically positioned for small-batch, application-specific supply and for customers requiring rapid analytical and formulation support. Their business model aligns with early-stage product developers and research-intensive users.
- Sigma-Aldrich (Merck) (United States) — The global reagent catalog and well-established quality systems make Sigma-Aldrich the reference supplier for laboratory and analytical-grade PCA. They remain the default for bench-scale research and regulatory-limited formulations that prioritize traceability and documentation.
- ExtraSynthese (France) — With decades of experience in natural substance synthesis, ExtraSynthese bridges traditional organic routes and specialized purification capabilities, catering to customers who require bespoke grades or small-to-medium scale contract production.
Together these players illustrate three viable go-to-market archetypes: high-volume synthesis incumbents, high-purity/regulatory-focused suppliers, and innovative bioprocess specialists. Each archetype carries different pricing power and margin dynamics.
Recent developments worth watching
- Green Chemicals’ launch of a specialty PCA grade optimized for UV protection underscores the trend toward application-tailored ingredients with integrated claims (performance + sustainability).
- Industry-wide forecast updates reflect accelerating interest from the pharmaceutical and nutraceutical sectors; this is driving premiumization in product specifications and rising demand for traceable, regulated supply chains.
- Regulatory positioning remains supportive at present—PCA’s listing statuses and REACH compliance lower regulatory entry friction—but adherence to pharmacopeial-like standards is increasingly expected by buyers.
What the PW Consulting report contains — practical, transaction-ready outputs
Our full study goes beyond high-level commentary to equip commercial teams, investors, and R&D leaders with concrete tools:
- Rigorous market-sizing and demand-modeling (2020–2032), with scenario variants that stress-test adoption curves across pharmaceutical, nutraceutical, specialty chemical and cosmetic segments.
- Supply-mapping and cost-to-serve frameworks that compare organic synthesis, bioprocess and custom-synthesis economics under multiple feedstock and regulatory scenarios.
- Supplier benchmarking and capability matrices covering quality systems, capacity flexibility, lead times, and compliance footprints — structured for procurement tender design.
- Regulatory and technical playbooks for ultra-high-purity production, including analytical control points, validation checklists, and route-to-market compliance sequences for FDA/EMA-regulated use.
- Commercial playbooks: pricing strategy, contract structures (JIT vs. safety stock), and partnership archetypes (tolling, JVs, strategic procurement alliances).
- Investment and M&A screening: prioritized target lists, valuation sensitivities tied to purity-grade mix, and integration risk checklists.
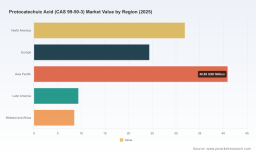
Note: To preserve the tactical value of our proprietary datasets, the report’s granular regional and application-level splits, supplier volumes, and tabulated unit-economics are accessible in the full downloadable version.
Strategic recommendations for 2026
For executive teams making decisions in 2026, PW Consulting recommends a three-track approach:
- Secure regulated supply first: For companies pursuing pharmaceutical or premium nutraceutical applications, prioritize agreements with suppliers that demonstrate consistent ultra-high-purity delivery and validated GMP pathways. Consider multi-sourcing across synthesis routes to mitigate feedstock or regulatory disruptions.
- Invest selectively in differentiation: If targeting premium personal-care or nutraceutical segments, invest in co-development with bioprocess innovators or suppliers that can deliver application-specific grades (e.g., UV-protection blends). These grades command margin premiums and customer loyalty.
- Design flexible capacity strategies: Use a mix of owned capacity, tolling agreements and long-term supply contracts to balance cost competitiveness and agility. For buyers, implementing quality-by-design procurement metrics reduces overpaying for unneeded specifications.
Scenario planning — three plausible paths through 2032
- Base case (6.5% CAGR): Demand grows steadily, with premiumization supporting margin expansion. Incremental capacity additions keep supply tight but balanced, enabling predictable contract negotiations.
- Accelerated adoption: Faster nutraceutical and cosmetic adoption of bio-based PCA variants fuels above-trend growth; premium grades see outsized price realization and attract venture and strategic capital into bioprocess scale-up.
- Downside / regulatory tightening: Stricter regulatory purity thresholds or feedstock constraints raise entry barriers, increasing premiums for compliant supply but reducing addressable volume for non-compliant producers. This scenario favors incumbent players with validated quality systems.
Conclusion — what action to take next
PCA’s transition from a research chemical to a commercially strategic ingredient creates clear windows for value capture in 2026 and beyond. Whether your objective is to secure regulated supply, pursue premium applications, or evaluate strategic acquisitions, the intelligence in PW Consulting’s full report translates market signals into executable choices. For procurement teams, R&D leaders, and M&A sponsors, the report provides the playbooks, vendor assessments, and scenario models necessary to make confident, defensible decisions.
Access to the complete dataset and the supplier-level analyses — including the granular regional and application splits omitted from this preview — is available through our report portal. PW Consulting stands ready to support custom advisory, supplier negotiations, and transaction diligence informed by this market study.
For detailed analysis of this topic, please visit the official page: Protocatechuic Acid (CAS 99-50-3) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com