

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Holter ECG Market to Expand at 7.52% CAGR (2026–2032) — PW Consulting

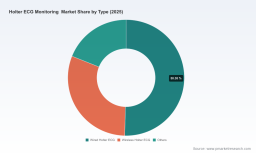
Holter ECG Monitoring Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
By the end of the base year (2025) the global Holter ECG monitoring market had solidified into a mature-but-growing segment of ambulatory cardiac diagnostics. Our PW Consulting baseline places 2025 market value and projects a steady compound annual growth rate (CAGR) of 7.52% across the 2026–2032 forecast window. Under this trajectory, the market expands meaningfully through 2032, driven by converging forces in device miniaturization, cloud-native analysis platforms, reimbursement clarity for extended monitoring, and an accelerating pipeline of regulatory-cleared wearable and patch technologies.
Holter ECG Monitoring Market
Why this research matters for 2026 corporate strategy
- Timing for portfolio bets: 2026 represents an inflection period where product investments made in 2024–25 begin to compete in volume and software integration. Companies that align R&D, regulatory and commercial teams now can capture share as the installed base upgrades to wireless, cloud-enabled systems.
- Go-to-market segmentation discipline: While headline growth is attractive, value is concentrated. Our analysis identifies where high-margin clinical interpretation services and software-as-a-service (SaaS) models sit relative to commoditized hardware — information that directly informs M&A and pricing decisions.
- Reimbursement arbitrage: Clarified CPT and Medicare dynamics for monitoring durations up to and beyond 48 hours make 2026 the year to optimize clinical pathways and coding strategies for ambulatory monitoring bundles.
- Regulatory and commercialization sequencing: With the FDA maintaining 510(k) pathways for many ambulatory systems and continued emphasis on post-market surveillance for Class II devices, strategic sequencing of clearances, labeling and claims will materially impact adoption velocity.
Market trajectory: What the headline numbers tell you
Over the historical base period (2020–2025) the sector demonstrated resilience and steady expansion. The market’s projected CAGR of 7.52% (2026–2032) underpins a multi-year growth runway — sufficient to support both organic growth strategies and selective bolt-on acquisitions. For 2026 planning, this level of growth implies predictable volume expansion for core hardware while creating outsized upside in software-driven interpretation, remote patient monitoring services, and extended-duration patch monitoring.
Holter ECG Monitoring Market
Report scope — pragmatic, action-oriented deliverables
This study is structured to convert market intelligence into executable actions. Key practical contents include:
Holter ECG Monitoring Market
- Methodology and transparent datasets covering the historical period (2020–2025) and forecasts to 2032 with scenario analyses reflecting conservative, base and accelerated adoption curves.
- Market sizing and topline forecasts (base year 2025) with sensitivity testing around pricing, reimbursement shifts and adoption timelines for wearable/patch systems.
- Commercial opportunity maps identifying high-return end-user segments, procurement cycles, and pricing benchmarks — presented as playbooks for sales and product teams.
- Regulatory and reimbursement compendium: a practical guide to relevant CPT code applications, Medicare local coverage considerations and FDA 510(k) requirements that affect time-to-market and claim packaging.
- Competitive landscaping with strategic profiles of incumbents and emerging challengers, including technology positioning, channel strategies and likely M&A targets.
- Operational benchmarking for OEMs and service providers: margins by business model (device sales vs. SaaS vs. interpretation services), deployment cost curves, and best-practice implementation checklists for clinical partners.
- Scenario-based playbooks for four strategic archetypes: incumbent OEMs, digital-native challengers, hospital systems/integrators, and specialized interpretation-service providers.
Competitive landscape — who matters and why
The competitive set spans legacy medical-device OEMs, device-focused regional players, and software-first incumbents. Market concentration indicates a meaningful share clustered among top players, creating an environment where scale and integrated service offerings matter.
- Large OEMs (platform and channel advantage): Global incumbents bring distribution scale, channel trust and integrated systems. Their priorities are incremental device innovation, backward compatibility, and embedding Holter data streams into broader cardiology informatics suites.
- Specialist device makers (cost and customization): Companies with focused Holter portfolios compete on device reliability, ease of use and local service economics. They are often first adopters of multi-lead and multi-modality recording within regional hospitals and ASC networks.
- Digital-native challengers (software-first disruption): Cloud-native interpretation platforms and patch-based continuous monitors are redefining care pathways. Rapid FDA clearances for end-to-end digital platforms have shortened the route from device deployment to revenue recognition for recurring interpretation services.
Prominent firms analyzed in the report include long-standing OEMs and several high-impact challengers. For corporate strategists, the decision levers are clear: secure clinical validation and reimbursement pathways for new modalities; decide whether to vertically integrate interpretation services or partner with third-party platforms; and prioritize channel investments where adoption is velocity-driven.
Recent regulatory and product developments shaping 2026 adoption
- Several FDA 510(k) clearances in the 2024–2025 window for cloud-native and wireless ambulatory systems have lowered technical barriers to market for new entrants and enabled faster clinical workflows for retrospective analysis.
- U.S. reimbursement frameworks continue to recognize discrete CPT pathways for short and extended-duration external monitoring, with local coverage determinations affirming codes for up to 48 hours and additional codes for monitoring beyond 48 hours. This clarity increases the commercial predictability for extended-monitoring products in clinical pathways such as post-stroke arrhythmia surveillance.
- Regulatory emphasis on post-market surveillance for Class II ambulatory monitors elevates the importance of robust QA, real-world performance data and documentation — a differentiator for vendors with established clinical registries.
Technology and clinical trends to watch
- Patch and single-lead continuous monitoring: Adoption is accelerating where patient comfort, adherence and remote workflows reduce clinic visits. These solutions also enable subscription-based interpretation models.
- AI-assisted interpretation: Cloud-native analytics and validated algorithms are reducing turnaround times for Holter interpretation, enabling near-real-time triage of critical arrhythmias and more scalable interpretation services.
- Hybrid hardware-software business models: Expect more vendors to bundle devices with recurring software and interpretation fees — shifting revenue mix and margin profiles across the industry.
- Integration into care pathways: Hospitals and ambulatory centers increasingly demand end-to-end interoperability with EHRs and cardiac care orchestration platforms, making open APIs and standards compliance commercial prerequisites.
Strategic implications and practical recommendations for 2026
- For incumbents: Prioritize software partnerships or acquisitions that accelerate cloud interpretation capabilities and create recurring revenue streams. Protect installed base through upgrade pathways rather than forcing hardware swaps.
- For challengers and startups: Focus on niche clinical claims where patch or AI advantages produce defensible adoption barriers. Invest early in FDA evidence generation and payer engagement to avoid commercialization delays.
- For hospital systems and ASCs: Negotiate bundled service agreements that align device procurement with interpretation and telemetry services to lower per-patient monitoring costs and ensure coding compliance.
- For investors: Target companies with a clear SaaS monetization path, validated clinical performance and exposure to extended-duration monitoring use cases, which show higher willingness-to-pay.
What you won’t find here — and why you should read the full report
This preview intentionally omits detailed segmentation tables and granular regional/application breakouts that materially influence go-to-market tactics. The full PW Consulting Holter ECG Monitoring Market report contains the granular splits, pricing matrices, detailed competitor benchmarking, and proprietary channel economics that operational teams need to execute with confidence. Those datasets are essential for building precise sales forecasts, negotiating distributor agreements, and sizing acquisition targets.
How to use this research in your 2026 planning cycle
- Align product roadmaps to the identified technology inflection points (patch adoption, AI interpretation, EHR interoperability).
- Map reimbursement windows to launch timelines so device claims and coding enable immediate revenue capture upon commercialization.
- Use the scenario models in the full study to stress-test M&A targets and validate payback periods for R&D investments under different adoption speeds.
- Leverage competitive profiles to identify white-space opportunities where incumbents are weak (e.g., cloud-native interpretation, integrated chronic care bundles).
Closing — a strategic invitation
As 2026 approaches, the Holter ECG monitoring market offers a blend of steady growth and targeted disruption. The headline CAGR and forecast trajectory indicate reliable topline expansion, but the real value lies in the details: product claims, reimbursement sequencing, clinical validation and channel economics. PW Consulting’s full report provides those actionable datasets and strategic playbooks — the essential inputs for executives deciding where to invest, partner or divest in the coming 18–36 months. For the complete intelligence suite and executable scenarios, access the full report.
For detailed analysis of this topic, please visit the official page: Holter ECG Monitoring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com