

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Azimuth Thrusters Market to reach $610.3M by 2032 at 1.49% CAGR — PW Consulting

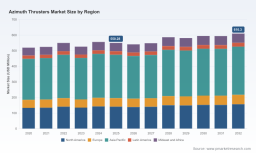
Azimuth Thrusters Market: Strategic Brief for 2026 Decision-Makers
Executive summary
The azimuth thrusters market remains a specialist but strategically important segment of marine propulsion, with a market size that has gravitated around USD 550 million in the mid‑2020s. Using 2025 as the base year, our forecast through 2032 projects a moderate expansion to roughly USD 610 million, reflecting a compound annual growth rate (CAGR) of approximately 1.49% over the 2026–2032 horizon. That growth masks persistent volatility across the prior half‑decade and divergent dynamics by vessel type, propulsion architecture, and regional demand drivers.
Azimuth Thrusters Market
For executives preparing 2026 plans, this market sits at the intersection of decarbonization ambition, tougher electrical and acoustic standards, and tightening upstream material controls. Those forces create both constraint and opportunity: vendors and buyers who align product roadmaps, supply‑chain strategies, and certification roadmaps will capture disproportionate value, while laggards face margin compression and delivery risk.
Azimuth Thrusters Market
Why this research matters for decisions in 2026
-
Timing capital allocation: With a low-single-digit CAGR and limited upside in the near term, investment decisions must prioritize R&D and retrofit solutions that improve lifetime economics (fuel/electricity consumption, maintenance intervals) rather than betting on rapid volume expansion.
Azimuth Thrusters Market -
Product roadmap prioritization: New electrical control certifications (UL 3141, UL 1741) and ISO efficiency/noise mandates mean that product delays are costly. Companies should sequence feature development to secure early certification and first‑mover trust in niche applications (e.g., dynamic positioning, ice operations).
-
M&A and partnership calculus: The market concentration metrics show a moderately consolidated supplier base. Strategic bolt‑ons that fill capability gaps (rim‑drive expertise, retractable mechanisms, power electronics) deliver faster route‑to‑market than greenfield scaling.
-
Supply‑chain resilience: Export controls on critical materials and wage inflation for specialized labor demand near‑term hedging—longer lead times for titanium or rare earth magnets will affect new builds and retrofit schedules.
How to read the high‑level data
Our report uses 2025 as the base year and tracks historical performance from 2020–2025. The path to 2032 reflects scenarios calibrated to demand in key marine segments and the evolving regulatory landscape. The headline figures show mid‑decade stabilization followed by measured growth to ~USD 610 million by 2032 at a 1.49% CAGR. The story behind those numbers is heterogenous: certain vessel classes and propulsion architectures expand faster, others are constrained by capex cycles and supply friction. The report surfaces those drivers without exposing proprietary segmentation data in this preview—download the full dataset for granular regional and application breakdowns.
Report contents — what the full study delivers
-
Market sizing and scenario models: transparent assumptions and sensitivity analyses that let you re‑run forecasts under alternate oil price, regulatory, and supply‑shock scenarios.
-
Go‑to‑market playbooks: commercial strategies tailored for OEMs, system integrators, and shipowners—covering pricing levers, warranty models, and aftermarket services packaging.
-
Supplier scorecards and capability matrices: comparative assessments across design, manufacturing depth, certification maturity, and aftermarket network—presented to inform procurement and M&A diligence.
-
Regulatory and standards impact analysis: practical interpretation of UL and ISO developments and checklist‑style guidance for compliance sequencing across electrical and acoustic subsystems.
-
Cost‑to‑serve and lifecycle economics: OPEX/CAPEX modeling that isolates where efficiency gains or electrification premium pay back under different operating profiles.
-
Risk registers and mitigation playbooks: supply‑chain hedges, sourcing alternatives, and workforce strategies for specialized marine engineering labor.
Competitive landscape — what to watch in 2026
The market exhibits moderate concentration: the top three players control a majority share (CR3 ~55%), with the top five reaching around 65% (CR5 ~65%). That structure favors established vendors with deep engineering benches and global service footprints. Our competitive review highlights product differentiation vectors and strategic moves you should monitor.
-
Kongsberg Maritime (Norway): A technology leader in rim‑drive solutions and high‑voltage permanent magnet platforms. Recent product introductions continue to push the boundaries on shallow‑draft and DP‑capable rim drives; expect Kongsberg to lean into electrified ferries and offshore support sectors.
-
SCHOTTEL Group (Germany): Strong heritage in Z‑drive and L‑drive architectures with broad OEM relationships. SCHOTTEL’s portfolio and marine service network make it a go‑to supplier for conventional commercial vessels and retrofit programs.
-
ZF Marine (Germany): Fast follower with recent AT series launches. ZF’s product refresh cadence signals focus on modularity and simplified integration for shipyards—key when vessel yards manage compressed build schedules.
-
Thrustmaster of Texas (United States): Known for heavy‑duty, high‑power units and configurable propeller arrangements. Their catalogue updates show emphasis on deck‑mounted and mini‑skid solutions for offshore and escort applications.
-
Brunvoll AS & Steerprop (Nordic specialists): Niche innovators—Brunvoll in retractable units for energy‑sector vessels and Steerprop in ice‑class designs. These suppliers win when performance under extreme conditions matters more than unit price.
-
Voith, Veth (Twin Disc), Wärtsilä, Kawasaki, Niigata, IHI: Each plays to specific strengths—whether inline swing designs, shallow‑draft packages for yachts, or high‑reliability systems for riverine and harbor operations. Expect continued role specialization rather than broad convergence.
Recent market signals to track: product launches (e.g., new AT Series and rim‑drive releases), targeted contracts for ocean energy and support vessels, and catalog refreshes emphasizing retractable and compact azimuth units. These moves reflect both tactical replacement demand and longer‑term positioning for electrification and offshore support growth.
Supply chain, regulation and geopolitical dynamics
-
Raw materials and export controls: Controls on titanium and rare earth exports have increased procurement costs and lead times—forcing OEMs to either redesign with alternative alloys or build inventory cushions. Scenario planning for material black‑swan events is now a required line item in procurement forecasts.
-
Standards and certification: New UL certifications for electrical control systems and tighter ISO mandates on efficiency and acoustic emissions raise the compliance bar. Incorporating certification timelines into product launch schedules is essential to avoid market access delays—especially for US and EU flag projects.
-
Labor and manufacturing capability: High‑power rim‑drive and precision titanium blade fabrication require specialized labor. Wage inflation in key manufacturing clusters increases variable costs and shifts the advantage toward firms with automated machining or diversified manufacturing footprints.
Actionable recommendations for executives (2026 planning cycle)
-
Prioritize retrofit and digital services: With fleet renewal slow, aftermarket services and retrofit offers (efficiency upgrades, digital remote diagnostics) deliver quicker ROI and build sticky customer relationships.
-
Lock in certification roadmaps: Start certification programs (UL, ISO) 12–18 months ahead of commercial launch. Allocate cross‑functional resources to anticipate test failures and iterative design changes.
-
De‑risk raw material sourcing: Pursue multi‑sourcing, alternative materials testing, and strategic inventory positions for critical inputs. Where possible, negotiate long‑term offtake or toll‑processing arrangements with suppliers.
-
Consider focused M&A: Target bolt‑on acquisitions that add rim‑drive, retractable mechanisms, or power electronics IP rather than chasing broad geographic expansion. Acquisitions that expand aftermarket presence are particularly accretive.
-
Invest in modular integration: Standardize interfaces (mechanical, electrical, control APIs) to reduce shipyard integration risk and accelerate certification reuse across platforms.
Decision frameworks included in the full study
The report supplies decision tools you can operationalize immediately: NPV and payback templates tailored to thruster retrofit vs newbuild scenarios; a supplier resilience heatmap; a regulatory compliance tracker; and a three‑layer product roadmap template linking R&D investment to certification milestones and go‑to‑market windows. These frameworks are populated with scenario inputs and benchmarking ranges so teams can run rapid sensitivity tests aligned to corporate risk appetite.
Next steps and how to use the full report
Use the full study to ground FY‑2026 budget discussions, set 3‑year product investment priorities, and align procurement strategies across marine and offshore portfolios. This preview highlights the strategic contours—supply friction, certification timetables, and concentrated competition—that will determine winners and losers. For access to the complete datasets, regional/application splits, supplier scorecards, and the downloadable Excel models, please visit the published report page. The detailed segmentation tables and scenario model are intentionally gated to preserve commercial value and provide your team with the practical tools needed to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Azimuth Thrusters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com