

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gallic Acid Market to Reach $348M by 2032 at 6.8% CAGR

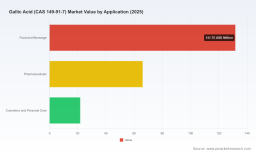
Gallic Acid (CAS 149-91-7) Market — 2026 Strategic Preview
As firms set 2026 priorities against an increasingly volatile raw-material and regulatory backdrop, Gallic Acid has emerged from a niche reagent into a strategically relevant ingredient across food & beverage, pharmaceutical, and personal care value chains. PW Consulting’s latest study (base year 2025) models the market as a structurally growing opportunity: the addressable global market expands from a 2025 baseline of USD 219.6 Million to an anticipated USD 348.04 Million by 2032, reflecting a compound annual growth rate of 6.8% across the 2026–2032 forecast window. This preview synthesizes the report’s high-level implications for corporate decision‑makers in 2026 — demonstrating the type of analytical depth contained in the full publication while reserving the granular segmentation tables that drive transactional action.
Gallic Acid (CAS 149-91-7) Market
Why this market matters to 2026 strategy
-
Cross-sector demand maturation: Gallic Acid’s role has broadened from laboratory reagent to multifunctional ingredient — an antioxidant, preservative, intermediate for API development, and formulation aid in cosmetics. This cross-sector adoption moderates cyclicality but also raises exposure to diverse regulatory regimes and quality expectations.
Gallic Acid (CAS 149-91-7) Market -
Sourcing risk and price elasticity: Production remains anchored in agricultural-derived feedstocks (e.g., tara pods, gallnuts, sumac), so availability and cost are sensitive to climatic variability and crop yields. Suppliers that can de-risk feedstock pipelines or offer vertically integrated bioproduction models will command strategic advantage.
Gallic Acid (CAS 149-91-7) Market -
Standards-driven segmentation: Demand bifurcates by quality and certification requirements — commodity industrial supply versus USP/EP pharmaceutical grades and certified reference materials for analytical use. Quality premiums and buyer willingness to pay vary significantly by application.
-
Consolidation and concentration: Market concentration is meaningful — the top three players collectively control a substantial portion of supply, with the top five exerting an even larger share. This concentration shapes negotiation dynamics and validates both defensive and acquisitive strategies for mid‑sized suppliers and purchasers.
What PW Consulting’s full study delivers (practical components)
-
Proprietary demand model (2020–2032): scenario-ready projections by application class and end-use verticals, designed to be plugged into capex and procurement planning tools.
-
Supplier landscape and heatmap: verified production capacities, ISO/USP/EP certification status, geographic footprint, and export lanes — accompanied by a supplier scorecard that rates technical competence, compliance risk, and commercial responsiveness.
-
Price and margin framework: mechanistic drivers linking feedstock cost shocks, conversion yields, and contract structures to finished-product price trajectories under multiple market stress scenarios.
-
Regulatory and quality playbook: a checklist and implementation roadmap for meeting pharmaceutical (USP/EP) and food-safety requirements, including documentation, audits, and analytical benchmarks.
-
Go-to-market playbooks for suppliers and buyers: differentiated strategies for industrial, food & beverage, pharmaceutical, and cosmetic customers, with tailored channel, pricing and certification recommendations.
-
M&A and partnership scanner: valuation heuristics, integration risks, and target profiles for bolt-on acquisitions or technology partnerships (e.g., fermentation/bioprocessing) to secure predictable supply and higher margins.
-
Executive dashboards and procurement templates: condensed KPIs for quarterly decision cycles, supplier scorecards, and stress-test scenarios for negotiation and contingency planning.
Supply-side dynamics: risks, defensive moves, and innovation
Raw-material volatility remains the dominant near-term supply risk. Where historical suppliers lean on agricultural feedstocks, atypical weather patterns materially affect both availability and unit economics. In response, we see two structural responses emerging: (1) vertical integration and onshoring of key production steps, and (2) investment in bioprocess routes that decouple production from seasonal feedstock flows.
Merck KGaA’s January 2024 non-binding memorandum with Mycenax Biotech is emblematic of the second response: strategic partnerships that target bioprocess scaling and lifecycle control for life-science ingredients. Companies with R&D capacity and downstream quality systems that can deliver USP/EP-compliant material through either traditional extraction or fermentation will be advantaged — both in price stability and in premium markets that prize traceability and reproducibility.
For buyers, defensive sourcing strategies should prioritize supplier diversification across production technologies and regions, dual-sourcing contracts with pre-negotiated price bands, and working-capital structures that absorb seasonality without passing unnecessary cost to end markets.
Demand-side trends and customer segmentation
End users are not homogeneous. Food & beverage formulators increasingly demand “clean‑label” natural antioxidants, favoring suppliers with verifiable traceability and sustainability claims. Pharmaceutical purchasers, by contrast, prioritize compliance and batch-to-batch reproducibility, creating a high-margin niche for USP/EP‑certified producers. Academic and industrial research demand continues to support a parallel market for certified reference materials and high‑purity grades used in analytical contexts.
Strategic takeaway for 2026: segment your customer outreach and pricing strategy to reflect the distinct willingness-to-pay and compliance burdens of each buyer cohort. Investments in certifications and batch-release analytics will pay dividends in regulated channels, while cost-to-serve optimization remains critical for high-volume industrial purchasers.
Competitive landscape — tactical implications
-
Merck KGaA / Sigma-Aldrich: A vertically integrated, reputation‑led supplier focusing on pharmaceutical-grade material and certified reference standards. Their scope and certification depth make them the go-to for regulated buyers; competitors should not attempt to win those accounts on price alone but can target responsiveness, bespoke supply agreements, and local warehousing as differentiators.
-
Gallochem Co., Ltd. & TNJ Chemical: Represent cost-competitive, scale-driven supply from China, targeting food, beverage and industrial applications. These suppliers compete on price and availability; buyers seeking low-cost nodes should implement rigorous QC and supplier‑audit protocols to manage quality drift risk.
-
Cayman Chemical & MedChemExpress: Specialists in high‑purity and certified reference materials for research and analytical use. Their strategies underscore the value of reputation and certification in premium niches — an important model for any supplier seeking to move up the value chain.
-
CDH Fine Chemical & Tokyo Chemical Industry: ISO‑certified exporters with broad distribution networks, supporting global laboratories and industrial customers. They illustrate the strategic edge of combining manufacturing competence with global logistics and regulatory support.
Across these competitors, the market is neither fully fragmented nor fully consolidated — creating room for ambitious mid-market players to scale through targeted investments in certification, traceability, and selective capacity expansions.
Priority strategic actions for 2026
-
Conduct a supplier risk audit Q1–Q2 2026 focused on feedstock exposure, certification gaps, and single‑source dependencies.
-
Lock in hybrid sourcing contracts that combine spot and volume commitments with index-linked price collars to limit upside risk while preserving supply flexibility.
-
Prioritize investment in certification (USP/EP) if targeting pharmaceutical channels; for consumer-facing applications, build traceability and sustainability claims that can command a premium.
-
Evaluate bioprocessing partnerships or minority investments in fermentation capacity as a hedge against agricultural volatility and as a route to predictable unit economics.
-
For investors: screen targets not only by revenue but by certification depth, geographic diversification, and feedstock control — these attributes materially affect valuation under stress scenarios.
-
Revise R&D roadmaps to exploit gallic acid derivatives and high-value formulations; small technical shifts can unlock step-changes in margin.
How to use this intelligence in your 2026 decision calendar
Early 2026: complete high-priority supplier audits and define risk-adjusted sourcing budgets. Mid 2026: finalize certification investments and test pilot partnerships in bioprocessing. Late 2026: activate M&A or JV diligence if capacity or technology gaps remain. Throughout 2026: monitor feedstock indices and regulatory updates; use the PW Consulting dashboards to translate macro scenarios into P&L and working-capital impacts.
Final note — the strategic value of the full PW report
This preview outlines the directional implications and high‑level recommended actions for 2026. The full PW Consulting report contains the granular models, supplier scorecards, validated capacity tables, and scenario P&L outputs that operational teams need to execute on these strategies. We deliberately withhold the detailed segmentation tables in this public preview — the most actionable intelligence (e.g., regional and application-level breakdowns, supplier capacity by grade, and contract-level price sensitivity analyses) resides in the full report and dashboards available through our client portal.
If your 2026 plans involve securing ingredient continuity, moving up the value chain into regulated channels, or making targeted acquisitions, this report is designed to be the analytical backbone for those decisions. PW Consulting’s Gallic Acid market study translates market dynamics into executable steps — from procurement playbooks to M&A checklists — so that you can make decisions in 2026 with conviction and evidence-backed downside protection.
For detailed analysis of this topic, please visit the official page: Gallic Acid (CAS 149-91-7) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com