

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ionomer Market Set for 6.5% CAGR to 2032

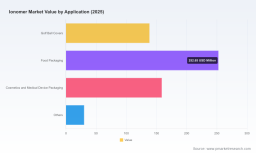
Ionomer Market — Strategic Preview for 2026 Decision-Making
As companies prepare plans and capital allocations for 2026, the ionomer market presents a technically nuanced, commercially meaningful opportunity — and a set of operational risks that can materially affect margins and time-to-market. This preview synthesizes the high-level findings from PW Consulting’s Ionomer Market study (base year: 2025; historical scope: 2020–2025; forecast horizon: 2026–2032) to help executives and investors prioritize choices. We demonstrate the analytical depth behind our work while reserving the granular segmentation tables and model outputs for the full report on our site.
Ionomer Market
Market trajectory at a glance
Through 2020–2025 the ionomer market experienced steady expansion from a modest base, with a notable plateau in the mid-period before renewed momentum into 2025. Measured in USD Million (base year 2025), the market reached a mid‑hundreds level by 2025 and is projected to continue expanding through the 2026–2032 forecast window. Our baseline forecast assumes a compound annual growth rate (CAGR) of 6.5% across 2026–2032, reflecting steady demand growth from packaging and specialty end‑uses together with ongoing product innovation that uplifts average selling prices and application penetration.
Ionomer Market
Two observations from the time series are especially important for 2026 planning: first, the market has shown resilience after a temporary demand plateau; second, the coming multi‑year growth is substantial enough that strategic choices made in 2026 — on sourcing, capital allocation, and product positioning — will determine relative competitive standing through the late 2020s.
Ionomer Market
What is driving growth — and what to watch
- End‑use demand mix. Ionomers continue to serve a cross‑section of applications from premium consumer goods to performance packaging and select industrial uses. Innovation in barrier, clarity and tactile properties is enabling ionomers to displace or augment alternatives in high‑value packaging and specialty consumer segments.
- Product premiumization and formulation shifts. Higher‑performance ionomer grades and tailored blends are commanding price and specification premiums. This dynamic supports revenue growth beyond simple volume expansion.
- Regulatory and tariff shocks. Regulatory measures and trade policy are increasingly important near‑term variables. Examples include new registration regimes in major production geographies and recently announced tariff measures affecting resin imports — all of which affect supplier selection and landed costs.
- Feedstock and raw‑material volatility. Feedstock price volatility feeds directly to resin margins. Case in point: an industry reference for ionomer pricing in hydrogen fuel‑cell systems highlights a substantive per‑kilogram cost at modest production scale; more broadly, crude price shocks and potential supply disruptions continue to accelerate feedstock cost pass‑through.
Supply dynamics and cost risk
Our analysis puts supply‑side dynamics at the core of 2026 decisions. Key points:
- Raw material economics are a primary driver of short‑term margin pressure. Public data points and technical cost models indicate that specialized ionomer grades can be costly to produce at small scale and sensitive to feedstock swings. Procurement strategies and contract terms need to reflect this reality rather than assuming stable input prices.
- Regulatory compliance costs are rising. New chemical registration requirements in major production markets require capital and operating expenditures to meet compliance timelines. These costs are uneven across producers and tend to re‑rank supplier competitiveness in procurement RFPs.
- Trade measures and logistics risk are material. Recent tariff moves that affect resin imports have created near‑term landed cost uplifts for affected supply chains. Geopolitical events that threaten critical maritime chokepoints further raise the case for redundancy in supply and for scenario planning in 2026 budget cycles.
Competitive landscape — how incumbents are positioned
The market structure is characterized by a mix of integrated global majors, regional producers, specialty formulators and international distributors. Market concentration metrics indicate that the leading three suppliers account for a meaningful plurality of demand, while the top five approach a clear majority — a structure that creates scale advantages but leaves room for regional players and specialty suppliers to prosper where technical differentiation or local service matters.
- Global integrated producers. Established polymer majors with global manufacturing footprints (e.g., Dow Inc., E. I. du Pont de Nemours and Company, ExxonMobil, Solvay, LyondellBasell) benefit from scale, proprietary grades and extensive channel relationships. Their ability to bundle upstream feedstock procurement and downstream technical service is a decisive competitive edge in several high‑value applications.
- Specialty and regional producers. Companies such as Asahi Kasei, Kuraray, LG Chem and selected Chinese producers combine technical depth with closer customer proximity in key growth markets. These firms often win on local responsiveness, tailored formulations and competitive pricing where logistics or regulatory advantages apply.
- Distributors and formulators. Channel players and specialty formulators (distributors and smaller specialty manufacturers) play an outsized role in converting base ionomers into application‑ready solutions, enabling OEMs and converters to accelerate time‑to‑market without heavy CAPEX.
For 2026 strategy, the implication is clear: scale, proprietary technology and integrated supply chains will define winners at the national and global levels, but targeted investments in formulation, local capacity and regulatory compliance will open corridors for challengers.
Strategic choices for 2026 — an action checklist
Executives should treat 2026 as a pivotal planning year. Key, actionable priorities derived from our study:
- Sourcing resilience. Build dual‑sourced supply chains and include explicit pass‑through and indexation clauses in long‑term contracts to manage feedstock volatility.
- Hedging and procurement sophistication. Use a mix of physical hedging, financial hedges and option provisions for sensitive grades; run quarterly stress tests against price spikes and tariff shocks.
- Localized manufacturing and inventory strategy. Where regulatory or logistical risk is high, evaluate near‑market capacity or toll‑manufacturing partnerships to reduce lead times and landed‑cost exposure.
- R&D and product roadmap alignment. Prioritize low‑cost, high‑performance formulations that lower total system cost for customers; build portfolio choices that allow premium capture in differentiated applications.
- Commercial and contractual repositioning. Revisit pricing architecture, minimum off‑take clauses and force‑majeure language to reflect evolving trade and feedstock risks.
- M&A and JV readiness. Use 2026 to prepare playbooks for opportunistic M&A: target regional capacity, specialty formulation capabilities, or backward integration into key feedstocks.
- Regulatory compliance planning. Budget for registration and testing timelines; align product launches with compliance milestones in major markets.
- Customer segmentation and value capture. Resegment your customers by value‑to‑you rather than by volume alone, and deploy differentiated service and formulation bundles accordingly.
What the PW Consulting report delivers (practical components)
The full Ionomer Market study is designed as a working document for commercial and strategic teams. Key deliverables include:
- Granular, bottom‑up market sizing and demand model (historical and forecast periods) with downloadable model access and scenario toggles.
- Supply‑chain mapping for major grades and geographies, including capacity maps, lead times and logistics cost drivers.
- Price and margin sensitivity analysis under alternative feedstock and tariff scenarios.
- Regulatory impact matrix and compliance roadmaps for key jurisdictions.
- Competitive benchmarking with capability matrices, SWOT summaries and commercial positioning for lead suppliers.
- Practical go‑to‑market playbooks for product launches, conversion wins, and distributor partnerships — including contract archetypes and negotiation levers.
- M&A screening framework and a short‑list of target archetypes (methodology and scoring; individual target data supplied in the full report).
- Primary interview syntheses and supplier call logs that underpin our market intelligence.
To preserve the strategic value of the analysis for our subscribers, the full report contains the detailed regional, type and application split tables, precise price ladders and downloadable forecast models. The excerpts above are intended to orient decision‑makers and highlight the areas where our proprietary data materially changes choices for 2026.
Near‑term scenarios and recommendations
We stress‑test three plausible 2026 scenarios in the full study — baseline growth, elevated cost stress (tariffs + feedstock spike), and accelerated premium adoption — each with actionable triggers for when to implement specific procurement, investment or commercial moves. For most firms, a hybrid approach is optimal: maintain flexibility in sourcing and contracts while selectively accelerating investments in differentiated grades and regional service capability.
Immediate recommended actions for leadership teams preparing 2026 plans:
- Run a rapid vulnerability audit of your ionomer exposure (by grade and supplier) and quantify P&L sensitivity to a 10–30% feedstock cost shock.
- Initiate conditional supply agreements with at least two qualified suppliers in different trade zones, including explicit tariff contingency language.
- Prioritize a pilot program for premium formulations with one lead customer to validate pricing power and incremental margin potential.
- Allocate a modest M&A watchlist budget and shortlist 2–3 regional targets that would materially de‑risk logistics or regulatory exposure.
Closing — why 2026 matters
Market dynamics are aligning such that choices made in 2026 — on sourcing structure, product differentiation and regulatory compliance — will determine whether firms secure durable margin expansion or simply endure cyclical pressures. PW Consulting’s Ionomer Market study is designed to convert macro signals into practical, executable plans. For executives who require the full model, detailed segment tables, and supplier‑level economics that underpin our recommendations, the full report and supporting datasets are available on our website.
Contact PW Consulting to schedule a briefing and receive the model license and proprietary annexes that will enable your 2026 strategy team to move from scenario to action with confidence.
For detailed analysis of this topic, please visit the official page: Ionomer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com