

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Engine Nacelle Market to Reach USD 844.28M by 2032 at 5% CAGR

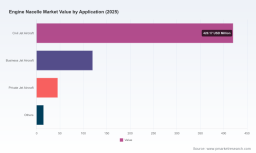
Engine Nacelle Market: Strategic Preview for 2026 Decision-Making
Executive preview
As PW Consulting’s Chief Industry Analyst, I present a focused, forward-looking synopsis of our Engine Nacelle Market study — a decision-grade briefing designed to influence capital allocation, partnership strategy, and product roadmaps in 2026. The global nacelle market is recovering and structurally evolving: after a five-year historical window marked by pandemic-related disruption and a mid-cycle dip, total industry revenues reached approximately USD 600 Million (base year 2025) and are projected to expand at a compound annual growth rate (CAGR) of about 5.0% through our 2026–2032 forecast horizon. That trajectory lifts the market toward the high USD 800 Millions by 2032 under our central scenario.
Engine Nacelle Market
Why this matters to corporate leaders in 2026
-
Timing of investment. The market’s steady 5% CAGR and the short-term rebound between 2024–2026 create a window to accelerate R&D and capacity investments before competition intensifies and supply constraints bite.
Engine Nacelle Market -
Risk of input-cost shocks. Raw-material volatility — notably disruptions to titanium supply — is no longer a theoretical tail risk. Procurement, sourcing strategy, and alloy-substitution workstreams must be prioritized to protect gross margins and delivery fidelity.
Engine Nacelle Market -
Certification & regulatory cycles. Compliance with airworthiness standards (e.g., FAA 14 CFR Part 33) imposes multi-year timelines for design changes and retrofits; understanding certification sequencing is critical when scheduling product launches and after-market offers.
-
Consolidation & competitive positioning. The market exhibits a moderate concentration among established nacelle system specialists and aero-structure Tier‑1s. Strategic M&A and targeted partnerships remain high-impact levers to secure program content and aftermarket streams.
Market sizing and near-term trajectory
Our base-year assessment (2025) places the global Engine Nacelle market at roughly USD 600 Million. Looking into 2026, we expect continued growth driven by fleet renewals, narrowbody program ramp-ups, and aftermarket demand as operators invest in fuel-efficiency and noise-reduction upgrades. By applying a 5% CAGR across our forecast period, the market reaches a substantively larger scale by 2032 under the central projection. Importantly, the historical series shows resilience: the sector recovered from a mid-period downturn and is now on an upward path, but that recovery is uneven across program types and supplier footprints — a nuance that matters for program-level bidding and capacity planning.
Key demand and technology drivers
-
Fuel efficiency and emissions. Airframe and powerplant OEMs continue to prioritize nacelle integrations that reduce engine fuel consumption and lifecycle CO2. Opportunities exist for advanced nacelle geometries, acoustic liners, and smooth integration with low-bypass and next-gen turbofan designs.
-
Noise regulation and community constraints. Stricter airport noise standards and community-driven curfews increase the value of nacelle-level noise-reduction technologies and may accelerate retrofit demand in specific markets.
-
Composite adoption and weight reduction. Lightweight composite nacelle components deliver lifecycle benefits but require robust manufacturing ecosystems and quality systems — firms that have demonstrable capabilities in advanced composites command pricing and program preference.
-
MRO and aftermarket monetization. Growth in installed base and retrofit cycles elevates the attractiveness of service contracts, spares provisioning, and on-wing support as higher-margin revenue streams.
Supply chain, raw materials, and resilience measures
Raw-material dynamics are a strategic constraint. Industry data indicate that geopolitical developments have disrupted key titanium supply lanes, creating potential shortages and elevated costs across the next 18–36 months. For procurement and operations leaders this translates into three actionable priorities: diversify qualified suppliers, accelerate alternative-material qualification programs where technically and regulatorily feasible, and implement tiered sourcing contracts that lock pricing or volumes through critical certification windows.
Competitive landscape — who matters and why
The Engine Nacelle ecosystem is anchored by a mix of integrated Tier‑1 nacelle systems specialists and a set of aero-structure and components-focused players. Our study includes detailed profiles and strategic assessments for the industry’s leading contributors. Highlights:
-
Safran Nacelles (France): Globally recognized for end-to-end nacelle programs and strategic engine partnerships. Strong program integration capabilities make them a natural contender on new OEM platforms.
-
Collins Aerospace (RTX Corporation, United States): A long-tenured systems supplier with a focus on certifiable solutions, lean manufacturing, and acoustic technologies. Their R&D in noise mitigation and program certification depth is a differentiator.
-
Spirit AeroSystems and Nexcelle (United States): Both bring program-specific strength: Spirit with volume programs for major narrowbody platforms, and Nexcelle with focused nacelle architectures and supplier collaborations across major OEMs.
-
European and specialized providers (GKN Aerospace, FACC, Aernnova, Liebherr-Aerospace, among others): These players compete on composite expertise, thrust reverser technology, and actuation systems — portfolio breadth versus specialization is the strategic trade-off.
-
Component- and systems-focused firms (The NORDAM Group, Triumph, Barnes Group Inc, Magellan Aerospace, Woodward, Ducommun): These suppliers occupy critical niches (actuation, fan cowls, thrust reversers) and are increasingly strategic partners for Tier‑1 integrators seeking supply-chain redundancy.
Across these participants, our competitive analysis identifies strategic vectors: (1) consolidation for program access, (2) vertical integration of high-risk subsystems, and (3) product differentiation via low-noise/weight architectures. Top players combine systems-integration credibility with certification track-records and global aftermarket networks.
Recent industry signals
Innovation remains active: for example, ST Engineering MRAS showcased advanced nacelle components at the Singapore Airshow in February 2026, signaling sustained technology investment and the competitive importance of airshow-leveraged demonstrations for program marketing. At the same time, regulators continue to set the pace; adherence to airworthiness standards such as FAA 14 CFR Part 33 is central to any product roadmap.
What our full report provides (practical, transaction-ready deliverables)
We designed this research as an operational tool for 2026 decision cycles. Components include:
-
Bottom-up market model: granular revenue build-ups by program vintage and an integrated forecasting engine that supports scenario toggles (demand shocks, price erosion, material-cost stress tests).
-
Program-level risk heatmaps: certification timelines, supplier single-source exposure, and aftermarket revenue visibility.
-
Supplier capability matrix: technical competencies (composites, actuation, acoustic liners), certification depth, global manufacturing footprint, and willingness to partner or divest.
-
Cost and margin diagnostic: bill-of-materials benchmarking, cost-to-manufacture ranges, and sensitivity to titanium and composite resin prices.
-
Commercial playbooks: bidding strategies for OEMs and suppliers, win themes for MRO service contracts, and integration checklists for joint ventures and acquisitions.
-
Scenario analyses and trigger points: early-warning indicators for supply-chain stress, demand shocks, and profitable entry/exit thresholds for investors and strategic buyers.
Each section is built to be operational: procurement teams get supplier negotiation levers; corporate development teams receive acquisition target scorecards; product leaders obtain certification-aware roadmaps.
Strategic recommendations for 2026
-
Prioritize supply-base diversification immediately. Lock in multi-year agreements with qualified alternative titanium and composite suppliers, and fund accelerated qualification programs to reduce single-source exposure.
-
Invest selectively in acoustic and aerodynamic innovations that deliver measurable fuel-burn and noise benefits. These deliver regulatory and commercial differentiation and can command aftermarket pricing premiums.
-
Define an MRO-led aftermarket strategy. Expand on-wing support offerings and spare-part inventories in markets where retrofit economics are compelling; margin-led services will smooth cyclicality and improve valuation multiples.
-
Push certification roadmaps earlier in the product development cycle. The lead time on airworthiness approvals is non-trivial; firms that front-end certification investments shorten time-to-revenue and reduce program risk.
-
Pursue bolt-on acquisitions for capability gaps rather than broad horizontal deals. Target firms that provide actuation, thrust-reverser expertise, or unique composite process know-how to accelerate program wins.
-
Build scenario playbooks for 2026–2028. Codify trigger points (material-cost thresholds, OEM order book shifts, regulatory changes) that will activate pre-defined responses: hedge contracts, ramp-up/down manufacturing, or strategic buyer approaches.
Final note — the strategic value of the full study
This preview is intended to establish the strategic calculus and the near-term imperatives for 2026. Our full Engine Nacelle Market research delivers the underlying datasets, program-level economics, and supplier scorecards necessary to execute the recommendations above. We intentionally limit disclosure here to preserve the actionable granularity found in the complete report — including program-by-program forecasts, supplier contracts analysis, and market segmentation — which remains accessible through the full study platform.
Next steps
For teams preparing capital plans, procurement strategies, or M&A pipelines in 2026, the optimal next step is a short briefing with our market modeling team to align scenario assumptions with your balance-sheet and program timelines. PW Consulting can run a tailored sensitivity analysis across your product and supplier portfolio to produce a 90‑day action plan that converts market visibility into defensible, immediate moves.
For detailed analysis of this topic, please visit the official page: Engine Nacelle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com