

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: I&I Cleaning Market Poised for 4.72% CAGR to 2032

Industrial and Institutional Cleaning Market: Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
As PW Consulting’s flagship intelligence on Industrial & Institutional (I&I) Cleaning, this briefing synthesizes the macro trajectory, competitive dynamics, regulatory turning points, and practical playbooks that will shape capital allocation and commercial strategy in 2026. The market we model uses 2025 as the base year and projects through 2032: following steady growth from 2020, the industry is expected to expand at a compound annual growth rate (CAGR) of 4.72% through our forecast horizon. Total industry revenues grew from the low‑50s (USD Million) in 2020 to an estimated USD 63.4 Million in 2025 and are projected to approach the high‑80s (USD Million) by 2032. Those headline figures frame a market that is mature but adaptive — where raw material shocks, regulatory resets, and service‑led differentiation will reallocate value.
Industrial and Institutional Cleaning Market
Why this matters for 2026 planning
-
Timing: 2026 is not just another forecasting year. It is the inflection moment when post‑pandemic hygiene demand normalizes while structural pressures — notably raw material cost volatility and tightened chemical regulation — accelerate margin compression and compel reformulation or premiuming strategies.
Industrial and Institutional Cleaning Market -
Decision leverage: Procurement, R&D prioritization, and portfolio reshaping decisions taken in 2026 will determine supplier relationships and margin profiles for the next business cycle. Firms that preemptively redesign formulations, renegotiate supply terms, or shift toward service/recurring revenue models will capture asymmetric returns as the market rebalances.
Industrial and Institutional Cleaning Market -
Risk window: New regulatory measures and intensified scrutiny of persistent bioaccumulative toxins will drive short‑term compliance costs and medium‑term ingredient substitution. These risks are quantifiable and manageable — but only with scenario‑based planning and prioritized mitigation actions.
Market dynamics shaping 2026
-
Raw material and energy volatility: 2026 has seen pronounced price shocks across key input streams. Leading suppliers have implemented significant price increases in response to supply chain and energy disruptions. These moves compress formulators’ gross margins unless offset by pricing discipline, reformulation, or operational efficiencies.
-
Regulatory tightening: Authorities in major markets are progressing risk evaluations and enacting amendments that target several widely used industrial chemicals. The evolving regulatory environment elevates compliance costs and introduces phase‑out timelines for certain legacy solvents and specialty agents. Firms must prioritize chemical inventory audits, alternative‑ingredient testing, and regulatory scenario modeling.
-
Service and systems shift: End‑users increasingly value integrated solutions — automated dispensing, data‑enabled hygiene verification, and sustainability assurances. This is translating into demand for bundled hardware‑software‑chemical offerings and service contracts that improve retention and margin resilience.
-
Consolidation and concentration: The market shows a material degree of concentration among major global suppliers. Competitive advantage is shaped by scale in raw material procurement, formulation IP, and channel reach into institutional customers. For many buyers and smaller suppliers, this concentration raises supplier dependency and negotiating complexity.
-
Customer segmentation evolution: Buyers — from healthcare and foodservice to manufacturing and commercial property managers — are differentiating requirements around efficacy, traceability, and sustainability. This creates premiuming opportunities for validated high‑efficacy or low‑environmental‑impact formulations, while commoditization risks persist in basic surface care categories.
Competitive landscape — who moves markets
The competitive arena blends ingredient majors, specialty formulators, and hygiene system providers. The list of global players we profile includes multinational chemical suppliers and operational hygiene leaders. Each offers distinct strategic assets:
-
BASF SE (Ludwigshafen, Germany) — a full‑spectrum supplier of surfactants, enzymes and specialty additives, active across both raw material supply and formulation support. Recent unilateral price adjustments underscore the company’s leverage over upstream cost pass‑through dynamics.
-
Ecolab Inc. (St. Paul, Minnesota, USA) — a service‑led hygiene company combining chemical portfolios with dispensing systems and digital monitoring. Its strength is in cross‑industry penetration and contractually recurring revenues.
-
Diversey Holdings Ltd. (Charlotte, North Carolina, USA) — focused on sustainable, tech‑enabled cleaning solutions for healthcare, hospitality and food service, emphasizing lifecycle cost and compliance advantages.
-
The Clorox Company (Oakland, California, USA) — through its professional line, leverages brand recognition and scale in disinfectants and institutional wipes to serve managed facilities and healthcare segments.
-
Dow Inc., Clariant AG, Huntsman, Stepan, Solvay and others — these firms supply critical surfactants, solvents, polymers and additives that feed the formulation layer. Their strategic positioning centers on raw material innovation, stable supply, and sustainability roadmaps.
-
Kimberly‑Clark Corporation — differentiated by nonwoven and wipe products for institutional hygiene, combining material science with distribution strengths.
Together, this cohort controls a substantial proportion of professional‑grade supply and sets the market’s price and innovation agenda. Recent public moves — notably large price increases by a major provider to offset material and energy cost volatility — illustrate the speed at which upstream shocks can feed through to end markets.
Report contents — actionable intelligence (what’s inside)
Our full market study is built as a practitioner’s toolkit. Highlights include:
-
Top‑down and bottom‑up market sizing with transparent assumptions (base year 2025), and an integrated model projecting to 2032 using a 4.72% CAGR scenario plus high/low cases for sensitivity testing.
-
Supply chain stress testing: supplier concentration analysis, critical‑raw‑material mapping, and a supplier risk heatmap that identifies single‑source exposures and substitution pathways.
-
Regulatory impact matrix: scenario narratives and quantified P&L impacts for likely regulatory outcomes, including compliance timelines and cost pathways for ingredient substitution.
-
Price and margin playbooks: tactical options for cost recovery (contract terms, indexation, tiered pricing), product mix optimization, and route‑to‑market adjustments for 2026 shocks.
-
Technology and service monetization frameworks: go‑to‑market blueprints for transitioning from product sales to recurring revenue via dispensing systems, SaaS sanitation verification, and managed services.
-
M&A & partnership lens: target profiles, valuation heuristics for strategic and financial buyers, and integration checklists for technology or raw material acquisitions.
-
Customizable dashboards and Excel models for board presentations and investment committees that help quantify tradeoffs across price, volume, and margin scenarios.
Strategic imperatives for 2026
-
Lock in upstream protection: Negotiate multi‑year supply contracts with index mechanisms, qualify secondary suppliers, and accelerate testing of alternative chemistries to reduce exposure to single‑source price spikes.
-
Prioritize regulatory preparedness: Build a short list of likely ingredient phase‑outs, fund accelerated substitution R&D for the most at‑risk formulations, and establish regulatory monitoring to shorten reaction time.
-
Shift to service‑led models where feasible: Pilot automated dispensing and hygiene verification offerings with high‑value customers to transition a portion of revenue to recurring streams that are more resilient to raw material swings.
-
Recalibrate pricing architecture: Move from across‑the‑board hikes to differentiated pricing tied to formulation cost, efficacy claims, and service bundling to preserve volume in price‑sensitive accounts.
-
Invest in data and traceability: Deploy batch‑level traceability and performance analytics to support premium claims (sustainability, efficacy) and to defend pricing to institutional buyers.
-
Prepare M&A and partnership options: Identify bolt‑on targets that accelerate access to sustainable chemistries, digital dispensing, or regional distribution networks to shore up market position as competitors pursue consolidation.
How to use this briefing — practical next steps
-
Operational leaders: run a 90‑day supplier audit and a 180‑day reformulation pipeline for exposed SKUs; prioritize negotiations with top suppliers and model cash flow impact of various indexation formulas.
-
Commercial teams: segment customers by price elasticity and service appetite; pilot premium service bundles with a subset of accounts to test willingness to pay and churn impact.
-
R&D and sustainability leads: fast‑track testing of non‑restricted chemistries and allocate validation resources to high‑volume institutional applications that face imminent regulatory risk.
-
Finance and corporate development: use the report’s valuation heuristics and scenario outputs to assess opportunistic M&A or partnership plays that can be executed before competitors reposition.
Final note — why you should read the full report
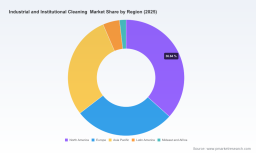
This briefing outlines the strategic topography of the I&I cleaning market as you enter 2026, but intentionally omits granular regional and application‑level distributions that drive transactional decisions. The complete PW Consulting report delivers those subsegment matrices, supplier‑by‑sku exposure tables, and downloadable scenario models designed for direct use in procurement negotiation rooms and board decks. If your 2026 planning requires executable detail — not just directional intelligence — the full study contains the calibrated numbers and playbooks to act decisively.
For executives preparing budgets, negotiating with suppliers, or evaluating product and service pivots, the right combination of macro outlook, supplier intelligence, and operational playbooks is the difference between cost pass‑through and market share capture. PW Consulting’s full Industrial & Institutional Cleaning Market study provides that combination — ready to be deployed in Q1 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Industrial and Institutional Cleaning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com