

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: CPVC Power Pipe Market to Reach USD 2.59 Billion by 2032 at 6.67% CAGR—Asia‑Pacific Leads with USD 908.1M in 2025
By pmarketresearch, 2026-07-13
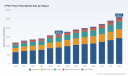
CPVC Power Pipe Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive preview from PW Consulting’s 2026 market intelligence suite
As power networks, telecom backbones and industrial plants accelerate upgrades, the market for CPVC power pipe is entering a phase of sustained expansion and strategic complexity. Our new PW Consulting report — covering historical performance (2020–2025) and forward forecasts through 2032 — synthesizes demand drivers, supply-chain pressures and competitive positioning into a decision-ready narrative for corporate leaders planning 2026 investments.
Cpvc Power Pipe Market
Market trajectory at a glance
After a five-year expansion through 2025, the CPVC power pipe market reached an estimated USD 1,648.6 million (base year 2025). Our model projects a continuation of growth into the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 6.67%, lifting total market value toward approximately USD 2,590.7 million by 2032. The transition from retrofit-centric demand in earlier years to a blended mix of urban grid modernization, telecom cable protection upgrades and industrial infrastructure investment underpins this trajectory.
Cpvc Power Pipe Market
These headline figures are the starting point. What matters for 2026 decisions are the underlying vectors — where demand concentrates, how input-cost volatility will affect margins, and which capability investments will yield the best risk-adjusted returns. The report translates headline growth into actionable scenarios for manufacturers, EPC contractors, utilities, and strategic investors.
Cpvc Power Pipe Market
Why 2026 is a strategic inflection
- Capital cycles align with policy windows: Many utilities and governments entering multi-year modernization programs will finalize procurement roadmaps in 2026 — creating near-term volume opportunities and contractual lock-ins.
- Raw material and trade dynamics are fluid: Feedstock price movements and policy actions in 2025 have already reshaped supply economics, and 2026 will be the first year when these impacts fully propagate through procurement and customer pricing.
- Competitive posture matters more than ever: Market concentration remains moderate (CR3 ≈ 21.45%, CR5 ≈ 32.18%), meaning scale, integrated-resin relationships and certification breadth will decide which suppliers capture high-value contracts.
Supply-side dynamics and cost levers
Three forces will dominate supplier economics in 2026:
- Feedstock pricing and availability: CPVC production is closely tied to PVC resin and chlorine feedstock cycles. Notably, spot PVC-related prices were softer in Q2 2025 (with a quarter-over-quarter decline of approximately 5.96% in North America), while US CPVC pricing reached near USD 2,370/MT in June 2025. These moves create both margin pressure and purchasing windows for buyers with flexible sourcing strategies.
- Regulatory intermittency: Environmental audits and tighter emissions controls in 2025 constrained output in several production hubs, particularly in China and parts of Europe, generating transitory supply tightness for import-dependent regions. Compliance-driven capacity curtailments are likely to recur as regulators enforce upgraded standards.
- Trade and tariff volatility: Sharp tariff actions in the 2025 period increased pricing premiums for regions reliant on imports. For 2026 procurement planning, tariff risk needs to be treated as a first-order variable in supplier selection and localization decisions.
For operators and procurement teams, these dynamics translate into concrete trade-offs between spot buys, long-term contracts and near-sourcing investments. The report provides modeled cost curves and procurement scenarios to stress-test these choices under alternative feedstock and tariff pathways.
Segmentation and demand patterns (high level)
Demand for CPVC power pipe is anchored by three application clusters: urban power grid upgrades, telecommunications and cable protection, and industrial/power-plant infrastructure. Each cluster exhibits distinct project rhythms, qualification needs and price sensitivity. Our analysis maps the implications of these differences for product specification, lead times and warranty design — without disclosing proprietary segment allocations in this summary.
Key takeaways for 2026 strategy:
- Urban grid programs favor suppliers with project and logistics scale, tight quality control and long-track records on system integration.
- Telecom and cable-protection projects prioritize conduit integrity, low-install-cost solutions and agile delivery, often favoring specialized channel partners.
- Industrial and power-plant clients demand high-temperature performance, traceability and stringent compliance pedigree, creating premium pockets within the market.
Competitive landscape — capabilities that matter
The CPVC power pipe arena blends global resin leaders, established North American and European manufacturers, and highly capable regional producers across Asia. In our review, key competitors demonstrate discrete strengths:
- Resin and compound leadership: Firms with integrated resin capability maintain a dual advantage: control over raw-material availability and influence over compound specifications. This vertical edge shortens lead times and supports higher-margin engineered lines.
- System suppliers and certification breadth: Manufacturers offering end-to-end systems (pipes, fittings, valves) with robust third-party certifications (e.g., NSF/ANSI) are preferred in regulated projects and public tenders.
- Regional manufacturing & distribution footprints: Local production capacity in high-growth markets reduces tariff exposure and improves responsiveness to utility-defined schedules.
Representative company archetypes we analyze in the full report include long-established North American producers with domestic manufacturing and compliance pedigrees; European thermoplastic specialists providing full-system solutions; and large regional manufacturers across South Asia and China focused on cost competitiveness and local project penetration. Each archetype faces different strategic imperatives in 2026, from downstream integration to export-risk mitigation.
What the PW Consulting report delivers (operational takeaways)
The full report is built for executives who must convert market projections into executable plans in 2026. It contains:
- Scenario-driven revenue models for 2026–2032 reflecting alternative macro, price and regulatory assumptions.
- Supplier risk heatmaps and procurement playbooks that integrate price, lead-time and compliance vectors.
- CapEx prioritization templates for manufacturing scale-up, near-shoring and certification roadmaps.
- Commercial negotiation templates and TCO calculators calibrated for CPVC-specific inputs (resin linked costs, tariffs, logistics premium).
- M&A readiness and target-screening criteria for buyers pursuing inorganic growth in core and adjacent segments.
- Regulatory impact assessment, including country-level constraint scenarios and mitigation approaches for import-dependent markets.
These tools are grounded in our proprietary databases and scenario engines, which synthesize historical performance (2020–2025) with forward-looking demand drivers to produce stress-tested strategies — not just static forecasts.
Strategic actions recommended for 2026
Based on the analysis, PW Consulting recommends that stakeholders prioritize three strategic actions this year:
- Lock strategic feedstock agreements with flexible clauses: Given ongoing feedstock price volatility and tariff risk, suppliers and large buyers should negotiate contracts with indexed pricing collars and capacity guarantees to preserve margins while retaining optionality.
- Invest selectively in near-shoring and certification: Target investments that reduce tariff exposure and shorten lead times for high-value projects. Certifications and traceability investments unlock premium tenders and reduce compliance friction in regulated markets.
- Differentiate on solutions not just product: Move from component sales to system solutions (value-added fittings, life-cycle services, warranty programs) to capture higher-margin pockets and deepen customer stickiness.
How to use the intelligence in 90 days
- Week 1–2: Validate exposure — map your 2026 tender pipeline against supplier concentration and tariff-exposed regions.
- Week 3–6: Run the PW procurement scenario models with your actual cost inputs to identify optimal contracting strategies (spot vs. hedged volume).
- Week 7–12: Execute targeted supplier negotiations or short-term near-shoring pilots to insulate mission-critical projects from feedstock shocks.
Access and next steps
This brief is a strategic preview designed to surface core market dynamics and executive priorities. The full PW Consulting CPVC Power Pipe Market report contains the detailed segment models, supplier profiles, contract templates and downloadable financial models that operational teams will need to execute on the 2026 agenda. For procurement directors, plant managers and corporate strategists, the report converts macro trends into procurement-ready actions and investment choices.
To obtain the full report, detailed scenario tables and the proprietary decision tools described above, please visit our official report page. PW Consulting clients can contact their account lead for expedited delivery and a tailored briefing session.
PW Consulting — converting market insight into executable advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Cpvc Power Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solid Fuel Testing Market Tops USD 482.5 Million in 2025, New Report Shows
By pmarketresearch, 2026-07-13
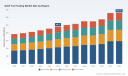
Solid Fuel Testing Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As energy markets and decarbonization pathways converge, the quality-assurance layer that sits between fuel producers, regulators, and end-users—solid fuel testing—has quietly grown into a strategic enabler. PW Consulting’s new Solid Fuel Testing Market report (base year 2025; historical 2020–2025; forecast 2026–2032) distils the commercial and regulatory forces shaping this space and translates them into decision-ready guidance for executives planning 2026 initiatives and beyond.
Solid Fuel Testing Market
Market Snapshot: A steady growth runway with important inflection points
After recovering from pandemic-era disruptions, the global solid fuel testing market reached approximately USD 482.5 Million in 2025. Our forecast models project a continuation of steady expansion through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 4.59%, taking the market to roughly USD 661 Million by 2032. This growth trajectory reflects a mix of ongoing demand for traditional coal and coke testing, expanding requirements for biomass and waste-derived fuel verification, and incremental service intensity tied to regulatory and contractual compliance.
Solid Fuel Testing Market
Market concentration is moderate: the three largest firms account for a little over one-third of the market, with the top five approaching half. This structure creates opportunities for scale players to leverage global labs and for specialized providers to defend niches through accreditation, speed-of-service, or localized sampling capabilities.
Solid Fuel Testing Market
Why this matters for 2026 decision-makers
- Strategic procurement: Fuel buyers and utilities must balance spot and contracted sourcing with evolving testing requirements. Testing providers that can demonstrate rapid, standards-aligned sampling and analysis materially reduce commercial settlement risk.
- CapEx prioritization: Investors and plant operators assessing retrofits or fuel-switching projects need defensible testing plans to model combustion performance, emissions outcomes, and ash management—inputs that materially affect ROI.
- Regulatory resilience: Shifts in emissions rules and renewable fuel mandates create step-changes in testing scope. Companies that anticipate these changes and pre-position laboratory and mobile capabilities will avoid costly scope gaps mid-contract.
Dynamics shaping the next 18–36 months
The market is being driven by four interacting vectors:
- Regulatory recalibration. Recent U.S. Environmental Protection Agency rulemaking through 2025–2026 has altered the compliance landscape for renewable fuels and mercury emissions in coal-fired units. Such revisions create near-term surges in demand for qualifying tests, retesting of legacy contracts, and verification tied to subsidy or compliance schemes.
- Fuel mix diversification. Energy transition strategies are prompting greater use of biomass, co-firing blends, and waste-derived fuels. Each fuel family brings distinct test portfolios and sampling complexities—raising the average testing touchpoint per ton of fuel delivered.
- Supply chain pragmatism. Global trade patterns, port congestion, and regional policy incentives are increasing the need for on-site testing, mobile laboratories, and rapid-turnaround certificates that minimize demurrage and allow commercial settlement confidence.
- Quality and traceability expectations. Buyers and finance providers increasingly require ISO/ASTM-aligned testing, accreditation, and traceable sampling chains as prerequisites for contracts and project financing.
Competitive landscape: capabilities, gaps, and strategic positioning
The market features a mix of global testing conglomerates, regional laboratories, and specialized niche providers. Our competitive assessment emphasizes not only breadth of services but also where capability differentials will determine market share over the next two to three years.
- Intertek Group plc (London) – Strengths: comprehensive service suite across coal, metallurgical coke, petroleum coke, and biomass with deep standards expertise (ASTM, ISO). Strategic implication: Intertek’s global testing footprint and standards advisory capabilities make it a go-to for multinational trading firms and large utilities seeking integrated audit-and-test packages.
- SGS S.A. (Geneva) – Strengths: extensive laboratory network and recent capability expansion into solid waste fuel testing. Strategic implication: SGS is well positioned to capture growth in waste-to-fuel value chains and in markets where regulators require independent verification at scale.
- Bureau Veritas (Paris) – Strengths: independent inspection and specialist testing (e.g., coke reactivity, petrography), with investments in sustainable testing capabilities. Strategic implication: Bureau Veritas is attractive to metallurgical and niche industrial users who require both physical inspection and high-complexity laboratory services.
- ALS Limited (Brisbane) – Strengths: reliable coal sampling and broad analytical suite; regional depth in Australasia. Strategic implication: AL S’s operational reliability resonates with commodity traders and exporters in geographies where consistent throughput matters.
- AmSpec Services / Control Union / McCreath Labs / Standard Laboratories – Strengths: specialized biomass testing, accredited regional labs, mobile sampling and port services. Strategic implication: These players form the backbone of niche and local market service capacity—critical when speed and accreditation are non-negotiable.
Recent capability moves exemplify the directional bets firms are making: Bureau Veritas’ advances in Ghent toward sustainable solid fuel analysis; Control Union’s ISO 17025-accredited biomass laboratory opening in Vietnam; and SGS’s expansion into solid waste fuel testing in Riga. Collectively, these moves indicate an industry pivot toward broader fuel acceptance, faster logistics-aligned testing, and credentials that underpin trade and financing.
What’s in the PW Consulting report (practical, operational, and strategic modules)
Our report is designed to be transactionally useful to commercial teams, procurement leads, laboratory managers, and investors preparing 2026 plans. The deliverables include:
- Market sizing and forecast methodology, with sensitivity analyses that stress-test outcomes under multiple regulatory and fuel-mix scenarios.
- Detailed vendor capability profiles and a proprietary scoring matrix assessing accreditation breadth, mobile sampling capacity, lab throughput, geographic coverage, and turnaround times.
- Operational playbooks: templated sampling chains of custody, typical test bundles for coal/biomass/waste-derived fuels, and recommended SLA language for commercial contracts to reduce settlement disputes.
- Compliance toolkit: checklist alignment to ASTM, ISO, and relevant regional regulatory touchpoints, plus a scenario planner for impending rule changes.
- Go-to-market and M&A intelligence: gap analysis identifying where scale acquisitions or asset-light partnerships will accelerate entry into high-growth niches.
- Buyer decision frameworks: total cost-to-serve calculators that fold in testing lag risk, demurrage exposure, and credit implications tied to disputed fuel quality.
To respect competitive sensitivity and our “trailer” approach, the report reserves the full segmentation tables, regional allocations, and granular unit values for subscribers. These tables pair with proprietary primary research to enable contract-level modeling and supplier selection decisions.
Strategic recommendations for executives planning in 2026
- For fuel buyers and utilities: Lock in multi-tier testing arrangements that combine accredited lab contracts with local mobile sampling. Prioritize providers with demonstrable rapid-turnaround certificates and electronic custody chains.
- For testing service providers: Invest in ISO/ASTM accreditations and mobile-lab assets aligned with major trading hubs. Consider targeted partnerships to cover waste-derived fuel protocols and emerging biomass specifications.
- For investors and acquirers: Target bolt-on acquisitions that deliver immediate local accreditation or logistical gain (e.g., port-based mobile crushing and sampling), rather than broad capabilities that require long integration timelines.
- For regulators and policy teams: Engage with the testing ecosystem when drafting fuel definitions and compliance timelines; clearer test-method harmonization reduces market frictions and non-compliance disputes.
Risk matrix: what could derail the outlook
- Policy volatility: Abrupt regulatory reversals or delayed implementation of renewable fuel volumes could compress near-term testing demand.
- Technology disruption: Rapid uptake of in-line, sensor-based calorific or moisture measurement could reduce lab-based test volumes unless labs evolve to provide verification and calibration services.
- Market fragmentation: Proliferation of non-accredited “certificate” providers could increase disputes—raising the value of accredited, traceable testing but pressuring margins.
How PW Consulting’s analysis converts to 2026 action plans
Clients who have previewed our executive briefing consistently highlight three tangible benefits:
- Faster supplier selection cycles through our vendor scorecards and contract templates—reducing procurement time by weeks where testing requirements are complex.
- Reduced settlement disputes via our tested chains-of-custody playbook and recommended SLAs—improving working capital predictability.
- Clarity on where to invest for capability—be it mobile lab assets, ISO accreditations, or data-integrated certificates—to capture incremental margin or de-risk fuel portfolios ahead of regulatory shifts.
Conclusion: positioning for practical resilience
The solid fuel testing market is not a headline-grabbing segment of the energy transition, but it is a foundational one: accurate, timely testing underpins commercial settlement, regulatory compliance, and the credibility of fuel-switching initiatives. With market value having expanded to just under USD 500 Million in 2026-equivalent terms and a multi-year CAGR that supports steady growth to roughly USD 661 Million by 2032, the observable pattern is clear—testing demand will track both fuel-market complexity and regulatory scrutiny.
PW Consulting’s Solid Fuel Testing Market report translates this macrotrend into concrete operational playbooks, vendor intelligence, and financial implications tailored for 2026 decision cycles. For executives who need the granular segmentation, regional allocations, and supplier-level financials to execute supplier choices or M&A plays, the full report contains the detailed datasets and scenario models that make those decisions defensible.
Next step
To access the complete dataset, vendor scorecards, and the operational toolkits referenced in this briefing, visit PW Consulting’s Solid Fuel Testing Market report page for subscribers and commissioned clients. Our team is available to run bespoke workshops that convert the report’s insights into executable 90–180 day plans aligned to your sourcing, compliance, or investment timelines.
For detailed analysis of this topic, please visit the official page: Solid Fuel Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Center Network Market to Rise from USD 38.41 Billion in Base Year 2025 to USD 108.56 Billion by 2032, Fueled by a 15.9% CAGR
By pmarketresearch, 2026-07-13
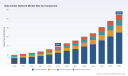
Data Center Network Market 2026: Strategic Imperatives for Decision-Makers
PW Consulting’s latest Data Center Network Market report (base year 2025, forecast 2026–2032) is designed for boards, CIOs, infrastructure investors, and procurement leaders needing a concise, practicable intelligence package to make high‑stakes decisions in 2026. The market has shifted from a multi-year hardware refresh cycle into an era defined by AI‑scale interconnects, power constraints, and platform‑level differentiation. Our research synthesizes historical performance with forward scenarios to translate complexity into clear action. Below we present a high‑level preview of the report’s strategic value—deliberately omitting detailed segment tables and vendor shares so that decision‑makers access the full, sourced datasets via our report page.
Data Center Network Market
Executive snapshot
- Market trajectory: The Data Center Network market expanded materially during 2020–2025, rising from USD 20.15 Billion in 2020 to USD 38.41 Billion in 2025. The acceleration is continuing into 2026 with an expected step change as AI workloads penetrate broader deployments.
- Near‑term forecast: Our base forecast projects the market to grow at a compound annual growth rate (CAGR) of 15.9% through the 2026–2032 horizon, reaching USD 108.56 Billion by 2032 under the central scenario.
- Structure and concentration: The market exhibits meaningful concentration—our analysis shows that the top three vendors command a substantial share of revenue, and the top five capture an even larger portion—indicating an environment where strategic vendor selection and risk mitigation are critical.
- Why this matters now: Capital intensity from hyperscalers, regulatory change around power, and new silicon and optics launches are changing both procurement calculus and architecture decisions for 2026.
Why this report matters for 2026 decisions
- AI as the growth vector: Hyperscaler and AI customer investment behavior is the prime near‑term demand driver. Industry CapEx into data center infrastructure surged in the lead‑up to 2025, and large public cloud and AI platform investments materially altered upgrade cadences and density requirements. This report quantifies those dynamics and translates them into procurement and capacity plans.
- Power and interconnection risk: New regulatory arrangements and commercial pledges have reframed who bears incremental grid and generation costs. Simultaneously, operators face multi‑year grid connection queues that force consideration of behind‑the‑meter generation, battery storage, and staged capacity approaches. Our models allow you to stress‑test financials under these constraints.
- Vendor consolidation and differentiated silicon: Rapid introductions of new switch‑chip and DPU families are shifting value from box vendors to silicon and software ecosystems. The convergence of ASIC capability, DPU offload, and optical fabric design requires an integrated vendor and architecture assessment—our vendor scoring matrix and scenario planner operationalize that evaluation.
What the report contains: operational, repeatable outputs
- Market sizing & scenario suite: Annual historical series (2020–2025) and multiple forecast scenarios (2026–2032) with sensitivity to AI workload penetration, capex cycles, and regulatory shocks.
- Investment & procurement playbooks: Practical templates for RFIs/RFPs, TCO calculators, lifecycle cost models (power, cooling, optics), and contract clauses that allocate interconnection and grid upgrade risk.
- Vendor scorecards and decision tree: Independent comparative assessments of hardware, silicon, DPU, and software capabilities; recommended win‑/loss criteria for enterprise, colocation, and hyperscale procurement tracks. (Detailed vendor share tables and segment‑level numbers are available in the full report.)
- Deployment case studies: Real‑world examples of scaled AI fabric deployments, power‑constrained colo expansions, and retrofit programs that reduced TCO and deployment lead times.
- Regulatory impact toolkit: A playbook that converts state and federal policy developments into actionable procurement and siting strategies, including models for behind‑the‑meter investments and battery co‑location economics.
- M&A and partnership diligence: Checklists and valuation adjustments tailored to network‑centric deals and strategic alliances with silicon/optics suppliers.
Competitive landscape: who matters and why
The data center networking ecosystem is evolving into a multi‑layered competitive battleground where silicon, software, and systems integration determine customer outcomes. Leading players exhibit differentiated strengths:
Data Center Network Market
- Cisco Systems, Inc. — Continues to dominate with integrated stacks that combine switch silicon, routing, and fabric software optimized for hyperscale and enterprise requirements. Recent advancements in high‑performance switch chips and routing platforms signal Cisco’s intent to defend scale deployments and AI fabric footprints.
- Arista Networks, Inc. — Focused on high‑speed Ethernet and AI‑optimized fabrics, Arista’s platform strategies emphasize low latency, power efficiency, and operational simplicity for cloud and AI clusters. Its product cadence targets reduced TCO for service providers and hyperscalers.
- Juniper (now integrated with Hewlett Packard Enterprise) — The HPE–Juniper combination positions a stronger integrated edge‑to‑core portfolio, blending Juniper’s routing and switching innovations with HPE’s systems and channel reach—an important strategic consolidation to watch for enterprise adoption cycles.
- NVIDIA Corporation — By bringing high‑performance switching and DPU capabilities together with its GPU leadership, NVIDIA is shaping a new class of AI fabrics where packet processing, telemetry, and application offload are tightly coupled with GPU compute.
- Broadcom Inc. — As a core silicon supplier, Broadcom’s ASIC roadmaps influence the entire vendor ecosystem; network vendors’ competitiveness increasingly depends on how they leverage Broadcom silicon variants and value‑add software.
- Dell Technologies, Huawei, Extreme Networks, Nokia and others — Each brings complementary strengths: integrated IT stacks, regional market penetration, fabric innovation, and optical interconnect capabilities. Competitive differentiation will hinge on software monetization, service delivery, and geographic/regulatory positioning.
Recent product and corporate developments—such as major new silicon launches and the large strategic acquisition activity in 2025–2026—are compressing windows for procurement decisions. Our vendor matrices show how these moves change supplier risk profiles and strategic fit for particular customer segments.
Data Center Network Market
Regulatory and infrastructure dynamics shaping 2026 strategies
- Power and community impact frameworks: Several major cloud and AI companies have publicly committed to covering incremental grid upgrade costs to protect residential ratepayers. This changes the commercial negotiation dynamics for large data center projects and introduces new forms of long‑term contractual exposure and reputational risk.
- Grid connection lead times: Prolonged interconnection queues in primary markets are forcing operators to consider behind‑the‑meter generation, battery storage, and phased buildouts. Our financial models quantify break‑even points for on‑site generation versus extended wait times.
- State‑level cost allocation: Emerging state policies that require large load customers to bear interconnection costs mean that location decisions must be evaluated not only on land and tax incentives, but on foreseeable utility upgrade liabilities.
- Standards and resiliency expectations: With Uptime Institute Tier standards remaining the benchmark for mission‑critical performance, networking architecture choices must align with maintainability and redundancy expectations—especially for Tier III/IV environments.
Top strategic recommendations for 2026
- Adopt a portfolio approach to supplier risk: Combine a primary strategic partner with two specialty providers—one focused on silicon/optics and another on software/DPU capabilities—to avoid lock‑in and exploit rapid innovation cycles.
- Model power and interconnection as first‑order costs: Include multi‑year grid delay scenarios and behind‑the‑meter options in CapEx/OpEx models; treat battery storage as a deployment accelerant, not only a resiliency add‑on.
- Prioritize software and telemetry capabilities: Operationalization and intent‑based networking deliver disproportionate downstream savings for dense AI deployments—ask vendors for measurable OPEX reduction commitments backed by SLAs.
- Leverage staged capacity designs: Where connection permits are uncertain, adopt modular POD architectures that allow incremental density increases and selective silicon upgrades without wholesale rip‑and‑replace.
- Embed regulatory scenarios into site selection: Use our regulatory impact score to quantify state and local policy exposure and fold this into TCO and NPV models used in siting decisions.
How to use PW Consulting’s full report
This article is a strategic trailer that highlights the operational insights and decision tools contained in PW Consulting’s full Data Center Network Market report. The complete publication includes granular vendor share data, regional and end‑user segmentations, downloadable financial models, full vendor scorecards, and the datasets that underpin our scenarios. Those core segment numbers and vendor allocations are deliberately withheld here to ensure you consult the authoritative source for procurement‑grade figures and bespoke modeling templates.
For procurement teams, investors, and technical architects making binding decisions in 2026, the full report converts market dynamics into executable plans—RFx artifacts, supplier due‑diligence protocols, and energy‑aware TCO models that can be applied immediately. Access the full report and the interactive dataset on our website to download the detailed charts, tables, and scenario workbooks that support rapid, defensible decision‑making.
For detailed analysis of this topic, please visit the official page: Data Center Network Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Welded Stainless Steel Tubing Market Poised for 4.2% CAGR Through 2032
By pmarketresearch, 2026-07-13
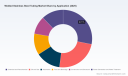
Welded Stainless Steel Tubing Market 2026: Strategic Imperatives from PW Consulting
The global welded stainless steel tubing market reached USD 18,242.3 Million in 2025 and is set to resume steady expansion over the forecast window. PW Consulting’s new market study projects a compound annual growth rate (CAGR) of 4.2% for 2026–2032, driving the market toward roughly USD 24.33 Billion by 2032. For executives planning capital allocation, supply-chain redesign, or M&A activity in 2026, this report translates macro momentum into disciplined, actionable choices while preserving the proprietary subsegment intelligence that underpins high‑confidence decisions.
Welded Stainless Steel Tubing Market
What the PW Consulting Report Actually Delivers (Practical, Usable Intelligence)
- Rigorous market sizing and trend validation: historical time-series (2020–2025), base‑year reconciliation (2025), and scenario-driven forecasts to 2032 with downside, base, and upside cases.
- Supply‑chain cost and margin maps: raw‑material exposure (nickel/chrome), mill yield curves, conversion cost drivers, and inflation pass‑through assumptions to model price sensitivity.
- Technology benchmarking and adoption curves: laser‑weld, laser‑hybrid, and conventional welding performance, unit cost comparisons, productivity deltas and investment break‑even analyses.
- Regulatory and standards impact assessment: implications of ASTM standards and their adoption timelines for product certification, liability, and contract compliance.
- Competitive positioning and deal pipeline: company scorecards, capability matrices, and a prioritized list of potential acquisition and partnership targets aligned to four corporate archetypes (scale players, high‑value alloy specialists, precision/laser specialists, and regional nimble suppliers).
- Playbooks for 2026 execution: procurement hedging strategies, capacity‑planning templates, product roadmap prioritization, and go‑to‑market tactics tailored for OEM, energy, and industrial end users.
- Interactive decision tools: downloadable models for scenario testing, unit economics, and cash‑flow sensitivity tuned to user inputs.
Note: This press summary intentionally highlights strategic insights and frameworks rather than publishing the full subsegment tables and granular company revenue splits. The complete datasets, dashboards, and segment-level forecasts are available through the report portal.
Welded Stainless Steel Tubing Market
Key Market Dynamics That Will Drive Decisions in 2026
- Steady, broad‑based growth. After a multi‑year recovery phase, the market’s mid‑single digit CAGR reflects structural demand across energy, process industries, transportation electrification, and commercial infrastructure. The growth profile favors players with flexible supply chains and product families that span commodity to high‑performance alloys.
- Raw‑material volatility as an operational risk. Nickel and chromium feedstock pricing swung materially in the run‑up to 2024, creating pronounced input cost risk for manufacturers and buyers. Buyers and producers must embed price‑flexibility clauses and consider financial hedging or forward procurement strategies to protect margins in 2026.
- Technology led differentiation. Laser and laser‑hybrid welding technologies materially improve fatigue resistance and dimensional control versus conventional welding, unlocking new use cases in thermal management, emission control, and structural profiles. Capital allocation to selective automation and welding upgrades is becoming a competitive prerequisite rather than optional.
- Standards and certification as market access gates. Recent and emerging ASTM specifications for mechanical and laser‑welded structural tubing raise the bar for material qualification and traceability. Compliance timelines will influence procurement windows and offer early-mover advantages to certified suppliers.
- Production concentration vs. fragmentation. The industry exhibits low top‑tier concentration—CR3 at c.14.8% and CR5 at c.22.2%—indicating fragmentation and substantial white space for roll‑up, capacity rationalization, and value‑chain consolidation strategies.
Competitive Landscape: Strategic Implications for 2026
The market map includes global steel majors, precision alloy specialists, and highly focused regional fabricators. Each archetype is playing a distinct game:
Welded Stainless Steel Tubing Market
- Precision and performance specialists (e.g., Plymouth Tube Company, Sandvik/Alleima) compete on tight tolerances, specialty grades, and aftermarket value for aerospace, medical, and heat‑exchanger OEMs. Their strategic advantage is IP, quality control, and premium yields.
- High‑alloy and energy-focused producers (e.g., Tubacex) serve demanding oil & gas and petrochemical specifications where metallurgical depth and alloy availability are paramount. These players weather commodity cycles by locking long‑term offtake and leveraging alloy inventories.
- Integrated industrial steel players (e.g., ArcelorMittal, Nippon Steel) bring scale, vertical integration, and broad distribution. Their strengths lie in cost competitiveness on commodity grades and in exploiting global project pipelines through existing client relationships.
- Regional and niche fabricators (e.g., Marcegaglia Steel, Bristol Metals/Brismet, Stainless Structurals, Indiana Tube, KVA Stainless) focus on service, custom profiles, quick turnarounds and compliance to local standards. Laser‑weld enabled firms and those certified to new ASTM profiles will increasingly capture architectural, structural and data‑center opportunities.
- Smaller precision makers (e.g., Fischer Group, YC Inox) and custom suppliers play important roles as specialist partners or tuck‑in targets for strategic acquirers.
Strategic takeaway: the combination of a fragmented supplier base and differentiated technology pathways creates both consolidation opportunities and niches where focused investment can yield outsized margins. Full company scorecards and capability heatmaps are included in the paid report.
Recent Events and What They Signal for 2026
- Standards compliance and trade show visibility from laser‑weld specialists highlights how certification plus targeted marketing accelerates adoption—an advantage for early‑certified players.
- Industry commentary noting dynamic growth in heat‑exchange replacement cycles confirms a durable demand pool for precision welded tubes.
- Raw‑material swings and regional manufacturing footprints underscore the strategic value of diversified sourcing and localized buffering strategies ahead of 2026 project cycles.
Actionable Strategic Recommendations for 2026
- Adopt a three‑track procurement posture: (1) short‑term hedging and indexed contracts for 2026, (2) mid‑term supplier diversification to de‑risk alloy exposure, and (3) strategic supplier partnerships with volume commitments to secure prioritized capacity.
- Prioritize selective capital investment in laser‑weld and automated inspection systems where the technology premium can be monetized (thermal management, EV battery systems, emission controls). Run a two‑year pilot to validate performance gains and commercialization cadence.
- Pursue targeted M&A and JV plays focused on: (a) laser‑weld technology providers and profile fabricators, and (b) regional service leaders that provide fast customer access and JIT logistics for critical end users.
- Institutionalize standards readiness: ensure product development pipelines incorporate ASTM requirements and that quality systems can produce traceable documentation for structural and pressure applications.
- Develop aftermarket and service revenue streams (assembly, coating, inventory management) to reduce exposure to commodity cycle swings and to deepen customer relationships.
- Embed scenario planning in capex decisions: use stress tests for feedstock price spikes, major new project rollouts, and accelerated EV demand shifts to size buffer capacity prudently.
Who Should Read This Report — And Why It Matters for 2026
- C‑suite leaders (CEOs, CFOs, COOs) evaluating strategic investment and portfolio reshaping.
- Procurement and supply chain heads seeking practical hedging frameworks and supplier scorecards.
- M&A teams and private equity assessing roll‑up opportunities in a fragmented market.
- Product and engineering leaders determining when and where to field laser‑welded and high‑alloy offerings.
- Project developers and EPCs who need certified supply sources for project delivery and warranty certainty.
PW Consulting’s study converts broad market signals into executable programs tailored to these stakeholders, with downloadable decision models that permit rapid scenario testing for 2026 actions.
Next Steps (How to Access the Full Intelligence)
This release provides a high‑confidence strategic view while preserving the granular subsegment forecasts, company revenue splits, and the interactive models that constitute the report’s commercial value. To access the full datasets, company scorecards, and the downloadable decision tools that will support 2026 planning, visit the PW Consulting report page. Our team also offers bespoke briefings and scenario workshops for executive teams preparing capital plans and M&A pipelines for 2026.
PW Consulting — translating market dynamics into clear, executable strategy for industrial leaders navigating the welded stainless steel tubing landscape.
For detailed analysis of this topic, please visit the official page: Welded Stainless Steel Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Brown Algae Protein Market Set to Expand at an 8.45% CAGR Through 2032
By pmarketresearch, 2026-07-13
Brown Algae Protein Market: Strategic Implications for 2026 — PW Consulting Insights
Executive summary
PW Consulting’s latest market study on Brown Algae Protein synthesizes commercial, technical and regulatory intelligence to inform executive decisions in 2026. The sector has moved from a niche ingredient space into a fast-growing component of multi-disciplinary value chains — driven by advancements in extraction technologies, rising interest in alternative proteins, and new biomass supply dynamics. Our analysis places the global brown algae protein market on a clear growth trajectory: after consistent expansion through 2020–2025, the market is forecast to continue expanding at a compound annual growth rate (CAGR) of 8.45% through 2026–2032. The trajectory and underlying drivers create discrete windows for strategic entry, scale-up, and consolidation in 2026; this report is structured to translate those windows into executable choices for corporate leaders.
Brown Algae Protein Market
Why 2026 is an inflection year
-
Maturing extraction and fractionation technologies have materially improved yield, purity and downstream functionality — making brown algae protein commercially viable for a wider range of food, feed and nutraceutical applications. This technical maturation is reducing barriers to premium product development and broader commercial adoption.
Brown Algae Protein Market -
Supply-side dynamics are shifting. Traditional harvest regions remain important, but the appearance of large-scale brown algal biomass events (for example, recent Sargassum accumulations measured in the order of tens of millions of tonnes) is creating potential low-cost feedstock streams. These episodic supplies present both an opportunity and a logistics challenge: they can dramatically lower raw material cost curves if processed responsibly, yet require rapid mobilization of processing capacity and environmental safeguards.
Brown Algae Protein Market -
Stakeholder expectations on sustainability, traceability and community engagement have hardened. Examples of co-management partnerships and sustainable harvest protocols in regions such as Brittany demonstrate that supply security in this segment increasingly depends on socio-environmental practices as much as on technical capability.
-
Market structure shows room for both incumbent expansion and nimble challengers. Our concentration analysis indicates a market that is not tightly consolidated at the top—enough scale exists among leading players to set technical standards, but fragmentation persists across geographies and product formats, leaving strategic openings for focused M&A and partnerships in 2026.
What the report contains — practical, decision-ready modules
-
Comprehensive market sizing and forecast model (historical 2020–2025 and forward-looking 2026–2032) with scenario variants to stress-test demand, price and feedstock volatility assumptions.
-
Supply-chain maps from harvest to finished protein fractions, highlighting bottlenecks in logistics, drying, storage and coastal processing capacity.
-
Technology assessment and vendor landscape covering extraction routes (mechanical, enzymatic, membrane, hydrolysis), yield curves, capex/Opex benchmarks and scale-up risks.
-
Regulatory and compliance playbook for prioritized markets, including submission checklists, expected timelines and label positioning strategies.
-
Commercial due diligence templates and contracting frameworks for offtake, toll-processing and co-investment with harvester communities.
-
Competitive intelligence dossiers on active producers and strategic challengers, including capability matrices, go‑to‑market approaches and partnership histories.
-
Investment and M&A screening tool with return simulations, payback windows, and integration risk scoring to support 2026 capital allocation decisions.
Strategic recommendations for 2026 decision-makers
-
Prioritize feedstock diversification and resilience. Combine contracted harvest volumes with scalable processing for episodic biomass sources (e.g., Sargassum events) to lower unit costs while maintaining quality controls.
-
Invest selectively in midstream processing capabilities that preserve protein functionality. Companies that control fractionation and stabilization will capture higher value per tonne than upstream-only harvesters.
-
Embed sustainability and traceability into commercial agreements. In 2026, procurement terms tied to verified harvesting practices and community benefits will materially affect market access in many buyer segments.
-
Adopt a portfolio approach to product strategy. Maintain a core range of high-yield isolates for commoditized applications while selectively developing differentiated formulations for premium food, nutraceutical and personal-care segments.
-
Use pilot partnerships to de‑risk scale-up. Short-term toll-processing agreements and co‑development projects with established processors can accelerate product validation without heavy upfront capex.
-
Pursue targeted M&A or joint ventures to gain proprietary processing know‑how and geographic sourcing. The mid-market remains receptive to bolt-on acquisitions that offer immediate capacity uplift or specialized technology.
-
Prepare regulatory dossiers and claims substantiation in parallel with product development. Align scientific programs to typical buyer evidentiary needs (safety, functionality, sustainability) to compress time-to-market.
Competitive landscape snapshot
The report maps ten core market participants that exemplify the range of strategic positioning in brown algae protein: European integrators that combine sustainable harvest practices with advanced fractionation; North American and South American players focused on raw material processing and feed markets; Asian large-scale producers offering cost leadership in alginate and protein derivatives; and specialist innovators developing food-grade powders and functional blends.
-
Algaia S.A. (France): a vertically integrated player with deep expertise in extraction and environmental co-management. Their operational model illustrates how certified harvesting partnerships can secure upstream supply while preserving access to premium buyers.
-
Acadian Seaplants (Canada): an established harvester-processor with strengths in animal nutrition and crop inputs. Their long-term contracts with coastal communities are a blueprint for supply resilience.
-
CP Kelco / Tate & Lyle (U.S.): incumbent hydrocolloid specialists who are extending value capture into associated protein fractions. Their scale and distribution networks are barriers for newcomers seeking rapid breadth in food markets.
-
Gelymar (Chile) and South American processors: regional champions offering proximity to prolific harvest zones, demonstrating the advantage of geographically focused processing clusters.
-
Large Chinese producers (e.g., Qingdao-based groups and Brightmoon): high-volume operations with cost competitiveness in commodity-grade ingredients, increasingly active in global supply chains.
-
Cargill (U.S.): a strategic acquirer and integrator that can leverage broader ingredient portfolios to accelerate commercial adoption in food and feed segments.
-
Specialists such as Ocean Harvest, Mara Seaweed and Seagreens: illustrate differentiated routes to market — from aquaculture feed formulations to consumer-facing food powders — and highlight niches where agility and product story drive premium pricing.
Collectively, these profiles show a market where scale, quality protocols and supply relationships matter more than sheer production capacity. Our concentration metrics indicate leading groups hold meaningful share but do not preclude disruption by well-executed entrants.
Operational and supply-chain signals to monitor in 2026
-
Regulatory shifts and eco-certification requirements at the national and buyer level that could change supplier eligibility overnight.
-
Capex announcements for coastal processing facilities and investments in drying and cold-chain logistics — early movers will secure capacity and margins.
-
Emergence of aggregator models that consolidate episodic biomass (harvested blooms) into uniform feedstock streams; these aggregators can compress supply volatility and become attractive acquisition targets.
-
Science-driven product claims and substantiation (e.g., amino-acid profiles, digestibility, functional performance), which will influence buyer segmentation and pricing power.
How PW Consulting can support your 2026 decisions
-
Tailored strategic workshops to convert the report’s scenarios into prioritized action plans for your organization.
-
Commercial and technical due diligence for potential acquisitions, joint ventures or long-term supply agreements, including site-level assessments and technology audits.
-
Supply-chain design and contract templates that reconcile sustainability commitments with cost competitiveness.
-
Pilot program design and delivery management to validate formulations, processing routes and quality protocols with minimal capital commitment.
Conclusion — action now, scale smart
For decision-makers planning capital allocation and market entry in 2026, the brown algae protein sector offers asymmetric upside if approached with a pragmatic, staged strategy. The market’s growth fundamentals are strong — reflected in the multi-year expansion and the forecast CAGR of 8.45% across the 2026–2032 horizon — but capture will depend on marrying technical capability with sustainable supply and rigorous commercial execution. PW Consulting’s report provides the scenario models, operational playbooks and competitive intelligence required to convert opportunity into profitable, defensible positions. To access the full set of data tables, segmentation insights and company dossiers that underpin our recommendations, consult the PW Consulting market report landing page or contact our industry practice team for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Brown Algae Protein Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Composite Sandwich Panels to Grow at 7.15% CAGR and Reach USD 8,514.6 Million by 2032
By pmarketresearch, 2026-07-13
Composite Sandwich Panels Market — 2026 Strategic Outlook and Decision Playbook
Executive summary
PW Consulting’s latest market study frames composite sandwich panels as a strategic inflection point for building, transport and aerospace OEMs and their suppliers entering 2026. The global market, with a measured progression from approximately USD 3.7 billion in 2020 to USD 5.25 billion in 2025 (base year), is projected to continue expanding at a compound annual growth rate of 7.15% through a 2026–2032 forecast horizon. By 2032 the market is expected to exceed USD 8.5 billion, underscoring a durable recovery and structural growth driven by energy-efficiency mandates, materials innovation and demand for lightweight, fire-rated envelope and structural solutions.
Composite Sandwich Panels Market
This briefing is written as a strategic “trailer”: it samples the report’s analytical depth to establish confidence in our models and conclusions, while deliberately omitting the granular sub-segment tables and region-by-application breakdowns that form the proprietary core of the full PW Consulting deliverable. Executive teams seeking the full dataset, scenario matrices and supplier-level scorecards should refer to the report landing page for access.
Composite Sandwich Panels Market
Why this report matters for 2026 corporate decisions
- CapEx prioritization: Our demand modelling links capital allocation to near-term regulatory timelines for fire and thermal performance. For firms with production decisions on the table in 2026, the report quantifies payback windows under three cost- and demand- scenarios so executives can prioritise expansions, retrofits or brownfield vs greenfield choices.
- M&A and alliance screening: A mid-consolidation market structure (CR3 ~32.5%, CR5 ~44.8%) points to pockets of opportunity for bolt-on acquisitions and technology licensing. The report supplies a prioritized shortlist of technology and capacity targets, with fit-for-purpose valuation multipliers and integration risk flags tailored to strategic buyers.
- Procurement and raw-material risk management: We provide bottom-up cost models that map composite panel BOMs to feedstock price pathways—highlighting sensitivity to polyurethane (PUR) and polyisocyanurate (PIR) foam inputs, petroleum-derived resins and the growing influence of thermoplastic core procurement. These models convert commodity scenarios into margin and pricing levers for OEMs and contractors.
- Product roadmap and certification planning: For product leaders, the report lays out a prioritized certification and product-development calendar, reflecting rising fire-safety and embodied-carbon requirements across major end-markets.
Practical contents you'll find in the full PW Consulting report
- Market-sizing and forecast model (historical 2020–2025; forecast 2026–2032) with interactive scenario toggles for price, regulation and technology adoption.
- Supply-side analytics including a supplier map, capacity-by-technology overlays, and break-even analyses for typical production lines.
- Cost build-ups for core panel configurations and sensitivity outputs to oil-price, resin supply and recycled-polyolefin adoption.
- Regulatory matrix linking regional/market compliance timelines to expected product obsolescence risk.
- Go-to-market playbooks for construction, transportation and aerospace segments, including tender-readiness checklists and sample commercial terms.
- M&A playbook: target screening, valuation yardsticks, due-diligence templates and integration checklists.
- Technology roadmap highlighting where thermoplastic cores, honeycomb innovations and recycled-material integration will create competitive edge.
Competitive landscape: who matters and what to watch
The sector features a mix of global materials players, specialized composites manufacturers and regional panel producers. This hybrid competitive set creates an environment where technical differentiation, scale and regulatory compliance capability determine value capture.
Composite Sandwich Panels Market
- Kingspan Group (Ireland): Market leader behaviorally focused on high-performance insulated panels with advanced core packages and a clear emphasis on thermal efficiency and fire safety for building envelopes.
- Hexcel Corporation (United States): Competitive differentiation in aerospace-grade honeycomb and lightweight structural panels — innovations there set performance benchmarks that cascade into other high-value transport segments.
- The Gill Corporation (United States): Specialist in multi-opening press production and tailored structural panels for aerospace and transportation OEMs.
- ArcelorMittal (Luxembourg): Traditional steel player that competes through metal-faced panel systems engineered for load-bearing, thermal and fire-rated requirements.
- Tata Steel (India) and regional manufacturers such as Assan Panel A.S. and DANA Group: These players combine localized production with portfolio breadth targeted at industrial, commercial and modular construction customers.
- 3A Composites, EconCore, Rock West Composites and advanced custom manufacturers: These suppliers focus on lightweight facings, novel core technologies and thermoplastic honeycomb solutions for architecture, transportation and industrial niches.
Recent vendor-level developments underscore the direction of travel: capacity expansions in Asia for thermoplastic fiberglass panels, new mid-temperature honeycomb cores for aircraft interiors, product launches aimed at high-thermal and load-bearing roofing, and aerospace-focused thermoplastic system certifications. These moves are consistent with a market where technology leadership and compliant product portfolios are prerequisites for winning large-volume contracts.
Materials, technology and regulation — the structural drivers through 2032
Three interconnected trends will shape returns in 2026 and beyond:
- Feedstock volatility and cost pass-through: Foam cores (PUR, PIR) along with petroleum-based resin inputs remain cost drivers; our scenario work translates oil-price shocks into margin erosion timeframes and suggests hedging and supplier diversification strategies. The broader honeycomb market—valued at roughly USD 4.35 billion in 2025—continues to be a major demand sink for the composite sandwich sector.
- Material substitution and circularity: Thermoplastic cores and recycled polyolefins are moving from pilot to production scale in targeted applications. These materials improve recyclability and cost position in high-volume transport and construction use-cases, and we map practical substitution pathways in the report.
- Stringent fire and energy regulations: Tighter fire-safety and thermal-insulation standards are compressing design windows for legacy products and elevating certified materials and tested systems. Successful suppliers are coupling R&D investments with accelerated certification timelines—this is a gating factor for market access.
Opportunities and risks for 2026 strategic plans
- Opportunities: Modular construction, retrofit programs for energy efficiency, and the electrification of transport (where lightweighting reduces energy consumption) create high-growth pockets. Suppliers offering lower embodied-carbon panels or faster on-site installation will command premium positioning.
- Risks: Raw material price spikes, non-aligned regulatory approvals across jurisdictions, and production bottlenecks for advanced core materials can delay revenue recognition. Trade measures and localized content requirements in certain markets also add complexity to global sourcing strategies.
- Mitigants: Our report recommends layered mitigations: flexible BOM designs, forward-purchase and index-linked contracts for critical feedstocks, modular manufacturing setups to accelerate local content compliance, and investment in certification-ready pilot lines to shorten time-to-market.
How commercial and technical teams should use PW Consulting’s findings
Procurement officers can apply our cost models for supplier negotiation and to construct indexed contracts tied to resin and foam benchmarks. R&D and product teams should use the technology-roadmap timelines to sequence certification investments and prioritize thermoplastic integration where lifecycle benefits are highest. Corporate development teams will find the M&A playbook and target prioritization useful for executing roll-up or capability buys within defined valuation bands.
Next steps
PW Consulting’s Composite Sandwich Panels Market report is intentionally structured to move organizations from insight to action. The full report contains the granular segmentation, regional and application breakdowns, supplier scorecards, and downloadable financial models referenced in this briefing. For decision-makers preparing 2026 budgets and strategic roadmaps, the full dataset and scenario tools are the recommended foundation for investments, procurement commitments and M&A diligence.
To obtain the complete report, detailed appendices and proprietary datasets, please visit PW Consulting’s report page or contact our industry practice for a tailored briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Composite Sandwich Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Leak Detection Equipment Market Valued at USD 4,158.5 Million in 2025, Poised to Grow at a 5.85% CAGR During 2026–2032
By pmarketresearch, 2026-07-13
Automatic Leak Detection Equipment Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As companies plan budgets, procurement and product strategies for 2026, automatic leak detection (ALD) has moved from a niche technical capability to an operational and regulatory imperative. PW Consulting’s new market study — based on a 2025 base year and projecting through 2032 — shows a market that expanded steadily through the early 2020s and is forecast to continue growing at a mid-single-digit CAGR. The market grew from roughly USD 3.1 billion in 2020 to about USD 4.16 billion in 2025, with our model projecting a rise to approximately USD 6.19 billion by 2032 at a compound annual growth rate of 5.85% (2026–2032). These headline figures understate a more nuanced reality: demand drivers are increasingly regulatory and service-led, and competitive dynamics point to selective consolidation rather than a winner-takes-all outcome (CR3 ~38.5%; CR5 ~52.7%).
Automatic Leak Detection Equipment Market
Why this report matters for 2026 decision-making
-
Compliance-driven procurement: New and tightening regulations mean that ALD is now a line-item in capital and operational project plans for refrigeration OEMs, utilities, pipeline operators and commercial real estate managers. Companies making 2026 purchasing or retrofit decisions need validated cost and deployment scenarios that reflect the new regulatory timelines.
Automatic Leak Detection Equipment Market -
Technology selection under uncertainty: Multiple sensing approaches — from acoustic and fiber-optic monitoring to pressure- and gas-based detectors — are commercially mature, but their value depends on deployment scale, asset topology and service model. Our study offers decision frameworks for selecting a technology mix that balances sensitivity, false-alarm profiles and lifecycle cost without disclosing the proprietary split-level allocations in the full dataset.
Automatic Leak Detection Equipment Market -
Channel and service strategy: For vendors and systems integrators, the opportunity is as much in recurring monitoring and managed services as it is in hardware sales. The report identifies how vendors can convert one-time equipment sales into subscription-like revenue through analytics, permanent monitoring networks and SLA-backed inspection services.
What the report contains — practical content for immediate action
-
Market sizing and methodology: A transparent reconciliation of historical volumes and value (2020–2025) with scenario-based forecasts for 2026–2032, accompanied by sensitivity ranges and model access for licensed clients.
-
Regulatory impact models: Quantified implications of recent rules (including refrigerant-focused ALD mandates and pipeline detection performance standards) on near-term demand and retrofit cycles, with timelines and cost buckets for planning CAPEX and O&M.
-
Technology due diligence playbook: Side-by-side evaluation templates that score vendor technology across detection performance, integration complexity, installation time and lifecycle cost—designed to be reused directly during RFP and pilot phases.
-
Vendor benchmarking and sourcing matrix: Comparative profiles of established and emerging suppliers, go-to-market posture and service footprint — with executable vendor shortlists for utility, industrial and refrigeration procurements (note: detailed segment allocations and vendor market shares are included in the full report only).
-
Commercial templates and case studies: Negotiation checklists, sample service agreements and retrofit phasing templates built from live project data across water utilities, pipelines, industrial sites and commercial buildings.
-
M&A and investment thesis: Deal-screening criteria and valuation approaches for investors seeking exposure to ALD hardware, software analytics platforms and managed-monitoring service businesses.
Market dynamics shaping the 2026 agenda
Three forces are creating an urgent 12–24 month agenda for buyers and suppliers alike:
-
Regulatory acceleration. Recent rulemaking has moved ALD from guidance to enforceable requirement in several end markets. Notably, refrigerant-focused mandates require automatic leak detection systems to be operational within 30 days for new commercial and industrial refrigeration appliances with large refrigerant charges (effective Jan 1, 2026), and require retrofits on a defined cadence for pre-existing equipment by January 1, 2027. Separately, pipeline safety regulators have established advanced leak detection performance standards for gas transmission systems.
-
Shift from episodic inspection to continuous monitoring. Permanent networked monitoring (including acoustic and hydrophone-based permanent loggers and fiber-optic distributed sensors) is gaining traction in high-consequence infrastructure because it reduces detection time and enables analytics-driven prioritization of field crews.
-
Service economics and lifecycle thinking. The revenue opportunity is being rebalanced toward recurring services (monitoring, verification, false-alarm management) as owners seek to convert capital outlays into predictable operational performance. Vendors that combine hardware with software subscriptions and field-service SLAs are positioned to capture disproportionately high lifetime value.
Competitive landscape — what to watch among core players
The ALD sector is characterized by a mix of specialist instrumentation firms, industrial OEMs with system-level offerings, and service-centric players. The competitive set we profile in this study — including InterTech Development Company, Veeder-Root, GUTERMANN AG, INFICON and Hermann Sewerin GmbH — illustrates the range of strategic approaches currently winning business:
-
InterTech Development Company (Skokie, IL) : A specialist in automated leak and flow test systems, InterTech’s patented mass-flow and hydraulic technologies address high-precision industrial and medical applications. Recent trade-show visibility (MD&M West, Feb 2026) highlights demand in high-speed manufacturing and medical-device leak testing where throughput and resolution are critical. Strategic implication: InterTech’s strengths fit customers prioritizing production-line speed and traceability, and the company is a logical partner for OEMs that require embedded testing in manufacturing lines.
-
Veeder-Root (Simsbury, CT) : Established in tank gauging and digital pressurized line leak detection, Veeder-Root’s solutions are recognized for regulatory compliance in fuel storage and pipeline contexts. For buyers confronting fuel and fuel-handling regulations, Veeder-Root’s systems offer a credible compliance path with mature operational support networks. Strategic implication: companies operating distributed fueling assets should prioritize vendors with demonstrated regulatory testability and field-service coverage.
-
GUTERMANN AG (Zug, Switzerland) : A leader in acoustic detection for water networks, GUTERMANN has recently expanded its permanent monitoring line with a high-sensitivity hydrophone logger launched in late 2025. This product release underlines a market shift toward permanent detection in plastic-pipe networks. Strategic implication: utilities planning long-term leakage reduction programs should evaluate permanent acoustic networks as part of asset-management roadmaps, not only as one-off detection tools.
-
INFICON (Bad Ragaz, Switzerland) : INFICON’s gas-leak detection portfolio (helium, hydrogen, refrigerant, vacuum) plays to manufacturing and service markets where trace-gas detection underpins product quality and safety. Their breadth across tracer gases positions them well where regulators or customers demand traceable leak-rate verification. Strategic implication: manufacturers with strict quality controls or service providers conducting instrumented maintenance will find INFICON’s portfolio compelling.
-
Hermann Sewerin GmbH (Gütersloh, Germany) : With acoustic correlators, ground microphones and pipe locators, Sewerin is a strong contender in utility and municipal markets. Their field-hardened tools and channel relationships with contracting crews make them a logical choice for capital projects and reactive leakage programs. Strategic implication: procurement strategies should account for the ease of integration with existing field teams and training pathways — an area where Sewerin shows strength.
Strategic recommendations for 2026
-
Start retrofit procurement cycles now. Organizations subject to the 2027 retrofit deadlines should initiate pilot and procurement processes in 2026 to avoid compressed installation windows and higher spot-market prices for field services.
-
Prioritize vendors offering integrated compliance evidence. Select solutions that not only detect leaks but also provide audit-ready records and verification workflows to reduce compliance effort and downstream inspection costs.
-
Run a technology pilot that measures both detection performance and false-alarm handling costs. Sensitivity alone is not a business-case winner; end-to-end signal-to-action time and the effort required to validate events determine the operational ROI.
-
Evaluate service-partner networks as a differentiator. For large or geographically dispersed portfolios, the availability of certified local service, calibration and emergency response should be weighted heavily in vendor selection.
-
Consider layered procurement: combine permanent monitoring in high-risk corridors with portable and periodic systems elsewhere to optimize capital and O&M spend.
-
For investors and acquirers: look for businesses combining hardware, software analytics and recurring service revenue. These hybrid models command premium multiples as markets move from capex-driven to service-centric economics.
Why PW Consulting’s analysis is different
Our research blends a rigorous bottom-up market model with practical, executable outputs that executives can use immediately. Key differentiators include scenario-calibrated forecasts anchored to recent regulatory milestones, executable procurement templates, vendor scorecards designed for RFP use, and deployment playbooks that account for field labor, permitting and verification workflows. We intentionally present headline market and concentration metrics in this brief to orient readers; the complete report contains the full regional, type and application splits, vendor market shares, and transactional datasets that underpin our conclusions.
Next steps
For procurement leads, asset owners, systems integrators and investors preparing 2026 plans, the window to influence vendor selection, pilot outcomes and compliance pathways is short. Access the full PW Consulting Automatic Leak Detection Equipment Market report to obtain the complete segmentation, vendor benchmarking tables and downloadable decision tools necessary to convert these insights into executable plans. Contact PW Consulting via our website to request the full report and a tailored briefing that maps findings to your asset portfolio and regulatory obligations.
For detailed analysis of this topic, please visit the official page: Automatic Leak Detection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Autostereoscopic Displays Market to Grow at 17.88% CAGR, Surpassing USD 5.76 Billion by 2032
By pmarketresearch, 2026-07-13
Autostereoscopic Displays Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As enterprises prepare capital allocation and product roadmaps for 2026, autostereoscopic (glasses-free 3D) displays are moving from niche showcase technology toward repeatable commercial deployments across digital signage, medical visualization, automotive cabins and premium consumer devices. PW Consulting’s forthcoming market study — anchored on a 2025 base year and projecting through 2032 — quantifies this shift and translates it into operational guidance. Our topline forecast shows the market expanding from a 2025 base into a multi‑billion dollar opportunity by 2032, driven by a compound annual growth rate of 17.88% across the 2026–2032 forecast horizon. This preview outlines the strategic value the full report delivers to boards, product chiefs, procurement teams and private investors, while intentionally holding back granular segment tables to preserve the exclusive value of the full dataset.
Autostereoscopic Displays Market
Why 2026 Is a Strategic Inflection Point
-
From a demand perspective, maturity in display optics, head- and eye-tracking, and system-on-chip integration is lowering the cost and complexity thresholds for large-format signboards, medical monitors and in-vehicle displays. Commercial pilots are moving into scaled rollouts.
Autostereoscopic Displays Market -
From a supply-side perspective, 2025–2026 is marked by policy and input-cost shocks that materially affect sourcing and margin dynamics. Recent trade and tariff actions targeting electronic components, together with concentrated production of optical films and AMOLED materials in Asia, create acute procurement risk — and procurement teams must act now to secure continuity and pricing leverage.
Autostereoscopic Displays Market -
From a competitive perspective, incumbent display OEMs and a growing set of specialist innovators are deploying differentiated technologies — lenticular optics, parallax barriers, directional backlighting, light-field systems and switchable solutions — producing a bifurcated landscape where system-level integration and application-specific validation determine winners.
What the Full Report Provides — Practical, Decision‑Ready Tools
The full PW Consulting report is built for immediate operational use by commercial leaders and investors. Key deliverables include:
-
Robust market sizing and scenario forecasts (base year 2025; forecast period 2026–2032) with demand drivers mapped to application and technology adoption curves, enabling three-tier scenario planning (conservative, base, accelerated).
-
Technology roadmaps and architecture trade-off models that compare optical approaches (lenticular, parallax, directional backlight) against light-field and switchable displays, with actionable criteria for cost, image fidelity, viewing angle, power consumption and integration complexity.
-
Procurement playbooks: supplier scorecards, total cost of ownership (TCO) calculators, contract clauses addressing tariff and IP risk, and near-term sourcing decision trees tailored to 2026 budget cycles.
-
Go-to-market playbooks for vendors and systems integrators including product positioning by application (advertising & signage, healthcare visualization, in-vehicle UX), pilot-to-scale roadmaps, pricing frameworks and channel strategies.
-
Risk matrices that translate macro-policy shocks and raw material volatility into financial sensitivities, plus mitigation templates for multi-sourcing, buffer inventory and hedging of critical optics components.
-
Investment and M&A scorecards that map IP, manufacturing capacity, customer concentration and margin profiles to acquisition valuation bands and integration risk tiers.
-
Vendor profiles and comparative capability matrices (executive summaries of market players, product strengths, distribution footprints, and go-to-market vectors) to accelerate supplier selection and partnership diligence.
Competitive Landscape — Who Matters, and How
The market structure as of 2025–2026 shows moderate concentration: the top three players account for a meaningful share of revenue, while the top five consolidate a majority position. This concentration dynamic creates both strategic advantages for incumbents and windows of opportunity for fast‑moving specialists.
-
Magnetic 3D (New York) continues to be a visible commercial force in large-format digital signage and enterprise displays. With recent product expansions into all-in-one multiview displays, the firm is prioritizing turnkey solutions for retail and experiential signage where ease-of-deployment matters most.
-
Alioscopy (Paris) remains positioned on the high end of precision lenticular optics, serving professional visualization and specialty display needs where resolution and color fidelity are non-negotiable. Its engineering-led approach and high-resolution offerings match use cases in professional design and industrial visualization.
-
Leia Inc. (USA) pushes the consumer-device angle with switchable light-field stacks and spatial AI tooling. Their platform approach — marrying hardware with spatial content tooling — is a template for consumer OEM partnerships and licensing models.
-
Dimenco (Netherlands), Barco (Belgium) and specialist groups such as 3D Global Solutions and MOPIC are leaning into vertical applications: medical visualization, endoscopic systems and secure professional displays where certified performance and domain-specific features (eye-tracking, low-latency rendering) command premium pricing.
-
Major OEMs (Samsung, LG, Philips) are experimenting with both research-grade autostereoscopic prototypes and commercial signage offerings. Their reach and channel muscle can rapidly scale proven module technology but will require product differentiation to justify above-commodity pricing.
-
New entrants and scale-ups (e.g., Zondision) are notable for integrating eye-tracking with custom ASICs — an indicator that vertical integration at the silicon level is a competitive lever for cost and performance.
Recent industry activity reinforces the above dynamics. Through late 2025 and into mid-2026 we observed multiple product introductions focused on interactive, eye-tracked autostereoscopic monitors and large-format signage demonstrations at major trade events. These launches indicate a move from technical proof-of-concept to customer-validated solutions in specific verticals.
Regulatory, Supply‑Chain and Cost Considerations Shaping Near‑Term Strategy
-
Trade policy risk is no longer hypothetical. In 2025 and early 2026, reciprocal tariffs and targeted duties on Chinese-origin electronics created immediate sourcing pressure for modules and optical films. Some exemptions exist but are temporary and subject to review — creating an imperative to stress-test supplier contracts and design dual-sourcing strategies.
-
Optical films, parallax barriers and AMOLED supply chains remain geographically concentrated. Tariff uncertainty and logistics disruptions can cascade into price increases for module BOMs; procurement teams should model 10–25% input-cost shocks in downside scenarios and prioritize inventory, multi-sourcing and design flexibility.
-
Labor and proximity advantages in Asian production continue to provide measurable cost levers. Our analysis shows that manufacturing bases in Asia often yield lower direct production cost versus Western alternatives — a material factor when evaluating whether to localize production or accept longer supply chains for high‑value systems.
Actionable 90‑Day Roadmap for Executive Teams
To translate insight into action for 2026, PW Consulting recommends this prioritized checklist for commercial and procurement leaders:
-
Complete an exposure audit: quantify component-level sourcing concentration, tariff exposure and single-supplier risks for critical optical components.
-
Initiate high-priority pilots in one vertical where your organization can capture premium pricing (e.g., healthcare visualization or premium signage); structure pilots with milestone-based purchase commitments to derisk scale-up.
-
Deploy TCO and sensitivity modeling from the report to evaluate make-vs-buy decisions, factoring in potential tariff regimes and freight constraints.
-
Open parallel supplier engagement streams: one near-term partner with established capacity and one strategic partner focused on differentiation (optics, ASICs, spatial software).
-
Lock in IP and integration terms early when engaging with module suppliers; define clear acceptance tests for viewing-angle, latency and calibration to avoid costly integration rework.
-
For investors and acquirers: use the report’s M&A scorecards to flag targets with defensible IP, validated customer pilots and scalable manufacturing roadmaps.
Why PW Consulting’s Report Is a 2026 Operational Essential
Our study blends market economics, technology assessment and procurement-grade tools into a single deliverable calibrated to the 2026 decision calendar. The forecast is granular enough to model program economics into multi-year CAPEX cycles yet delivered with templates and playbooks that enable immediate action. While this preview highlights strategic takeaways, the full report contains the detailed, machine-readable datasets, segmentation tables, vendor financials and scenario models that procurement, product and corporate development teams will require to execute confidently in 2026.
PW Consulting intentionally withholds the full segmentation matrices and certain granular split figures in this public summary to preserve the actionable value of the primary dataset. Those locked elements include itemized regional and application-level revenue splits and per-technology SKU economics — the exact inputs that underwrite procurement decisions and investment valuations.
Next Steps
For executive teams preparing budgets, product roadmaps or M&A pipelines for 2026, securing the full PW Consulting Autostereoscopic Displays Market report will provide the data and templates needed to move from strategy to procurement and commercialization. The report’s combination of validated market forecasts (2026–2032), competitive diagnostics, supplier scorecards, regulatory sensitivity analyses and operational playbooks is tailored for rapid adoption.
To access the full dataset and decision tools referenced in this preview, please visit the PW Consulting report page or contact our strategy desk for an executive briefing. The 2026 window for decisive supplier engagement, pilot conversion and portfolio positioning is narrow — market leaders will pair informed scenario planning with near-term operational moves to capture the outsized returns that a 17.88% CAGR market trajectory makes possible.
For detailed analysis of this topic, please visit the official page: Autostereoscopic Displays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com