

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Solid Fuel Testing Market Tops USD 482.5 Million in 2025, New Report Shows

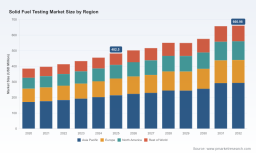
Solid Fuel Testing Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As energy markets and decarbonization pathways converge, the quality-assurance layer that sits between fuel producers, regulators, and end-users—solid fuel testing—has quietly grown into a strategic enabler. PW Consulting’s new Solid Fuel Testing Market report (base year 2025; historical 2020–2025; forecast 2026–2032) distils the commercial and regulatory forces shaping this space and translates them into decision-ready guidance for executives planning 2026 initiatives and beyond.
Solid Fuel Testing Market
Market Snapshot: A steady growth runway with important inflection points
After recovering from pandemic-era disruptions, the global solid fuel testing market reached approximately USD 482.5 Million in 2025. Our forecast models project a continuation of steady expansion through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 4.59%, taking the market to roughly USD 661 Million by 2032. This growth trajectory reflects a mix of ongoing demand for traditional coal and coke testing, expanding requirements for biomass and waste-derived fuel verification, and incremental service intensity tied to regulatory and contractual compliance.
Solid Fuel Testing Market
Market concentration is moderate: the three largest firms account for a little over one-third of the market, with the top five approaching half. This structure creates opportunities for scale players to leverage global labs and for specialized providers to defend niches through accreditation, speed-of-service, or localized sampling capabilities.
Solid Fuel Testing Market
Why this matters for 2026 decision-makers
- Strategic procurement: Fuel buyers and utilities must balance spot and contracted sourcing with evolving testing requirements. Testing providers that can demonstrate rapid, standards-aligned sampling and analysis materially reduce commercial settlement risk.
- CapEx prioritization: Investors and plant operators assessing retrofits or fuel-switching projects need defensible testing plans to model combustion performance, emissions outcomes, and ash management—inputs that materially affect ROI.
- Regulatory resilience: Shifts in emissions rules and renewable fuel mandates create step-changes in testing scope. Companies that anticipate these changes and pre-position laboratory and mobile capabilities will avoid costly scope gaps mid-contract.
Dynamics shaping the next 18–36 months
The market is being driven by four interacting vectors:
- Regulatory recalibration. Recent U.S. Environmental Protection Agency rulemaking through 2025–2026 has altered the compliance landscape for renewable fuels and mercury emissions in coal-fired units. Such revisions create near-term surges in demand for qualifying tests, retesting of legacy contracts, and verification tied to subsidy or compliance schemes.
- Fuel mix diversification. Energy transition strategies are prompting greater use of biomass, co-firing blends, and waste-derived fuels. Each fuel family brings distinct test portfolios and sampling complexities—raising the average testing touchpoint per ton of fuel delivered.
- Supply chain pragmatism. Global trade patterns, port congestion, and regional policy incentives are increasing the need for on-site testing, mobile laboratories, and rapid-turnaround certificates that minimize demurrage and allow commercial settlement confidence.
- Quality and traceability expectations. Buyers and finance providers increasingly require ISO/ASTM-aligned testing, accreditation, and traceable sampling chains as prerequisites for contracts and project financing.
Competitive landscape: capabilities, gaps, and strategic positioning
The market features a mix of global testing conglomerates, regional laboratories, and specialized niche providers. Our competitive assessment emphasizes not only breadth of services but also where capability differentials will determine market share over the next two to three years.
- Intertek Group plc (London) – Strengths: comprehensive service suite across coal, metallurgical coke, petroleum coke, and biomass with deep standards expertise (ASTM, ISO). Strategic implication: Intertek’s global testing footprint and standards advisory capabilities make it a go-to for multinational trading firms and large utilities seeking integrated audit-and-test packages.
- SGS S.A. (Geneva) – Strengths: extensive laboratory network and recent capability expansion into solid waste fuel testing. Strategic implication: SGS is well positioned to capture growth in waste-to-fuel value chains and in markets where regulators require independent verification at scale.
- Bureau Veritas (Paris) – Strengths: independent inspection and specialist testing (e.g., coke reactivity, petrography), with investments in sustainable testing capabilities. Strategic implication: Bureau Veritas is attractive to metallurgical and niche industrial users who require both physical inspection and high-complexity laboratory services.
- ALS Limited (Brisbane) – Strengths: reliable coal sampling and broad analytical suite; regional depth in Australasia. Strategic implication: AL S’s operational reliability resonates with commodity traders and exporters in geographies where consistent throughput matters.
- AmSpec Services / Control Union / McCreath Labs / Standard Laboratories – Strengths: specialized biomass testing, accredited regional labs, mobile sampling and port services. Strategic implication: These players form the backbone of niche and local market service capacity—critical when speed and accreditation are non-negotiable.
Recent capability moves exemplify the directional bets firms are making: Bureau Veritas’ advances in Ghent toward sustainable solid fuel analysis; Control Union’s ISO 17025-accredited biomass laboratory opening in Vietnam; and SGS’s expansion into solid waste fuel testing in Riga. Collectively, these moves indicate an industry pivot toward broader fuel acceptance, faster logistics-aligned testing, and credentials that underpin trade and financing.
What’s in the PW Consulting report (practical, operational, and strategic modules)
Our report is designed to be transactionally useful to commercial teams, procurement leads, laboratory managers, and investors preparing 2026 plans. The deliverables include:
- Market sizing and forecast methodology, with sensitivity analyses that stress-test outcomes under multiple regulatory and fuel-mix scenarios.
- Detailed vendor capability profiles and a proprietary scoring matrix assessing accreditation breadth, mobile sampling capacity, lab throughput, geographic coverage, and turnaround times.
- Operational playbooks: templated sampling chains of custody, typical test bundles for coal/biomass/waste-derived fuels, and recommended SLA language for commercial contracts to reduce settlement disputes.
- Compliance toolkit: checklist alignment to ASTM, ISO, and relevant regional regulatory touchpoints, plus a scenario planner for impending rule changes.
- Go-to-market and M&A intelligence: gap analysis identifying where scale acquisitions or asset-light partnerships will accelerate entry into high-growth niches.
- Buyer decision frameworks: total cost-to-serve calculators that fold in testing lag risk, demurrage exposure, and credit implications tied to disputed fuel quality.
To respect competitive sensitivity and our “trailer” approach, the report reserves the full segmentation tables, regional allocations, and granular unit values for subscribers. These tables pair with proprietary primary research to enable contract-level modeling and supplier selection decisions.
Strategic recommendations for executives planning in 2026
- For fuel buyers and utilities: Lock in multi-tier testing arrangements that combine accredited lab contracts with local mobile sampling. Prioritize providers with demonstrable rapid-turnaround certificates and electronic custody chains.
- For testing service providers: Invest in ISO/ASTM accreditations and mobile-lab assets aligned with major trading hubs. Consider targeted partnerships to cover waste-derived fuel protocols and emerging biomass specifications.
- For investors and acquirers: Target bolt-on acquisitions that deliver immediate local accreditation or logistical gain (e.g., port-based mobile crushing and sampling), rather than broad capabilities that require long integration timelines.
- For regulators and policy teams: Engage with the testing ecosystem when drafting fuel definitions and compliance timelines; clearer test-method harmonization reduces market frictions and non-compliance disputes.
Risk matrix: what could derail the outlook
- Policy volatility: Abrupt regulatory reversals or delayed implementation of renewable fuel volumes could compress near-term testing demand.
- Technology disruption: Rapid uptake of in-line, sensor-based calorific or moisture measurement could reduce lab-based test volumes unless labs evolve to provide verification and calibration services.
- Market fragmentation: Proliferation of non-accredited “certificate” providers could increase disputes—raising the value of accredited, traceable testing but pressuring margins.
How PW Consulting’s analysis converts to 2026 action plans
Clients who have previewed our executive briefing consistently highlight three tangible benefits:
- Faster supplier selection cycles through our vendor scorecards and contract templates—reducing procurement time by weeks where testing requirements are complex.
- Reduced settlement disputes via our tested chains-of-custody playbook and recommended SLAs—improving working capital predictability.
- Clarity on where to invest for capability—be it mobile lab assets, ISO accreditations, or data-integrated certificates—to capture incremental margin or de-risk fuel portfolios ahead of regulatory shifts.
Conclusion: positioning for practical resilience
The solid fuel testing market is not a headline-grabbing segment of the energy transition, but it is a foundational one: accurate, timely testing underpins commercial settlement, regulatory compliance, and the credibility of fuel-switching initiatives. With market value having expanded to just under USD 500 Million in 2026-equivalent terms and a multi-year CAGR that supports steady growth to roughly USD 661 Million by 2032, the observable pattern is clear—testing demand will track both fuel-market complexity and regulatory scrutiny.
PW Consulting’s Solid Fuel Testing Market report translates this macrotrend into concrete operational playbooks, vendor intelligence, and financial implications tailored for 2026 decision cycles. For executives who need the granular segmentation, regional allocations, and supplier-level financials to execute supplier choices or M&A plays, the full report contains the detailed datasets and scenario models that make those decisions defensible.
Next step
To access the complete dataset, vendor scorecards, and the operational toolkits referenced in this briefing, visit PW Consulting’s Solid Fuel Testing Market report page for subscribers and commissioned clients. Our team is available to run bespoke workshops that convert the report’s insights into executable 90–180 day plans aligned to your sourcing, compliance, or investment timelines.
For detailed analysis of this topic, please visit the official page: Solid Fuel Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com