

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: AC Capacitors Market Poised to Hit USD 3,970.16 Million by 2032 at a 4.85% CAGR — Asia Pacific Leads with USD 1,231.5M
By pmarketresearch, 2026-07-13
AC Capacitors Market 2026: Strategic Insights for Decisions that Matter
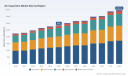
PW Consulting’s latest market intelligence on the AC capacitors sector combines rigorous historical analysis (2020–2025), a clearly defined 2026 base, and scenario-driven forecasts through 2032. The global AC capacitors market—measured in USD Million—registered steady growth to a base-year size of USD 2,850.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. By 2032 the market is expected to approach roughly USD 3,970 Million under PW Consulting’s central scenario. This briefing unpacks the strategic levers, risk vectors, and competitive dynamics that should shape executive decisions in 2026, while preserving the granular segment intelligence for subscribers who require transaction‑grade detail.
Ac Capacitors Market
Why this report matters for 2026 decision-making
- Timing: 2026 is a hinge year. With legacy industrial demand converging against accelerating electrification and efficiency regulations, procurement cycles, product roadmaps, and supplier strategies decided now will lock in cost and capability profiles for multiple years.
- Scale and momentum: The market’s trajectory from 2020 through 2025 demonstrates resilience across end markets, and our forecast to 2032 quantifies the opportunity and structural shifts executives must anticipate when allocating capital or resizing supply footprints.
- Practicality: PW Consulting’s deliverables are built to be operational—model-ready forecasts, supplier risk heat maps, scenario-adjusted price indices, and prioritized action plans tailored to common buyer and supplier archetypes.
Market trajectory: what the headline numbers reveal
Readers should treat the headline market numbers as directional imperatives. After a steady expansion to USD 2,850.0 Million in 2025, our central forecast anticipates consistent growth through the 2026–2032 period at a 4.85% CAGR, reflecting a mix of replacement demand in legacy HVAC and motor sectors, coupled with incremental gains in power-electronics and emerging industrial applications. The trajectory implies that companies with clear product differentiation, resilient supply chains, and the ability to capture adjacent power-electronics demand will outperform market averages.
Ac Capacitors Market
Two quick strategic implications flow from this profile: first, mid‑tier manufacturers and component buyers should plan capital and contract cycles around multi‑year demand steadiness rather than short-term spikes; second, diversification into power‑electronics‑grade film technologies and higher‑temperature/voltage ratings is warranted for players seeking premium positioning.
Ac Capacitors Market
Supply chain dynamics that will shape 2026 outcomes
- Raw material cost and availability: Aluminum foil and polypropylene film dynamics are the most immediate cost drivers. Recent reports indicate aluminum foil prices have risen in key production regions, and polypropylene film supply is under pressure from competing demand in packaging and electric-vehicle segments. These trends compress margins for commoditized product lines and create arbitrage opportunities for differentiated film formulations.
- Lead-time inflation: Average lead times for passive components moved to roughly 19 weeks as of late 2025. That cadence degrades responsiveness for OEMs with lean inventories, increasing the importance of buffer strategies, multi‑sourcing, and advance purchase agreements.
- Quality bottlenecks: High‑purity aluminum foil suppliers have reached etching-capacity limits in some regions, raising the strategic value of vertical integration or long-term agreements with specialty foil suppliers for firms competing in high-reliability segments.
Competitive landscape: incumbents, moves, and strategic postures
The AC capacitors market demonstrates moderate concentration: the top three companies account for approximately 28.5% of market share (CR3), while the top five reach about 39.2% (CR5). That structure indicates room for regional champions and niche specialists to prosper alongside global players.
- Barker Microfarads (BMI) — Hillsville, VA, USA: BMI’s positioning in high‑reliability motor start and run film capacitors for HVAC and motor applications is a durable asset. For 2026, BMI’s strategic playbook should focus on leveraging service, customization, and inventory responsiveness to capture premium aftermarket and retrofit demand.
- AmRad Engineering — USA: AmRad’s focus on USA-made motor run capacitors, including dual‑run offerings for HVAC, positions it well amidst resurgent onshoring and supplier‑diversification trends. Its strategic pathway should emphasize certified manufacturing capacity and targeted OEM partnerships.
- Cornell Dubilier Electronics (CDE) — Liberty, SC, USA: CDE’s broad AC film motor run and power film capacitor portfolio, combined with recent product introductions aimed at harsher environments, signals a push into higher-margin, high-reliability power-electronics niches. Expect continued product innovation and selective vertical integration.
- TDK (EPCOS) — Japan/Germany: TDK’s global scale and regulatory-compliant MotorCap portfolio are complemented by recent product launches (notably an extended X2 safety film capacitor portfolio introduced in early 2026 supporting higher AC ratings). TDK’s R&D cadence and cross-regional footprint make it a strategic standard-bearer for OEMs requiring certified, industrial-grade solutions.
- Vishay Intertechnology — Malvern, PA, USA: Vishay’s capabilities in AC film, motor run, and high‑voltage power capacitors give it an advantage in industrial and power-electronics conversions. For 2026, Vishay’s best opportunities lie in bundling capacitors with broader power modules and leveraging global distribution channels.
Recent product activity—examples include TDK’s February 2026 expansion of its X2 safety film capacitor family and Cornell Dubilier’s August 2025 release of a high‑temperature DC link capacitor—highlights a trend toward higher-voltage, higher-temperature designs suitable for demanding environments and adjacent power-electronics applications. These moves are consistent with the market’s gradual tilt toward performance differentiation.
Practical components of the PW Consulting report
The full report is structured to inform operational, commercial, and M&A decisions. Key contents include:
- Methodology and transparent market-accounting frameworks that reconcile top-down macro indicators with bottom-up supply-side intelligence.
- Historical time series (2020–2025) and scenario-based forecasts (2026–2032), with model files ready for client re-parameterization.
- Supply chain heat maps highlighting exposure to raw‑material volatility, lead‑time risk, and single‑source dependencies.
- Price and input-cost modeling aligned with polypropylene and aluminum‑foil dynamics, and sensitivity analyses that quantify margin impacts under alternative commodity regimes.
- Competitive benchmarking and capability matrices for incumbent suppliers and disruptive challengers, including technology roadmaps and go‑to‑market archetypes.
- Commercial playbooks: supplier selection checklists, negotiation levers, and procurement-timing heuristics designed for OEMs, contract manufacturers, and Tier‑1 suppliers.
- M&A and partnership diagnostics: valuation multiples, integration pitfalls, and synergy capture templates tailored to capacitor-facing assets.
How senior leaders should act in 2026
- Procurement leaders: Lock prioritized volumes on strategic film types now while maintaining optionality through secondary suppliers. Structure contracts to share commodity upsides or to include indexed pricing bands to protect margins.
- Product and engineering: Prioritize modular capacitor platforms that can be tuned for higher temperature/voltage ratings with limited requalification cost—this reduces time‑to‑market for OEMs reacting to new industrial and power-electronics requirements.
- Operations and supply chain: Reassess lead-time buffers and inventory policies with the expectation of extended procurement cycles; invest in forecasting fidelity and supplier development where high-purity foil or specialty film is a bottleneck.
- Corporate development: Evaluate tuck-ins that add differentiated film technologies or regional manufacturing capacity, focusing on assets that shorten qualification cycles for key OEMs.
Readership note — what we are intentionally withholding here
This communication is a strategic preview intended to demonstrate analytical depth while preserving the transactional intelligence that makes PW Consulting’s full report a decision-enabling asset. We have therefore intentionally omitted detailed segment-level splits, specific regional revenue breakdowns, and granular application‑level dollar values from this release. Subscribers to the complete report receive the full segmentation matrix, disaggregated time-series, and downloadable model files required to execute procurement, engineering, and M&A plays in 2026.
Closing: the actionable edge for 2026
For executives weighing capital allocation, supplier selection, or product roadmaps in 2026, the AC capacitors market presents a balance of steady growth and targeted disruption. The headline market expansion to roughly USD 3,970 Million by 2032 (central scenario) at a 4.85% CAGR masks meaningful shifts in supplier economics, technology thresholds, and lead-time realities that will determine winners and laggards. Companies that pair disciplined procurement strategies with selective engineering investments in higher-performance film and safety-rated capacitors will capture disproportionate value.
To access the full dataset, proprietary segmentation, scenario models, and supplier dossiers that underpin these conclusions, please consult PW Consulting’s full Ac Capacitors Market report. The complete deliverable is engineered to convert insight into executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ac Capacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Semiconductor-Grade Tungsten Powder Market Set to Grow at 9.15% CAGR from 2026 to 2032
By pmarketresearch, 2026-07-13
Semiconductor Grade Tungsten Powder Market: Strategic Imperatives for 2026 — PW Consulting Report Briefing
Executive Summary
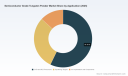
PW Consulting’s new market intelligence brief on the Semiconductor Grade Tungsten Powder Market synthesizes an integrated view of supply, demand, pricing dynamics, regulatory shocks, and supplier strategy to inform corporate decisions in 2026. Anchored by a rigorous dataset spanning 2020–2025 and a detailed forecast through 2032, the report documents a clear multi-year acceleration: the market expanded from roughly USD 385 million in 2020 to about USD 565 million in 2025 and is modeled to exceed USD 1.04 billion by 2032, tracking a compound annual growth rate of 9.15% over the forecast horizon. This release outlines the strategic value of the analysis for C-suite executives, procurement leads, and M&A teams while intentionally withholding granular segment tables to encourage full report engagement.
Semiconductor Grade Tungsten Powder Market
Why This Matters for 2026 Decision-Makers
- Procurement resilience: Recent upstream disruptions have exposed single-point vulnerabilities in tungsten feedstocks. Procurement strategies calibrated to 2026 realities must balance spot exposure with structured long-term offtakes and diversified supplier panels.
- Capital allocation: Strong market growth and rising material intensity across advanced packaging and deposition processes create selective opportunities for capacity expansion, downstream integration, and targeted vertical investments.
- Regulatory and supply-chain risk management: Export controls and feedstock concentration have immediate pricing and availability consequences; companies that preemptively model regulatory scenarios will preserve product roadmaps and time-to-market for critical nodes.
Market Trajectory: Data-Driven Context (High Level)
Our historical sizing shows steady, demand-led expansion through 2020–2025, accelerating as semiconductor content per device climbs and advanced deposition and metallization techniques proliferate. The 2026–2032 forecast, derived from bottom-up modelling across technology adoption curves and wafer fab investment plans, produces a 9.15% CAGR for the period. This trajectory reflects both secular semiconductor demand and episodic supply-side shocks that have structurally tightened availability of semiconductor-grade tungsten powder.
Semiconductor Grade Tungsten Powder Market
Dynamics: Supply Shocks, Pricing, and Feedstock Stress
- Export controls and upstream feedstock volatility: In early 2025, restrictive export measures on key tungsten intermediates were introduced, resulting in material licensing requirements that materially reduced export volumes. The consequences cascaded through the supply chain and were a principal driver of a multi-fold rise in market prices for semiconductor-grade powders during 2025–2026.
- Feedstock scarcity and pricing spikes: The principal upstream intermediate, ammonium paratungstate (APT), saw unprecedented price swings in the period following tightened exports. Certain reporting windows registered several-hundred-percent jumps, forcing downstream buyers to reprice product roadmaps and re-evaluate procurement contracts.
- Near-term market tightness vs. structural growth: While short-term tightness is primarily supply-driven, structural demand from advanced node manufacturing, 3D integration, and specialty deposition techniques (CVD/ALD and sputtering use-cases) underpins the medium-term growth path.
Competitive Landscape: Who Moves Markets
The semiconductor-grade tungsten powder market is concentrated and technical barriers to entry are meaningful. The competitive field combines legacy refractory metals specialists, integrated producers, and regionally anchored manufacturers. Our concentration analysis indicates a compact top tier, with the leading three and five suppliers controlling a substantial portion of market throughput—an important consideration when evaluating counterparty risk and bargaining power.
Semiconductor Grade Tungsten Powder Market
- Buffalo Tungsten Inc. (Depew, NY) — A specialized high-purity tungsten metal powder producer with strengths in niche, high-reliability applications. Its focus on quality and traceability positions it well for semiconductor supply chains that emphasize material provenance.
- Global Tungsten & Powders Corp. (Towanda, PA) — A western producer with multi-site production capability. Recent product introductions tailored for semiconductor applications signal an emphasis on differentiated chemistries and tighter tolerances for electronic-grade usage.
- Elmet Technologies LLC (Lewiston, ME) — Vertically integrated production from oxide to powder, offering control over impurity profiles and the flexibility to meet bespoke customer specifications.
- H.C. Starck Tungsten Powders (Goslar, Germany / Mitsubishi Materials) — A supplier emphasizing recycling and closed-loop material strategies; recently reported a notable recycling rate that serves both sustainability goals and feedstock security.
- Kennametal Inc., Edgetech Industries, AEM Metal, Stanford Advanced Materials, Atlantic Equipment Engineers, Japan New Metals, and major Chinese producers — Each brings distinct capabilities across particle engineering, spherical powder forms, and scale production. Collectively, these firms form a supply map with different technical specializations and geopolitical footprints.
Recent corporate activity reinforces market shifts: a product launch focused explicitly on semiconductor-grade powders by a major western supplier and operational disclosures on recycling rates by a leading manufacturer are symptomatic of a broader pivot—suppliers are investing in both technical differentiation and resilience-focused strategies.
Report Contents: Practical, Actionable Deliverables
PW Consulting’s full report is built for executables: it moves beyond narrative to deliver playbooks and decision tools you can use in 2026. Key inclusions are:
- Methodology and transparent assumptions behind the 2026–2032 forecast and scenario variants.
- Supply chain heat maps and supplier scorecards that quantify technical capabilities, geopolitical exposure, and capacity elasticity.
- Procurement playbooks with negotiation levers: contract structures, hedging approaches, and buyer-supplier partnership models tailored to tungsten powder markets.
- Pricing model that decomposes input cost drivers (including APT trajectories), conversion yields, and margin pass-through mechanics under alternative regulatory scenarios.
- Technology tracker that maps particle-level innovations, purity regimes, and deposition compatibility to end-market adoption timelines.
- M&A and investment thesis annex: target profiles, valuation sensitivities, and integration risk checklists.
- Risk matrix and regulatory scenario planning: probability-weighted impacts of export policy shifts, feedstock embargoes, and substitution risks.
Strategic Recommendations for 2026
Our analysis translates into eight priority actions for executives planning around the 2026 inflection point:
- Formalize multi-tiered sourcing strategies: Combine secure long-term allocations with tactical spot exposure; prioritize suppliers with demonstrable supply-chain traceability and redundant processing locations.
- Invest in feedstock flexibility: Where feasible, retrofit or design process lines to accept alternate tungsten chemistries or particle morphologies to reduce single-source dependency.
- Capitalize on supplier consolidation: Use the market’s concentrated supplier base to negotiate performance-based agreements, but recognize the counterparty pricing power when appetite for capacity is tight.
- Prioritize technical partnerships: Co-develop powder grades or particle treatments that improve yield or compatibility with advanced deposition methods—this can create defensible differentiation and thinner cost pass-throughs.
- Embed regulatory scenario planning into product roadmaps: Shorten decision cycles for qualification runs and maintain modular approval paths to mitigate sudden material substitutions.
- Explore recycled-content strategies: Recycled tungsten is emerging as both a supply buffer and an ESG lever; partnership opportunities exist with operators reporting high recycling rates.
- Gate M&A decisions with supply-chain analytics: Targets should be evaluated not only on EBITDA accretion but also on feedstock control, facility footprint, and qualification backlog for semiconductor customers.
- Monitor pricing corridors: Apply dynamic cost-pass-through models in customer contracts where possible to preserve margins during elevated volatility windows.
How We Built the View
The forecast uses a hybrid approach combining bottom-up adoption curves for semiconductor deposition and metallization processes, detailed supplier capacity modelling, and scenario-driven stress tests of supply chain interruption events. We triangulated industry data, proprietary supplier interviews, and third-party commodity pricing intelligence to create a defensible, decision-focused output.
Conclusion: Navigating a Strategic Inflection
The semiconductor-grade tungsten powder market sits at a strategic inflection: structural demand growth is meeting episodic supply-side constraints and tighter regulatory oversight. For companies dependent on these materials, 2026 is a year to translate scenario planning into executed strategies—whether through procurement playbooks, targeted investments, supplier partnerships, or selective M&A. PW Consulting’s comprehensive report provides the data, frameworks, and executable recommendations to make those choices with confidence.
Next Steps
This briefing is intended as an executive prelude. The full PW Consulting report contains the granular segmentation, supplier scorecards, and actionable playbooks referenced above. For access to the complete intelligence package, scenario workbooks, and bespoke advisory engagements tailored to your organization’s role in the tungsten powder value chain, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Semiconductor Grade Tungsten Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Advanced Cardiovascular Life Support Market to Reach USD 9,179.77 Million by 2032, Driven by an 8.5% CAGR
By pmarketresearch, 2026-07-13
Advanced Cardiovascular Life Support Market: Strategic Intelligence for 2026 Decision-Making
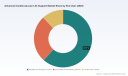
PW Consulting today releases an executive briefing drawing on our forthcoming Advanced Cardiovascular Life Support (ACLS) Market report — a practical intelligence package designed to inform boardroom choices and operational plans as companies enter a pivotal 2026 planning window. Our analysis synthesizes historical behavior, clinical and policy inflection points, technology integration trends, and competitive positions to translate market momentum into actionable options. At a macro level, the global ACLS market expanded from roughly USD 3.45 billion in 2020 to an estimated USD 5.19 billion in 2025 and is forecast to grow to approximately USD 9.18 billion by 2032, representing a compound annual growth rate (CAGR) of 8.5% over the forecast period.
Advanced Cardiovascular Life Support Market
Why this report matters for 2026 strategy
- Timing of investment and product launches: The intersection of updated clinical guidance, reimbursement policy changes, and accelerating adoption of system-level integrations creates a narrow opportunity window for vendors that can align product roadmaps and market access plans quickly. Our report identifies the highest-leverage moves for calendar 2026, from prioritizing integrated mechanical CPR/monitor interfaces to reallocating R&D toward multi-modality defibrillation strategies.
- Risk-adjusted forecasting: We combine top-down growth assumptions with scenario-driven adoption curves to surface upside and downside outcomes for capital allocation, making it easier to size bets on platform upgrades, training businesses, and consumables portfolios without overcommitting to any single channel.
- Competitive posture and consolidation playbook: Concentration analysis shows a moderately consolidated market structure (CR3 and CR5 metrics), where the leading incumbents command significant share. Our report translates that structure into tactical guidance on partnership, niche differentiation, and M&A targeting to accelerate access to closed distribution networks and high-volume training customers.
- Regulatory and reimbursement sensitivity: Recent guideline and payment updates have immediate and medium-term implications for device specifications, training programs, and hospital procurement cycles. The report maps these regulatory levers to revenue lines so business leaders can prioritize compliance-driven product enhancements and policy advocacy.
Data-driven insights without the spoilers
We intentionally provide robust macro sizing and growth projections to support capital planning while preserving the tactical segmentation detail for licensed report users. The headline numbers above—historic growth and projected scale—are sufficient to justify strategic choices such as expanding integrated monitoring-defibrillation platforms, investing in advanced simulation capabilities, or building a consumables subscription model. The granular region- and application-level allocations, and precise product revenue splits, are reserved for the full report to protect competitive value and to guide tailored go-to-market programs.
Advanced Cardiovascular Life Support Market
What the PW Consulting ACLS report contains (operationally focused)
- Validated market sizing and methodology — transparent assumptions, data sources, and a reconciled top-down/bottom-up approach so finance teams can plug numbers into corporate plans.
- Scenario modelling and sensitivity analysis — three adoption scenarios (baseline, accelerated, conservative) with elasticities for reimbursement variation, guideline-driven adoption, and capital equipment replacement cycles.
- Commercial playbooks — prioritized GTM options for incumbent OEMs, mid-market challengers, and training providers, including channel strategies, bundling tactics (device + training + consumables), and service revenue pathways.
- Regulatory & reimbursement tracker — a rolling view of guideline updates, payer coding changes, and procurement policy shifts with immediate operational implications for product design and clinical claims.
- Technology roadmaps & interoperability matrices — assessment of device integration maturity, interface standards, and recommended engineering priorities for next-generation ACLS systems.
- Training and workforce impact analysis — a practical playbook for scaling simulation and instructor networks, converting training to recurring revenue, and aligning certification offerings with updated clinical algorithms.
- Competitive intelligence dossiers — granular vendor profiles, recent strategic moves, and capability maps that position each competitor against the critical buying criteria used by hospitals, EMS providers, and cardiac centers.
- M&A heatmaps and partnership targets — prioritized lists based on capability gaps, distribution reach, and cultural fit to accelerate inorganic growth or protect core franchises.
Competitive landscape: what incumbents are doing now
The ACLS vendor ecosystem blends large diversified medtech players with specialized simulation and training firms. Our competitive chapter profiles strategic postures across product development, channel control, and clinical engagement.
Advanced Cardiovascular Life Support Market
- ZOLL Medical Corporation (Chelmsford, MA) — Strengths: integrated defibrillation and mechanical CPR solutions that map closely to updated ACLS workflows. Recent product integrations demonstrate a deliberate push to deliver seamless mechanical CPR feedback within advanced monitor ecosystems.
- Philips Healthcare (Amsterdam) — Strengths: strong footprint in both public access and professional defibrillator segments, with emphasis on guidance-driven CPR features and analytics to support quality-of-care programs.
- Medtronic plc (Dublin) — Strengths: depth in cardiac rhythm management and pacing tools used in ACLS bradycardia scenarios; well-positioned to capture demand tied to hemodynamic support protocols.
- GE HealthCare (Chicago) — Strengths: systems-level monitoring and defibrillation integration for hospital workflows; opportunity to leverage enterprise contracts for cross-selling critical-care monitoring upgrades.
- Laerdal Medical, Nasco Healthcare, Prestan Products, Gaumard Scientific — Strengths: leaders in high-fidelity simulation and hands-on training tools. Their products are central to hospital and EMS training pipelines, and they are increasingly strategic partners for OEMs seeking to bundle training with devices.
- Stryker (Physio-Control) and Abbott Laboratories — Strengths: LIFEPAK defibrillators and rhythm/hemodynamic support portfolios, respectively, with durable field and hospital penetration; both maintain strong clinical relationships that influence procurement cycles.
These firms collectively shape a market where the top three vendors account for a meaningful share of sales and the top five further concentrate distribution influence. That concentration affects pricing dynamics, tender outcomes, and the speed at which new clinical recommendations convert to purchasing decisions.
Regulatory and clinical context driving short- and mid-term demand
- Guideline shifts: The 2025 American Heart Association (AHA) Guidelines for CPR and Emergency Cardiovascular Care introduced changes—such as updated defibrillation strategies and additional emphasis on mechanical circulatory support—which are now being operationalized in provider training and product specifications. ACLS provider materials and instructor manuals were subsequently updated, creating an immediate demand pulse for revised training content and compatible devices.
- Reimbursement changes: Medicare policy updates for CY 2026 altered coding and payment parameters for certain rhythm-management and defibrillator-related procedures. These changes affect hospital procurement economics and may accelerate adoption of devices that demonstrably reduce downstream costs or shorten length of stay.
- Clinical-tech convergence: New recommendations on defibrillation approaches (e.g., double sequential strategies in refractory ventricular fibrillation) and the growing acceptance of integrated mechanical CPR solutions require design and interoperability changes that favor vendors with flexible platforms and strong clinical evidence generation capabilities.
Practical implications for commercial leaders
- Prioritize interoperable platforms: Buyers increasingly value turnkey solutions that reduce cognitive load during resuscitation—integrated monitors, coordinated mechanical CPR feedback, and unified data capture are rising procurement priorities.
- Monetize training: Certification and simulation services are natural recurring-revenue complements to capital sales. Vendors that can offer verified competency outcomes will unlock stickier customer relationships.
- Prepare for procurement cycles: Updated guidelines and payer policy changes will influence hospital budgeting timelines. Make sure clinical evidence packages and health-economic dossiers are ready ahead of tender rounds.
- Use M&A selectively: Where distribution bottlenecks exist, targeted acquisitions of training networks, regional distributors, or niche product lines can accelerate market entry and defend pricing.
How PW Consulting helps
Our ACLS Market report couples sector expertise with practical tools for execution: executable GTM plans, financial models you can import into corporate planning systems, and a regulatory tracker updated through the forecast period. For managers preparing 2026 budgets or revising three-year product plans, the report reduces uncertainty by mapping clinical, policy, and competitive drivers to demand scenarios and margin implications.
Next steps
This briefing is structured to give senior leaders the evidence and framing necessary to act in 2026 while preserving the commercial value of segment-level intelligence. For full access to the detailed regional, product, and end-user splits, as well as downloadable financial models and the complete competitive dossiers, please consult the PW Consulting Advanced Cardiovascular Life Support Market report on our website or contact your PW Consulting representative to arrange a tailored briefing.
For detailed analysis of this topic, please visit the official page: Advanced Cardiovascular Life Support Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Medical Silicone Vasculature Models Market Poised for 7.51% CAGR as 3D‑Printed Solutions Lead Growth
By pmarketresearch, 2026-07-13
Medical Silicone Vasculature Models Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As healthcare systems, device makers, and academic centers accelerate their investments in simulation, device validation, and patient-specific planning, the medical silicone vasculature models market is entering a phase of sustained, structurally driven growth. PW Consulting’s forthcoming in-depth market study — covering historical dynamics (2020–2025) and a forward-looking forecast (2026–2032) — synthesizes commercial, technical, and regulatory vectors that will shape boardroom decisions through 2026 and beyond.
Medical Silicone Vasculature Models Market
Macro trajectory: calibrated expansion, predictable runway
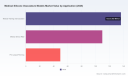
The market has expanded steadily in recent years and is projected to continue on that trajectory, with a compound annual growth rate (CAGR) of approximately 7.5% across the 2026–2032 forecast window. Our base-year view (2025) provides the anchor for scenario planning: an observable step-change between 2024–2025 that amplifies through the early forecast years, driven by converging trends — increased procedural volumes leveraging simulation, broader adoption of patient-specific models for pre-surgical planning, and deeper integration of silicone phantoms into device R&D and regulatory testing workflows.
Medical Silicone Vasculature Models Market
For decision-makers preparing capital allocation, product roadmaps, or M&A activity in 2026, these dynamics mean the market is large enough to justify targeted investments while remaining accessible to specialized entrants with superior IP or vertical integration strategies.
Medical Silicone Vasculature Models Market
Why this report matters to 2026 corporate strategy
-
Actionable commercial intelligence: We translate macro growth into prioritized market-facing plays — where to invest in tooling, which route to market delivers the fastest payback, and how to price differentiated offerings in a market that values anatomical fidelity and regulatory traceability.
-
Operational readiness: The report contains practical manufacturing and supply-chain diagnostics — from LSR (liquid silicone rubber) procurement sensitivity to cycle-time benchmarking for 3D-printed versus molded paths — to reduce time-to-revenue for new SKUs.
-
Regulatory and validation playbooks: We map ISO and ASTM test gates and synthesize FDA guidance implications for simulated-use testing of neurovascular and cardiovascular devices, enabling product and quality teams to anticipate validation timelines.
-
Competitive positioning and M&A scouting: With a moderate level of market concentration among leading vendors, the study highlights attractive acquisition targets, partnership archetypes, and white-space opportunities for incumbents and new entrants.
What’s inside — a practical, implementable research toolkit
The report is structured to be immediately usable by strategy, product, and commercial teams. Key deliverables include:
-
Market sizing and scenario modeling: A base-case forecast plus upside and downside scenarios that stress-test demand drivers (clinical adoption rates, reimbursement shifts, device R&D budgets) through 2032.
-
Segmentation framework: End‑use and technology segmentation with adoption curves for 3D-printed, molded, and hybrid silicone composites — enabling prioritized resource allocation without requiring you to extrapolate raw data.
-
Detailed supplier and raw-material analysis: Sensitivity analysis on medical-grade LSR pricing and its effect on gross margin in typical manufacturing configurations, including break-even maps for small-batch patient-specific production versus scale molded manufacturing.
-
Regulatory alignment checklists: Crosswalks between device testing protocols (including ISO 7198 and ASTM F2477) and emergent FDA recommendations on simulated use for neurovascular devices — imperative for filing timelines and clinical validation strategies.
-
Commercial playbooks: Go‑to‑market options by buyer cohort (academic centers, hospitals, device OEMs, training academies), sample commercial agreements, service-addition bundles, and recommended pricing architecture to defend premium propositions.
-
M&A and partnership playbooks: Due diligence templates focusing on IP, process maturity, and clinical validation repositories, plus integration checklists to capture synergies from software, imaging, and model manufacturing consolidation.
Competitive landscape — key players and strategic postures
The market is moderately concentrated: the top three and top five suppliers together account for a meaningful minority share of global revenues, underscoring both the presence of established leaders and room for differentiated challengers. Below we synthesize the strategic positioning of core industry participants that we profile in the report.
-
United Biologics (Irvine, CA) — Positioned around proprietary material formulations, their anatomically representative silicone models emphasize fidelity for endovascular and interventional training. Strategically, their strengths are IP-led material differentiation and close alignment with OEM procedural demonstration needs.
-
BDC Laboratories (Wheat Ridge, CO) — Focused on engineered compliant vessels and simulation-ready anatomy, BDC is notable for testing partnerships with device developers. Their trade-show visibility and applied R&D make them an attractive partner for device validation pipelines.
-
TrandoMed (Ningbo, China) — A high-volume 3D printing specialist with a strong presence in neuro, coronary, and peripheral simulation. TrandoMed’s cost-position and manufacturing scale support OEMs and training networks looking for patient-specific model programs at competitive price points.
-
Elastrat (Geneva, Switzerland) — European supplier with emphasis on material transparency and a portfolio suited for education, research, and device development. Their product breadth supports academic collaborations and multi-center simulation studies.
-
Mentice (Gothenburg, Sweden) — Integrated simulation provider combining software-enabled training platforms with patient-specific models. Mentice’s bundled solution approach is notable for customers seeking turnkey simulation ecosystems.
-
Preclinic Medtech (Shanghai) , MedScan3D (Galway) , and Swiss Vascular (Zurich) — These specialized producers focus on high-fidelity, patient-specific phantoms and niche anatomical models, with Swiss Vascular’s ETH Zurich spin-out dynamics highlighting an academic-to-commercial pipeline that investors and strategic acquirers should track closely.
Recent signals that matter for 2026 planning
-
New company launches and product introductions from academic spin-outs point to accelerating innovation in anatomical accuracy and imaging-to-model throughput — critical for firms focused on clinical adoption and OEM validation partnerships.
-
Continued trade-show and conference activity by established labs demonstrates that live demonstrations and hands-on validation remain the dominant channel for enterprise customer acquisition.
-
Raw-material cost pressure (medical-grade LSR) and standardized testing protocols (ISO/ASTM) are creating an operational imperative: suppliers must optimize material utilization and demonstrate compliance-ready validation packages to remain competitive.
Strategic implications and recommended 2026 actions
PW Consulting recommends a prioritized action set for CEOs, Heads of Product, and Corporate Development teams preparing for 2026:
-
Invest selectively in material science or partner for differentiation: Where premium pricing is available, proprietary silicone formulations or validated blends that better mimic vessel compliance and translucency will command a premium in training and device testing segments.
-
Build modular manufacturing capability: Hybrid production lines that combine small-batch 3D-printed processes for patient-specific models with higher-throughput molding for standardized curricula balance flexibility and cost-efficiency.
-
Prioritize regulatory-ready validation kits: Bundling standardized testing protocols, sample reports aligned to ISO/ASTM, and simulated-use test artifacts accelerates OEM adoption and shortens procurement cycles.
-
Consider targeted M&A and partnerships: Acquire or partner with imaging-to-model software specialists, or regional manufacturing partners to accelerate market access, particularly where local clinical validation is a barrier to adoption.
-
Differentiate through services: Training curricula, subscription-based model refresh programs, and cloud-enabled procedural analytics increase customer lifetime value and create recurring revenue streams.
What to expect from the full report
This preview highlights the strategic levers and competitive contours we see shaping 2026 decisions. The complete PW Consulting report delivers the full empirical foundation: year-by-year market sizing, granular segmentation by technology and application, company-level profiles with growth benchmarks, and downloadable due-diligence templates. We deliberately withhold certain granular split figures in this public release to preserve the utility of the subscription content that contains actionable breakouts and region-application matrices valuable to commercial negotiators and M&A advisors.
How to use this intelligence
For executives preparing budgets, negotiating partnerships, or executing M&A in 2026, the decision calculus should be anchored in three measures: time-to-clinical-validation, cost-per-model at scale, and the ability to demonstrate regulatory-compliant test artifacts. Our full report transforms those high-level priorities into executable plans — including supplier scorecards, margin impact tables, and a 12–24 month implementation roadmap for product launches or integration post-acquisition.
PW Consulting will be publishing the complete Medical Silicone Vasculature Models Market Report with extended data tables, proprietary forecasts, and tactical playbooks. To receive the full report and executive briefing materials, please visit our official report page for access and licensing options.
For clients seeking a rapid executive briefing or a tailored implications workshop (60–90 days), our lead analysts are available to co-develop a 2026 action plan grounded in the study’s scenario workstreams.
For detailed analysis of this topic, please visit the official page: Medical Silicone Vasculature Models Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Ceramic Glass Market to Climb from USD 2.15B in 2025 to USD 3.28B by 2032 at a 6.2% CAGR — Asia‑Pacific Leads with USD 978.7M
By pmarketresearch, 2026-07-13
Ceramic Glass Market 2026: Strategic Imperatives from PW Consulting’s Market Research
PW Consulting today releases a comprehensive Ceramic Glass Market Research briefing—designed as a decision-grade instrument for corporate strategy teams, product leaders, procurement heads and private equity investors preparing plans in 2026. Built on a 2025 base and a 2026‑2032 forecast horizon, the study incorporates historical performance from 2020–2025 and projects the market forward at a compound annual growth rate (CAGR) of 6.2%. Our bottom‑up modeling shows the global market expanding from approximately USD 1,605.4 Million in 2020 to USD 2,150.0 Million in 2025 and further toward a projected USD 3,275.7 Million by 2032.
Ceramic Glass Market Research
Why this report matters for 2026 decision cycles
-
Timing: 2026 is a junction year where product innovation (transparent, strengthenable covers and large-panel substrates), regulatory pressure, and raw material volatility converge. Leadership teams must translate technical roadmaps into commercial milestones within this window.
Ceramic Glass Market Research -
Capital allocation: With steady mid‑single-digit CAGR and differentiated pockets of high technical intensity, firms face choices between volume-driven capacity investments and high-margin, IP‑led product plays. Our analysis clarifies which choices are value accretive under multiple scenarios.
Ceramic Glass Market Research -
Supply chain resilience: Raw material shifts, recyclability pilots and geopolitical sourcing risks require new procurement strategies; the report provides scenario-driven hedging and sourcing options mapped to cost and service outcomes.
-
M&A and partnership signal: Market concentration—where the top three and top five players capture meaningful shares—creates both entry barriers and targeted acquisition opportunities. Our deal‑screening tools prioritize targets that accelerate access to high-value end markets.
Market dynamics and growth drivers
The sector’s 6.2% CAGR through the forecast reflects a confluence of demand vectors: next‑generation consumer electronics seeking ultrathin, damage‑resistant cover systems; steady replacement cycles in household and professional appliances; and rising adoption in semiconductor packaging and industrial technical applications. Recent product introductions and scale‑ups underscore this direction: transparent, strengthen‑able ceramics for mobile devices and expanded cooktop product lines with improved surface durability are moving from lab to factory floor.
At the same time, regulatory and sustainability initiatives are reshaping market pull. European circular‑economy policies and packaging directives are nudging certain segments toward glass‑based solutions and incentivizing end‑of‑life recovery. Manufacturing pilots converting post‑consumer glass‑ceramic shards back into production are now credible industrial options. Together with raw material trends—where high‑purity silica and soda ash remain foundational feedstocks and lithium price adjustments have altered the economics of certain formulations—these dynamics change both product specification and sourcing strategy.
Competitive landscape: incumbents, challengers and strategic postures
The industry exhibits moderate to high concentration: the three largest firms command a significant portion of installed value, and the five largest firms consolidate an even larger share, creating a landscape where scale, proprietary processes and customer relationships matter. These dynamics create distinct strategic archetypes:
-
Technology and IP leaders (e.g., Corning Incorporated): Inventors and scale players are leveraging deep R&D to push new material architectures. Recent launches signal a move into nanocrystalline structures designed for next‑generation foldable and drop‑resilient devices—an area with steep technical barriers and attractive margins.
-
Specialist high‑performance producers (e.g., SCHOTT AG, Nippon Electric Glass): Firms with domain expertise in cooktop panels, precision substrates and astronomy‑grade products are scaling differentiated lines—matte finishes, large‑panel core substrates—addressing both consumer aesthetics and industrial performance.
-
Regional volume competitors (select manufacturers across Asia): Cost‑competitive producers are focusing on volume cooktops and architectural applications; their role is pivotal in anchoring commodity volumes and creating price tension in less differentiated product tiers.
-
Adjacency and materials integrators (e.g., Saint‑Gobain, Elan Technology, CoorsTek): These players bridge ceramics, glass‑ceramics and engineered composites, enabling cross‑market rollouts such as hermetic seals and hybrid assemblies in electronics and industrial systems.
Notable recent developments captured in our research include high‑profile product launches and capacity moves that signal commercial readiness: a major multinational announcing a transparent glass‑ceramic cover product for mobile devices, further refinement and serial production of matte cooktop panels, and new large‑panel core substrate developments aimed at advanced semiconductor packages. Collectively, these moves reduce technology risk for select pathways and raise competitive stakes for incumbent supply agreements.
Technology trajectories and manufacturability constraints
Two technical trends will shape winners and losers. First, structural tailoring at the micro‑ to nanoscale (e.g., nanocrystalline matrices) is unlocking combinations of transparency, toughness and thermal stability suited to high‑growth end markets. Second, advances in panel production—larger formats, better surface finishes and integrated coatings—are increasing unit economics for appliance OEMs and design‑led consumer brands.
Manufacturing constraints—thermal processing capacity, furnace cycle times, and feedstock purity requirements—translate directly into lead times and minimum efficient scales. Our plant‑level cost models quantify these constraints and identify where incremental investments yield step‑change returns versus where process innovation is required.
Supply chain, raw materials and sustainability implications
-
Inputs: High‑purity silica sand (SiO2 > 99.5%) remains a non‑substitutable input for many virgin formulations; soda ash continues as a key feedstock, and lithium price shifts have opened room for alternative formulations in certain high‑temperature glasses.
-
Recycling and circularity: Pilots demonstrating remelting of post‑consumer shards are now moving to scale trials—presenting OPEX and carbon benefits for early movers that can secure reverse logistics.
-
Risk zones: Geographic concentration of feedstock processing and energy intensity of furnaces expose producers to electricity pricing and trade policy. Our risk heatmaps highlight where nearshoring or dual‑sourcing materially reduces disruption exposure.
Strategic recommendations for 2026
-
Prioritize hybrid investment strategies: balance small, rapid pilots in high‑margin product lines (transparent, thin, high‑value ceramics) with selective capacity plays in stable appliance volumes.
-
Negotiate conditional raw material arrangements: lock-in pricing collars for key inputs while preserving flexibility to shift to recycled feedstock as pilots commercialize.
-
Target M&A and JV targets that de‑risk technology pathways—look for assets offering large‑panel capability, unique coating processes, or proven recycling workflows.
-
Embed regulatory and sustainability scenarios into product roadmaps: align near‑term launches with circular economy incentives in major markets to capture early adopters and preferred supplier status.
-
Develop supplier‑backed R&D partnerships: co‑fund scale‑up of advanced glass‑ceramic formulations to accelerate time‑to‑market and to secure preferential supply of differentiated materials.
-
Invest in commercial analytics and pricing engines: use value‑based pricing where technical performance is the buying criterion and cost‑plus for commodity tiers.
What the PW Consulting report delivers — operationally ready
This market study is intentionally pragmatic. Beyond market sizing and our 2026–2032 forecast framework, the deliverables include:
-
Value chain decomposition and plant‑level cost models to support capex decisions;
-
Competitive mapping and IP landscape to inform partnership and licensing strategies;
-
Technology deep dives on nanocrystalline, large‑panel substrates, surface finishes and hermetic composites;
-
Supply‑risk heatmaps and raw material scenario models incorporating recent lithium and soda ash dynamics;
-
Commercial playbooks—go‑to‑market roadmaps for household appliance OEMs, consumer electronics partners and semiconductor companies;
-
M&A target shortlists and valuation priors calibrated to different growth and margin cases;
-
Executive workshops and a customizable financial model to stress‑test strategic options.
How to use this intelligence in 2026
Executives should treat the report as a decision architecture: feed its scenarios into 3‑5 year product roadmaps, capital allocation plans, and procurement contracts. Corporate development teams can use our target screening and valuation drivers to accelerate diligence; procurement teams can use the raw material scenarios to justify hedging or recycling investments; R&D leaders will find the technical roadmaps useful for prioritizing formulations that align with customer willingness‑to‑pay.
Our approach follows the “trailer” principle—this release surfaces the strategic implications and major, validated trajectories while preserving detailed segmentation tables, per‑product and regional spend breakdowns, and granular pricing curves for subscribers and report purchasers. Those datasets are essential for finalizing contract terms, performing detailed financial due diligence, or executing tactical supplier shifts.
To explore the full dataset, model files and scenario workbooks that underpin the analysis, and to access tailored advisory support from PW Consulting’s ceramic glass practice, download the full report or contact our advisory team. The 2026 strategic window presents both risk and asymmetric opportunity—this research is designed to convert market signals into executable advantage.
For detailed analysis of this topic, please visit the official page: Ceramic Glass Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Integrated Optical Delay Line Market to Expand at a 7.5% CAGR, Fueling Growth in Defense, Telecommunications and Data Centers
By pmarketresearch, 2026-07-13
Integrated Optical Delay Line Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on Integrated Optical Delay Lines (IODLs) synthesizes five years of historical performance and a seven-year forecast to 2032, delivering a concise strategic lens for C-suite executives, product leaders, and investors preparing decisions in 2026. This briefing presents the high‑level market trajectory, critical technology and supply‑chain inflection points, and the competitive moves that will shape opportunities — while preserving the full segment-level granularity for subscribers to the full report.
Integrated Optical Delay Line Market
Market snapshot — a market in steady expansion
At the macro level, the IODL market is transitioning from research‑led experimentation toward selective commercial adoption across telecommunications, microwave photonics, lidar, sensing, and emerging quantum transduction applications. The market expanded materially through the early 2020s, with a compound annual growth trajectory that we model at 7.5% across the forecast horizon. PW Consulting’s base-year alignment to 2025 and our 2026–2032 forecast show continuing growth pressure driven by broader system‑level needs for compact true‑time delay, reduced latency, and improved integration density.
Integrated Optical Delay Line Market
For context, the market’s maturation is evident in its revenue progression from the early 2020s into 2025 and the subsequent forecast to 2032. This steady growth underpins strategic choices in R&D allocation, capacity planning, and M&A timing: it is large enough to attract multi‑disciplinary entrants, yet not so commoditized as to eliminate premium pockets for differentiated material platforms, packaging approaches, and integrated module offerings.
Integrated Optical Delay Line Market
Why this matters for 2026 strategy
- Timing of commercialization vs. scale: 2026 is the inflection year where early technical demonstrations and pilot deployments meet the pragmatic demands of system integrators. Organizations must decide whether to move from prototyping partnerships into captive capability or to secure long‑lead supply agreements with specialist foundries and module suppliers.
- Capital allocation tradeoffs: With a mid‑single‑digit CAGR and clear pockets of high‑value applications (e.g., defense, high‑end telecom, and quantum transduction), companies must prioritize between targeted vertical plays and broader horizontal product lines. PW Consulting’s scenario models help quantify payback horizons under different go‑to‑market paths.
- Platform bets matter: Material-platform choices and foundry partner selection determine future feature sets (loss, thermal stability, footprint) and cost curves. Our analysis shows that low‑loss waveguide platforms and multimode silicon photonic approaches are unlocking new delay densities; however, packaging and thermo‑mechanical stability remain decisive for field reliability.
Technology and supply‑chain dynamics to watch
Technical advances and foundry availability are key constraints and enablers in 2026. Recent work on multimode silicon photonics demonstrates a pathway to break traditional delay‑density limits, while electro‑optic transducer innovations broaden the addressable application set into quantum and microwave‑to‑optical domains.
- Foundry & process readiness: Multi‑project wafer (MPW) services and 220‑nm SOI process nodes are enabling compact, mm²‑scale delay implementations suitable for system integration. Decision‑makers should assess foundry roadmaps and MPW cadence as part of any near‑term ramp plan.
- Material choices: Silicon‑on‑insulator, silicon nitride, and lithium niobate each offer distinct tradeoffs across loss, bandwidth, and integration complexity. Low‑loss waveguides (<0.1 dB/m) are becoming table stakes for ns‑scale delays in many use cases.
- Packaging & integration: The gulf between chip demonstration and productized module is dominated by packaging, connectorization, and thermal control. Suppliers that combine optical design with robust mechanical and electrical integration will command premium positioning.
- Standards & controls: Industry standards advocating low‑loss and thermal stability are raising the bar for fielded products. Concurrently, export controls on precision photonic components for dual‑use radar and quantum systems will shape market access strategies and supplier geographies.
Competitive landscape — focused, but with white space
The IODL market exhibits moderate concentration: the top three suppliers account for a meaningful portion of current revenues, and the top five increase that share further. This concentration underscores the presence of established technology providers while leaving room for specialized entrants and regional players to capture niche value.
Key industry participants highlighted in our research illustrate distinct go‑to‑market models and technical emphases:
- Enablence Technologies (Ottawa): Specializes in planar lightwave circuit (PLC) implementations enabling ultra‑long delay lines in compact footprints. Their recent partnership to supply PLC chips for FMCW LiDAR sensor makers signals a clear commercialization vector into automotive and robotics sensing stacks.
- IBM (Armonk): Approaches IODLs from a research and systems perspective, focusing on electro‑optic transducers and integration pathways for quantum transduction and microwave‑to‑optical conversions. Their patent activity reflects strategic intent to lower decoherence and insertion loss in high‑precision applications.
- Microwave Photonic Systems (MPS) (West Chester): Targets RF and radar systems with packaged photonic delay solutions optimized for wide bandwidths and fieldable integration — a useful model for defense and communications primes.
- Agiltron (Woburn): Provides modular delay products with user interfaces and high‑resolution switching, offering system integrators a lower‑risk path to prototype and pilot deployments.
- G&H (Gooch & Housego) (Ilminster): Focuses on custom fiber optic assemblies and small‑form‑factor variable optical delay lines, representing the bridge between fiber‑based incumbents and emerging on‑chip approaches.
Recent developments reinforce the pattern: partnerships aligning component specialists with system integrators, patent grants signaling strategic IP plays in quantum and transduction, and university demonstrations pushing technical boundaries. Taken together, these moves indicate an ecosystem evolving from academic demonstrations to commercially structured value chains.
Risk vectors and regulatory considerations
Strategic plans in 2026 must factor in several non‑market risks that materially affect timing and market access:
- Export controls and dual‑use scrutiny: High‑precision delay solutions used in radar and quantum systems are increasingly scrutinized under export control frameworks. Early engagement with compliance and licensing teams is mandatory for companies targeting cross‑border sales.
- Standards compliance: IEEE and related photonics standards are converging on low‑loss and thermal stability benchmarks. Products that do not meet emerging normative requirements will face adoption resistance in conservative telecom and defense procurement cycles.
- Supply chain concentration: Dependence on a narrow set of foundries or specialty material suppliers exposes programs to capacity constraints and lead‑time volatility. Diversified multi‑foundry strategies and qualification roadmaps are prudent hedges.
What the PW Consulting report contains — practical, decision‑grade deliverables
To preserve the signal in this preview while guiding actionable next steps, the full Integrated Optical Delay Line Market report provides the following practitioner‑oriented modules:
- Detailed market model (historic 2020–2025; forecast 2026–2032) with scenario toggles for adoption curves, price erosion, and application mix. (High‑level figures are summarized in this briefing; subscriber access unlocks the interactive model.)
- Competitive benchmarking with vendor diagnostic matrices across technology platform, packaging maturity, IP posture, and commercial readiness.
- Go‑to‑market playbooks tailored to three archetypes: system integrator, component foundry, and diversified OEM — including channel strategies, sample‑to‑production timelines, and recommended partner archetypes.
- Supplier selection framework and RFQ checklist for qualifying foundries, material vendors, and assembly partners — designed to shorten qualification cycles and reduce time‑to‑field risk.
- Regulatory & risk assessment with mitigation pathways for export control, standards compliance, and dual‑use governance.
- Investment and M&A due diligence template, including prioritized diligence questions for IP, tech transfer readiness, and integration costs.
Note: consistent with the preview principle, we intentionally omit the detailed region, application and type‑level revenue breakdowns from this summary. The full report includes those subsegment tables, growth shares, and sensitivity testing that underpin the strategic recommendations above.
Actionable recommendations for 2026
- Map capability to application economics: Prioritize platform investments that align with near‑term, high‑margin applications (defense, specialized telecom cores, and quantum systems). Use pilot partnerships to de‑risk packaging and thermal control before committing to full volume ramps.
- Secure foundry and packaging options early: Negotiate capacity reservations or preferred MPW slots with foundries that support your chosen substrate and process. Concurrently, qualify at least two packaging partners to de‑risk single‑vendor exposure.
- Protect and scout IP thoughtfully: Combine defensive patenting where necessary (e.g., transduction or integration methods) with active scouting of university consortia for emerging multimode and low‑loss techniques.
- Integrate compliance into commercial planning: Build export control and standards compliance into product roadmaps and tender responses to avoid late‑stage market exclusions.
- Use modular commercialization: Where feasible, offer modularized delay units or turnkey modules to accelerate adoption by system integrators while preserving optionality for future integration into custom SoCs.
Next steps — how PW Consulting can help
For leadership teams preparing 2026 investment rounds, product roadmaps, or M&A diligence, PW Consulting offers tailored engagements ranging from rapid market validation sprints to full commercial readiness programs, including access to the interactive market model, vendor scorecards, and our scenario analyses. The full report contains the subsegment revenue tables, competitive shares, and downloadable financial models necessary for board and investor presentations.
To obtain the comprehensive Integrated Optical Delay Line Market report and unlock the granular segmentation, sensitivity analyses, and supplier scorecards referenced in this preview, please visit the PW Consulting reports portal or contact our industry team for a briefing tailored to your strategic context.
Closing observation
Integrated optical delay lines are moving from a technical novelty toward selective commercial utility. The market’s steady mid‑single‑digit CAGR reflects this balance: meaningful growth and opportunity, but with decisive differentiation driven by platform choice, packaging excellence, and compliance-aware commercialization. Organizations that align product strategy, foundry partnerships, and regulatory planning in 2026 will capture preferential positions as the market expands through the early 2030s.
For detailed analysis of this topic, please visit the official page: Integrated Optical Delay Line Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PWM DC Motor Speed Controller Market Valued at USD 385.5 Million in 2025, Poised for 6.42% CAGR to 2032 as Asia‑Pacific Leads with USD 166.34 Million
By pmarketresearch, 2026-07-13
PWM DC Motor Speed Controller Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market brief on the PWM DC Motor Speed Controller market is purpose-built to inform the strategic choices that will define competitive positions through 2026 and beyond. Drawing on a comprehensive historical base (2020–2025) and forward-looking modeling for the 2026–2032 forecast window, this report synthesizes market sizing, technology trajectories, supply-chain pressure points, and a pragmatic set of action plays for OEMs, semiconductor suppliers, distributors, and private-equity sponsors. The market narrative is clear: a steady expansion, material structural shifts in supply and standardization, and concentrated pockets of opportunity for companies that align product, channel and cost strategies.
Pwm Dc Motor Speed Controller Market
Headline market dynamics (what the numbers tell us)
At the macro level, the PWM DC motor speed controller market has displayed stable growth across the past half-decade. Our reconstructed market sizing moves from a modest base in 2020 to a stronger position in 2025, reflecting the cumulative effects of industrial automation rollouts, higher content per vehicle, and proliferation of robotics and consumer-electronics use cases. Under our central forecast, the market expands at a compound annual growth rate (CAGR) of 6.42% across 2026–2032, with the total market progressing meaningfully through the forecast horizon.
Pwm Dc Motor Speed Controller Market
Two structural observations underpin the quantitative outlook. First, demand is broad-based: industrial and automotive applications continue to drive volume and value, while emerging pockets—medical automation, collaborative robotics, and advanced consumer products—lift ASPs through higher integration and richer feature sets. Second, supplier concentration remains moderate: the top three vendors comprise roughly a third of global revenue, while the top five account for under half of the market—indicating an industry where large semiconductor suppliers coexist with specialized module makers and regional integrators.
Pwm Dc Motor Speed Controller Market
Why this briefing matters for 2026 choices
For leadership teams making capital allocation, product roadmap, or M&A decisions in 2026, the strategic value of this report lies in three concrete capabilities:
- Market-context sensitivity: We map how macro drivers—standard updates, component-cost cycles, and end-market demand—combine to affect near-term supply and two- to three-year product economics.
- Decision-grade scenarioing: The report contains scenario P&Ls and cash-flow sensitivities that show how raw-material cost shocks, ASP compression, or feature-led premiumization change internal rate of return (IRR) on new product investments.
- Go-to-market playbooks: The research translates market structure into practical bets on channel partnerships, co-design arrangements with Tier-1s, and inventory buffering strategies to protect margins during supplier volatility.
What’s inside the full PW Consulting report (high-level)
The published study is intentionally operational, not merely descriptive. Its primary modules include:
- Methodology and data-pack: transparent modeling assumptions, raw-market input series from 2020–2025, and our top-line forecast for 2026–2032 with sensitivity bands.
- Technology and product taxonomy: functional breakdown of PWM architectures (integrated ICs, MOSFET-based modules, H-bridge topologies), thermal-management patterns, and cost-builder models for bill-of-materials (BoM) and manufacturing cost per unit.
- Competitive scorecards: vendor capability matrices, route-to-market strengths, and a supplier risk heatmap concentrating on lead times, capacity constraints, and certification readiness.
- Industry forces and regulatory pathing: implications of global standards and directives on product design, testing and time-to-market.
- Actionable strategic options: product-development roadmaps, M&A target lists, and channel strategies calibrated to different investor profiles and corporate ambitions.
To preserve competitive advantage for report subscribers, the public summary intentionally omits granular split tables and complete segmentation dashboards; these are available through our client portal and subscription channels.
Competitive landscape — who matters and why
The PWM DC motor speed controller market is characterized by a mix of large semiconductor houses, specialized analog and power-systems vendors, and a cohort of module and board-level suppliers serving niche segments. The recent product and certification moves underscore the ongoing race for differentiation through integration, current sensing, and software-enabled control.
- Infineon Technologies AG: Recognized for strong power MOSFET portfolios and integrated motor-control ICs, Infineon’s showcase of modular PWM motor-control solutions at recent trade events reinforces its traction in industrial-grade, high-reliability applications.
- STMicroelectronics N.V.: Continues to expand its low-voltage and battery-optimized PWM driver family; recent launches target portable and battery-powered devices where efficiency and footprint are decisive.
- Texas Instruments Incorporated: Focuses on current-sensing and dual H-bridge chips that enable precise speed regulation in demanding motor-control scenarios, moving aggressively into higher-current integrated solutions.
- Analog Devices, Inc.: Leverages mixed-signal strengths to deliver controllers optimized for robotics and precision automation where latency and control fidelity matter.
- ON Semiconductor, ROHM, Toshiba, NXP, and Microchip: Together, these companies cover a spectrum from fan-and-pump controllers to automotive-grade pre-driver and certified parts—each differentiating by reliability, cost, or automotive qualification.
- Pololu, Cytron, and Dimension Engineering: Represent the module- and system-level tier—supplying ready-to-use controllers for hobbyist, industrial prototyping, and small-scale robotics applications.
Recent vendor developments through late 2025 (product launches, certification updates, and trade-show debuts) indicate intensifying feature competition: dual H-bridge designs with higher peak currents, low-voltage drivers for battery operation, and broader AEC-style qualifications for automotive adoption. These moves are reflected in the scorecards contained in the full report.
Supply-chain and standards: tailwinds and headwinds
Three forces will materially shape execution risk and margin dynamics in 2026:
- Component-cost volatility: Power-semi inputs are experiencing supply tightness—silicon wafer pricing for power MOSFET manufacture has risen materially, and copper remains a high-cost input for inductors. Our BoM sensitivity module quantifies the margin delta from realistic swings in these inputs.
- Regulatory and standards pressure: Updated interoperability and safety requirements (for example, mandates on adjustable PWM control in industrial drives) increase the bar for product certification and functional safety verification, while RoHS compliance updates tighten materials-selection choices for CE market access.
- Thermal-management constraints: High-current controllers require more sophisticated junction-temperature management and system-level design to avoid MOSFET failures; our engineering appendix translates thermal requirements into PCB, heatsink, and firmware-control implications.
Strategic implications and recommended plays for 2026
Our analysis yields a short list of priority actions for executives looking to capture upside and mitigate downside in 2026:
- Prioritize modularization and software: Invest in scalable firmware architectures and modular hardware that allow quicker tailoring to automotive, industrial, and medical safety requirements—this compresses time-to-revenue and raises switching costs for customers.
- Hedge critical inputs: Negotiate multi-year wafer and copper contracts or secure capacity through strategic alliances with substrate and passive suppliers to limit BoM volatility exposure.
- Certification-first product roadmaps: For firms targeting automotive and industrial segments, front-load AEC and IEC compliance work to avoid backward revisions that delay commercial launches.
- Targeted M&A and partnerships: For companies seeking scale, pursue add-on buys in module manufacturing or firmware specialists rather than broad tuck-ins—this preserves margin expansion potential and accelerates access to end markets.
- Route-to-market optimization: Rebalance distributor vs direct-sales mixes by segment: maintain tight inventory buffers for high-turn SKUs and adopt just-in-time approaches for low-volume, high-spec products.
What the full report unlocks (and how to access it)
PW Consulting’s full PWM DC Motor Speed Controller Market report provides the granular datasets, vendor scorecards, and scenario modeling that underpin the insights summarized here—specifically the detailed segmentation dashboards, competitive benchmarking by SKU, and downloadable BoM-cost models that the public summary omits. Subscribers also receive an executive briefing and a customizable slide kit for board-level discussions.
If your 2026 plan requires defensible numeric justification for R&D allocation, M&A target screening, or channel strategy shifts, the full dataset and our scenario engine will supply that rigor. Visit our report landing page to review the table of contents, methodology, and options for subscription or tailored advisory engagements.
Concluding note: positioning for resilient growth
The PWM DC motor speed controller market is neither a rapid bubble nor a static commodity space; it is a steadily expanding domain where product differentiation, thermal and safety design competence, and upstream supply management decide winners. The current market structure—with moderate concentration and meaningful pockets of specialization—favors companies that combine semiconductor-scale efficiencies with system-level integration and certification expertise. PW Consulting’s study equips decision-makers with the quantitative and qualitative tools needed to make those bets prudently in 2026.
For access to complete segmentation tables, in-depth vendor scorecards, and our scenario workbooks, please follow the link on PW Consulting’s research portal—detailed intelligence and client engagements are available on request.
For detailed analysis of this topic, please visit the official page: Pwm Dc Motor Speed Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.43% CAGR for Wall Mount Electric Cabinet Market Through 2032
By pmarketresearch, 2026-07-13
Wall Mount Electric Cabinet Market — Strategic Preview for 2026: PW Consulting Insights
Executive summary
As businesses prepare strategic investments in 2026, understanding the trajectory of the global wall mount electric cabinet market is becoming mission‑critical for OEMs, distributors, system integrators and large end‑users. Our latest analysis shows the market achieved an estimated USD 6.48 billion in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of approximately 5.43% through the 2026–2032 forecast window, moving the industry toward a notably larger addressable base by 2032. This release is a strategic “trailer”: it highlights the decisive trends, competitive moves, and operational levers that will shape boardroom decisions in 2026 while preserving the granular segment-level datasets and models that we publish in the full report.
Wall Mount Electric Cabinet Market
What the PW Consulting report delivers (practical, decision‑ready content)
- Top‑line market sizing and forward scenarios that reconcile macroeconomic sensitivity, raw material shocks, and alternative adoption curves for IoT/edge deployments.
- Actionable go‑to‑market playbooks for product, channel and aftermarket strategies—tailored by product architecture and end‑use intensity.
- Supplier and contract playbooks including hedging templates for steel exposure, cost‑to-serve optimization matrices, and sourcing scorecards for critical components.
- Regulatory and standards compliance checklist—operational steps to accelerate certification and reduce time‑to‑market risks (including IEC and regional type approvals).
- M&A and partnership heatmaps identifying integration synergies, capability gaps, and valuation sensitivities relevant to bolt‑on and platform deals.
- Practical dashboards and financial models: margin impact scenarios for premiumized enclosures (e.g., IoT‑enabled, corrosion resistant, IP/IK rated), and a set of KPI triggers for course correction.
Market dynamics to watch in 2026
Several converging forces will determine winners and losers next year. We summarize the most consequential dynamics and translate them into short‑term action items for leadership teams.
Wall Mount Electric Cabinet Market
- Structural growth with selective premiumization. The market is growing at a mid‑single digit CAGR driven by steady gains in industrial automation, expansion of distributed energy assets, and rising demand for edge computing enclosures. Within this growth, premium features—higher IP/IK ratings, corrosion‑resistant materials, integrated thermal management and pre‑configured modularity—are commanding materially higher margin capture for those who can justify the value through reliability and reduced installation time.
- Raw material and labor cost pressure. Cold‑rolled steel volatility and a measurable rise in skilled labor costs for electrical fabrication are compressing traditional cost structures. Procurement teams should assume higher baseline material prices and plan supplier contracts with graded pass‑through or hedging clauses. Parallel investments in fabrication automation offer a multi‑year ROI to neutralize rising labour scarcity.
- Regulatory and energy‑efficiency constraints shaping product architecture. International standards governing empty enclosures and regional energy directives are pushing manufacturers to integrate cooling and climate‑control compatibility into base designs. Compliance is now table stakes, and early certification pathways reduce friction for cross‑border commercial expansion.
- Edge computing and IoT as differentiators. Suppliers integrating connectivity and edge‑ready architectures (sensors, pre‑wired PoE, thermal management telemetry) are moving from commodity vendors to platform providers. This creates aftermarket revenue pathways—remote monitoring, predictive maintenance services and lifecycle upgrades—if vendors can demonstrate measurable uptime benefits.
- Competitive consolidation but room for regional specialists. The market shows moderate consolidation: a group of established global vendors command a sizeable share, yet there remains opportunity for regional players who can deliver tailored solutions, rapid lead times and localized certification support.
Competitive landscape — how incumbents are positioning
We track both product innovation and go‑to‑market moves by leading vendors. Several themes emerge from recent company activity and product roadmaps.
Wall Mount Electric Cabinet Market
- Platformization and connectivity. Global players are layering IoT readiness onto traditional mechanical enclosures. Product updates from major suppliers demonstrate a clear push to embed connectivity and edge compute support—enabling these vendors to capture aftermarket service revenues and strengthen customer stickiness.
- Certification and regional adaptation. Achieving local certifications (UL/NEMA, regional Type approvals) has become a deliberate route to market share in industrial geographies. Certification wins materially reduce time‑to‑adoption by large industrial accounts with strict procurement standards.
- Modular design and thermal integration. Recent launches emphasize modular interiors, climate control integration, and compatibility with standardized cutouts for power and communication modules—features which accelerate contractor installation and reduce field engineering costs.
- Value and cost leadership at scale. Some manufacturers continue to compete on cost and lead time with economical NEMA/metal and non‑metallic offerings for high‑volume projects, preserving margin through scale and process efficiency.
Strategically, these moves suggest three distinct competitive archetypes: (1) platform providers monetizing services and connectivity, (2) certification‑led regional champions focused on industrial buyers, and (3) scale‑driven cost leaders serving commodity volume channels. Each archetype requires a discrete product, channel and operational playbook.
Recent industry developments with immediate implications
- Trade show and product launches continue to accelerate modularity and integration features—indicating an industry response to contractor time‑to‑install pressures.
- Major suppliers are renewing certification portfolios for key regional markets, lowering adoption barriers for large industrial projects.
- Measured increases in raw material prices and labor costs are shifting procurement programs from spot buys to multi‑year strategic contracts—those who act early will secure better cost baselines.
Strategic imperatives for 2026 decision‑makers
Based on our scenario analysis and client engagements, we recommend a pragmatic set of priorities for C‑suite and commercial leaders:
- Prioritize product architectures that reduce total installed cost. Focus R&D on modular pre‑wiring, standardized mounting plates, and thermal readiness. These features shorten onsite integration time and create premium pricing opportunities.
- Hedge raw material exposure through a three‑tier sourcing strategy. Combine long‑term agreements with alternate suppliers and qualified substitutes (e.g., selective non‑metallic composites for specific use‑cases) to manage price and lead‑time risk.
- Accelerate certification pipelines. Secure IEC and regional type approvals early—this pays dividends with large industrial and utility accounts where procurement cycles favor pre‑qualified suppliers.
- Define an IoT monetization path. If embedding connectivity, articulate a clear value proposition tied to uptime and OPEX savings. Pilot programs with marquee customers can accelerate learning and create reference cases for broader rollout.
- Invest in manufacturing resilience. Adopt targeted automation for high‑skill welding and finishing operations, paired with flexible cell architectures to shift capacity between metallic and non‑metallic lines.
- Design M&A and partnership plays around capability gaps. Identify small technology and service providers who can plug into platform roadmaps—particularly those with proven field analytics, thermal modelling or rapid certification processes.
How PW Consulting supports 2026 decisions
Our report equips leadership teams with the analytical tools and practical templates required to convert market signals into executable plans. Clients gain:
- Market sizing and sensitivity models calibrated to multiple macro scenarios and regional recovery shapes.
- Benchmarks and negotiation templates to optimize procurement of raw materials and outsourced fabrication.
- Roadmaps for product development, certification, and pilot commercialization of IoT and thermal management features.
- M&A diligence packages and integration playbooks focused on rapid time‑to‑value.
Note: this briefing purposefully omits the detailed segment‑level metrics and regional splits from the full dataset. The published report contains those granular tables, supplier scorecards and downloadable financial models required to operationalize the recommendations above.
Call to action
For executives mapping 2026 budgets and strategic moves: treat this market as a medium‑growth, margin‑opportunity segment where first movers on certification, modularity and IoT readiness capture disproportionate value. Access to the full PW Consulting report will deliver the precise segmentation, pricing ladders and supplier performance matrices you need to finalize capital plans, procurement strategies and potential acquisition targets.
Conclusion
In 2026 the wall mount electric cabinet market will reward disciplined strategic execution: companies that combine product premiumization, disciplined procurement and certification velocity will accelerate market share gains and margin expansion. PW Consulting’s research synthesizes macro trends, competitive activity and operational levers into decision‑ready guides—enabling leadership teams to move from hypothesis to action with confidence. For the full dataset, granular regional and application breakdowns, and plug‑and‑play financial models, consult the complete market report.
For detailed analysis of this topic, please visit the official page: Wall Mount Electric Cabinet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com