

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Integrated Optical Delay Line Market to Expand at a 7.5% CAGR, Fueling Growth in Defense, Telecommunications and Data Centers

Integrated Optical Delay Line Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on Integrated Optical Delay Lines (IODLs) synthesizes five years of historical performance and a seven-year forecast to 2032, delivering a concise strategic lens for C-suite executives, product leaders, and investors preparing decisions in 2026. This briefing presents the high‑level market trajectory, critical technology and supply‑chain inflection points, and the competitive moves that will shape opportunities — while preserving the full segment-level granularity for subscribers to the full report.
Integrated Optical Delay Line Market
Market snapshot — a market in steady expansion
At the macro level, the IODL market is transitioning from research‑led experimentation toward selective commercial adoption across telecommunications, microwave photonics, lidar, sensing, and emerging quantum transduction applications. The market expanded materially through the early 2020s, with a compound annual growth trajectory that we model at 7.5% across the forecast horizon. PW Consulting’s base-year alignment to 2025 and our 2026–2032 forecast show continuing growth pressure driven by broader system‑level needs for compact true‑time delay, reduced latency, and improved integration density.
Integrated Optical Delay Line Market
For context, the market’s maturation is evident in its revenue progression from the early 2020s into 2025 and the subsequent forecast to 2032. This steady growth underpins strategic choices in R&D allocation, capacity planning, and M&A timing: it is large enough to attract multi‑disciplinary entrants, yet not so commoditized as to eliminate premium pockets for differentiated material platforms, packaging approaches, and integrated module offerings.
Integrated Optical Delay Line Market
Why this matters for 2026 strategy
- Timing of commercialization vs. scale: 2026 is the inflection year where early technical demonstrations and pilot deployments meet the pragmatic demands of system integrators. Organizations must decide whether to move from prototyping partnerships into captive capability or to secure long‑lead supply agreements with specialist foundries and module suppliers.
- Capital allocation tradeoffs: With a mid‑single‑digit CAGR and clear pockets of high‑value applications (e.g., defense, high‑end telecom, and quantum transduction), companies must prioritize between targeted vertical plays and broader horizontal product lines. PW Consulting’s scenario models help quantify payback horizons under different go‑to‑market paths.
- Platform bets matter: Material-platform choices and foundry partner selection determine future feature sets (loss, thermal stability, footprint) and cost curves. Our analysis shows that low‑loss waveguide platforms and multimode silicon photonic approaches are unlocking new delay densities; however, packaging and thermo‑mechanical stability remain decisive for field reliability.
Technology and supply‑chain dynamics to watch
Technical advances and foundry availability are key constraints and enablers in 2026. Recent work on multimode silicon photonics demonstrates a pathway to break traditional delay‑density limits, while electro‑optic transducer innovations broaden the addressable application set into quantum and microwave‑to‑optical domains.
- Foundry & process readiness: Multi‑project wafer (MPW) services and 220‑nm SOI process nodes are enabling compact, mm²‑scale delay implementations suitable for system integration. Decision‑makers should assess foundry roadmaps and MPW cadence as part of any near‑term ramp plan.
- Material choices: Silicon‑on‑insulator, silicon nitride, and lithium niobate each offer distinct tradeoffs across loss, bandwidth, and integration complexity. Low‑loss waveguides (<0.1 dB/m) are becoming table stakes for ns‑scale delays in many use cases.
- Packaging & integration: The gulf between chip demonstration and productized module is dominated by packaging, connectorization, and thermal control. Suppliers that combine optical design with robust mechanical and electrical integration will command premium positioning.
- Standards & controls: Industry standards advocating low‑loss and thermal stability are raising the bar for fielded products. Concurrently, export controls on precision photonic components for dual‑use radar and quantum systems will shape market access strategies and supplier geographies.
Competitive landscape — focused, but with white space
The IODL market exhibits moderate concentration: the top three suppliers account for a meaningful portion of current revenues, and the top five increase that share further. This concentration underscores the presence of established technology providers while leaving room for specialized entrants and regional players to capture niche value.
Key industry participants highlighted in our research illustrate distinct go‑to‑market models and technical emphases:
- Enablence Technologies (Ottawa): Specializes in planar lightwave circuit (PLC) implementations enabling ultra‑long delay lines in compact footprints. Their recent partnership to supply PLC chips for FMCW LiDAR sensor makers signals a clear commercialization vector into automotive and robotics sensing stacks.
- IBM (Armonk): Approaches IODLs from a research and systems perspective, focusing on electro‑optic transducers and integration pathways for quantum transduction and microwave‑to‑optical conversions. Their patent activity reflects strategic intent to lower decoherence and insertion loss in high‑precision applications.
- Microwave Photonic Systems (MPS) (West Chester): Targets RF and radar systems with packaged photonic delay solutions optimized for wide bandwidths and fieldable integration — a useful model for defense and communications primes.
- Agiltron (Woburn): Provides modular delay products with user interfaces and high‑resolution switching, offering system integrators a lower‑risk path to prototype and pilot deployments.
- G&H (Gooch & Housego) (Ilminster): Focuses on custom fiber optic assemblies and small‑form‑factor variable optical delay lines, representing the bridge between fiber‑based incumbents and emerging on‑chip approaches.
Recent developments reinforce the pattern: partnerships aligning component specialists with system integrators, patent grants signaling strategic IP plays in quantum and transduction, and university demonstrations pushing technical boundaries. Taken together, these moves indicate an ecosystem evolving from academic demonstrations to commercially structured value chains.
Risk vectors and regulatory considerations
Strategic plans in 2026 must factor in several non‑market risks that materially affect timing and market access:
- Export controls and dual‑use scrutiny: High‑precision delay solutions used in radar and quantum systems are increasingly scrutinized under export control frameworks. Early engagement with compliance and licensing teams is mandatory for companies targeting cross‑border sales.
- Standards compliance: IEEE and related photonics standards are converging on low‑loss and thermal stability benchmarks. Products that do not meet emerging normative requirements will face adoption resistance in conservative telecom and defense procurement cycles.
- Supply chain concentration: Dependence on a narrow set of foundries or specialty material suppliers exposes programs to capacity constraints and lead‑time volatility. Diversified multi‑foundry strategies and qualification roadmaps are prudent hedges.
What the PW Consulting report contains — practical, decision‑grade deliverables
To preserve the signal in this preview while guiding actionable next steps, the full Integrated Optical Delay Line Market report provides the following practitioner‑oriented modules:
- Detailed market model (historic 2020–2025; forecast 2026–2032) with scenario toggles for adoption curves, price erosion, and application mix. (High‑level figures are summarized in this briefing; subscriber access unlocks the interactive model.)
- Competitive benchmarking with vendor diagnostic matrices across technology platform, packaging maturity, IP posture, and commercial readiness.
- Go‑to‑market playbooks tailored to three archetypes: system integrator, component foundry, and diversified OEM — including channel strategies, sample‑to‑production timelines, and recommended partner archetypes.
- Supplier selection framework and RFQ checklist for qualifying foundries, material vendors, and assembly partners — designed to shorten qualification cycles and reduce time‑to‑field risk.
- Regulatory & risk assessment with mitigation pathways for export control, standards compliance, and dual‑use governance.
- Investment and M&A due diligence template, including prioritized diligence questions for IP, tech transfer readiness, and integration costs.
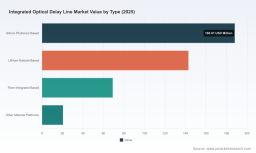
Note: consistent with the preview principle, we intentionally omit the detailed region, application and type‑level revenue breakdowns from this summary. The full report includes those subsegment tables, growth shares, and sensitivity testing that underpin the strategic recommendations above.
Actionable recommendations for 2026
- Map capability to application economics: Prioritize platform investments that align with near‑term, high‑margin applications (defense, specialized telecom cores, and quantum systems). Use pilot partnerships to de‑risk packaging and thermal control before committing to full volume ramps.
- Secure foundry and packaging options early: Negotiate capacity reservations or preferred MPW slots with foundries that support your chosen substrate and process. Concurrently, qualify at least two packaging partners to de‑risk single‑vendor exposure.
- Protect and scout IP thoughtfully: Combine defensive patenting where necessary (e.g., transduction or integration methods) with active scouting of university consortia for emerging multimode and low‑loss techniques.
- Integrate compliance into commercial planning: Build export control and standards compliance into product roadmaps and tender responses to avoid late‑stage market exclusions.
- Use modular commercialization: Where feasible, offer modularized delay units or turnkey modules to accelerate adoption by system integrators while preserving optionality for future integration into custom SoCs.
Next steps — how PW Consulting can help
For leadership teams preparing 2026 investment rounds, product roadmaps, or M&A diligence, PW Consulting offers tailored engagements ranging from rapid market validation sprints to full commercial readiness programs, including access to the interactive market model, vendor scorecards, and our scenario analyses. The full report contains the subsegment revenue tables, competitive shares, and downloadable financial models necessary for board and investor presentations.
To obtain the comprehensive Integrated Optical Delay Line Market report and unlock the granular segmentation, sensitivity analyses, and supplier scorecards referenced in this preview, please visit the PW Consulting reports portal or contact our industry team for a briefing tailored to your strategic context.
Closing observation
Integrated optical delay lines are moving from a technical novelty toward selective commercial utility. The market’s steady mid‑single‑digit CAGR reflects this balance: meaningful growth and opportunity, but with decisive differentiation driven by platform choice, packaging excellence, and compliance-aware commercialization. Organizations that align product strategy, foundry partnerships, and regulatory planning in 2026 will capture preferential positions as the market expands through the early 2030s.
For detailed analysis of this topic, please visit the official page: Integrated Optical Delay Line Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com