

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Autostereoscopic Displays Market to Grow at 17.88% CAGR, Surpassing USD 5.76 Billion by 2032

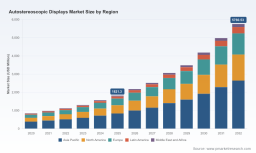
Autostereoscopic Displays Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As enterprises prepare capital allocation and product roadmaps for 2026, autostereoscopic (glasses-free 3D) displays are moving from niche showcase technology toward repeatable commercial deployments across digital signage, medical visualization, automotive cabins and premium consumer devices. PW Consulting’s forthcoming market study — anchored on a 2025 base year and projecting through 2032 — quantifies this shift and translates it into operational guidance. Our topline forecast shows the market expanding from a 2025 base into a multi‑billion dollar opportunity by 2032, driven by a compound annual growth rate of 17.88% across the 2026–2032 forecast horizon. This preview outlines the strategic value the full report delivers to boards, product chiefs, procurement teams and private investors, while intentionally holding back granular segment tables to preserve the exclusive value of the full dataset.
Autostereoscopic Displays Market
Why 2026 Is a Strategic Inflection Point
-
From a demand perspective, maturity in display optics, head- and eye-tracking, and system-on-chip integration is lowering the cost and complexity thresholds for large-format signboards, medical monitors and in-vehicle displays. Commercial pilots are moving into scaled rollouts.
Autostereoscopic Displays Market -
From a supply-side perspective, 2025–2026 is marked by policy and input-cost shocks that materially affect sourcing and margin dynamics. Recent trade and tariff actions targeting electronic components, together with concentrated production of optical films and AMOLED materials in Asia, create acute procurement risk — and procurement teams must act now to secure continuity and pricing leverage.
Autostereoscopic Displays Market -
From a competitive perspective, incumbent display OEMs and a growing set of specialist innovators are deploying differentiated technologies — lenticular optics, parallax barriers, directional backlighting, light-field systems and switchable solutions — producing a bifurcated landscape where system-level integration and application-specific validation determine winners.
What the Full Report Provides — Practical, Decision‑Ready Tools
The full PW Consulting report is built for immediate operational use by commercial leaders and investors. Key deliverables include:
-
Robust market sizing and scenario forecasts (base year 2025; forecast period 2026–2032) with demand drivers mapped to application and technology adoption curves, enabling three-tier scenario planning (conservative, base, accelerated).
-
Technology roadmaps and architecture trade-off models that compare optical approaches (lenticular, parallax, directional backlight) against light-field and switchable displays, with actionable criteria for cost, image fidelity, viewing angle, power consumption and integration complexity.
-
Procurement playbooks: supplier scorecards, total cost of ownership (TCO) calculators, contract clauses addressing tariff and IP risk, and near-term sourcing decision trees tailored to 2026 budget cycles.
-
Go-to-market playbooks for vendors and systems integrators including product positioning by application (advertising & signage, healthcare visualization, in-vehicle UX), pilot-to-scale roadmaps, pricing frameworks and channel strategies.
-
Risk matrices that translate macro-policy shocks and raw material volatility into financial sensitivities, plus mitigation templates for multi-sourcing, buffer inventory and hedging of critical optics components.
-
Investment and M&A scorecards that map IP, manufacturing capacity, customer concentration and margin profiles to acquisition valuation bands and integration risk tiers.
-
Vendor profiles and comparative capability matrices (executive summaries of market players, product strengths, distribution footprints, and go-to-market vectors) to accelerate supplier selection and partnership diligence.
Competitive Landscape — Who Matters, and How
The market structure as of 2025–2026 shows moderate concentration: the top three players account for a meaningful share of revenue, while the top five consolidate a majority position. This concentration dynamic creates both strategic advantages for incumbents and windows of opportunity for fast‑moving specialists.
-
Magnetic 3D (New York) continues to be a visible commercial force in large-format digital signage and enterprise displays. With recent product expansions into all-in-one multiview displays, the firm is prioritizing turnkey solutions for retail and experiential signage where ease-of-deployment matters most.
-
Alioscopy (Paris) remains positioned on the high end of precision lenticular optics, serving professional visualization and specialty display needs where resolution and color fidelity are non-negotiable. Its engineering-led approach and high-resolution offerings match use cases in professional design and industrial visualization.
-
Leia Inc. (USA) pushes the consumer-device angle with switchable light-field stacks and spatial AI tooling. Their platform approach — marrying hardware with spatial content tooling — is a template for consumer OEM partnerships and licensing models.
-
Dimenco (Netherlands), Barco (Belgium) and specialist groups such as 3D Global Solutions and MOPIC are leaning into vertical applications: medical visualization, endoscopic systems and secure professional displays where certified performance and domain-specific features (eye-tracking, low-latency rendering) command premium pricing.
-
Major OEMs (Samsung, LG, Philips) are experimenting with both research-grade autostereoscopic prototypes and commercial signage offerings. Their reach and channel muscle can rapidly scale proven module technology but will require product differentiation to justify above-commodity pricing.
-
New entrants and scale-ups (e.g., Zondision) are notable for integrating eye-tracking with custom ASICs — an indicator that vertical integration at the silicon level is a competitive lever for cost and performance.
Recent industry activity reinforces the above dynamics. Through late 2025 and into mid-2026 we observed multiple product introductions focused on interactive, eye-tracked autostereoscopic monitors and large-format signage demonstrations at major trade events. These launches indicate a move from technical proof-of-concept to customer-validated solutions in specific verticals.
Regulatory, Supply‑Chain and Cost Considerations Shaping Near‑Term Strategy
-
Trade policy risk is no longer hypothetical. In 2025 and early 2026, reciprocal tariffs and targeted duties on Chinese-origin electronics created immediate sourcing pressure for modules and optical films. Some exemptions exist but are temporary and subject to review — creating an imperative to stress-test supplier contracts and design dual-sourcing strategies.
-
Optical films, parallax barriers and AMOLED supply chains remain geographically concentrated. Tariff uncertainty and logistics disruptions can cascade into price increases for module BOMs; procurement teams should model 10–25% input-cost shocks in downside scenarios and prioritize inventory, multi-sourcing and design flexibility.
-
Labor and proximity advantages in Asian production continue to provide measurable cost levers. Our analysis shows that manufacturing bases in Asia often yield lower direct production cost versus Western alternatives — a material factor when evaluating whether to localize production or accept longer supply chains for high‑value systems.
Actionable 90‑Day Roadmap for Executive Teams
To translate insight into action for 2026, PW Consulting recommends this prioritized checklist for commercial and procurement leaders:
-
Complete an exposure audit: quantify component-level sourcing concentration, tariff exposure and single-supplier risks for critical optical components.
-
Initiate high-priority pilots in one vertical where your organization can capture premium pricing (e.g., healthcare visualization or premium signage); structure pilots with milestone-based purchase commitments to derisk scale-up.
-
Deploy TCO and sensitivity modeling from the report to evaluate make-vs-buy decisions, factoring in potential tariff regimes and freight constraints.
-
Open parallel supplier engagement streams: one near-term partner with established capacity and one strategic partner focused on differentiation (optics, ASICs, spatial software).
-
Lock in IP and integration terms early when engaging with module suppliers; define clear acceptance tests for viewing-angle, latency and calibration to avoid costly integration rework.
-
For investors and acquirers: use the report’s M&A scorecards to flag targets with defensible IP, validated customer pilots and scalable manufacturing roadmaps.
Why PW Consulting’s Report Is a 2026 Operational Essential
Our study blends market economics, technology assessment and procurement-grade tools into a single deliverable calibrated to the 2026 decision calendar. The forecast is granular enough to model program economics into multi-year CAPEX cycles yet delivered with templates and playbooks that enable immediate action. While this preview highlights strategic takeaways, the full report contains the detailed, machine-readable datasets, segmentation tables, vendor financials and scenario models that procurement, product and corporate development teams will require to execute confidently in 2026.
PW Consulting intentionally withholds the full segmentation matrices and certain granular split figures in this public summary to preserve the actionable value of the primary dataset. Those locked elements include itemized regional and application-level revenue splits and per-technology SKU economics — the exact inputs that underwrite procurement decisions and investment valuations.
Next Steps
For executive teams preparing budgets, product roadmaps or M&A pipelines for 2026, securing the full PW Consulting Autostereoscopic Displays Market report will provide the data and templates needed to move from strategy to procurement and commercialization. The report’s combination of validated market forecasts (2026–2032), competitive diagnostics, supplier scorecards, regulatory sensitivity analyses and operational playbooks is tailored for rapid adoption.
To access the full dataset and decision tools referenced in this preview, please visit the PW Consulting report page or contact our strategy desk for an executive briefing. The 2026 window for decisive supplier engagement, pilot conversion and portfolio positioning is narrow — market leaders will pair informed scenario planning with near-term operational moves to capture the outsized returns that a 17.88% CAGR market trajectory makes possible.
For detailed analysis of this topic, please visit the official page: Autostereoscopic Displays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com