

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts Coral Calcium Supplements Market to Climb from USD 475.25 Million in 2025 to USD 681.31 Million by 2032, Driven by a 5.28% CAGR
By pmarketresearch, 2026-07-13
Coral Calcium Supplements Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
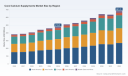
PW Consulting’s latest market research on Coral Calcium Supplements delivers a targeted, decision-ready view for executives preparing strategies in 2026. Our benchmark study synthesizes five years of historical data (2020–2025), establishes 2025 as the base year, and models the sector through a seven-year forecast horizon (2026–2032). At a macro level, the market is entering 2026 with clear momentum: total global revenue is projected to move from approximately USD 475.3 million in 2025 to roughly USD 510.9 million in 2026, reflecting an underlying compound annual growth rate (CAGR) of 5.28% over the forecast period. By 2032 our modeled scenario targets a market size approaching USD 681.3 million.
Coral Calcium Supplyments Market
Why this brief matters for 2026 corporate planning
- Actionable foresight: The study converts granular inputs (supply chains, ingredient sourcing, regulatory precedent, and channel economics) into three pragmatic strategies companies can operationalize during 2026 budget cycles.
- Risk-adjusted growth paths: Beyond headline growth, the report maps downside scenarios tied to regulatory enforcement and raw-material constraints, enabling CFOs to stress-test capital allocations and procurement commitments.
- Competitive positioning playbook: With concentration metrics and company-level intelligence, the brief identifies where new entrants can disrupt and where incumbents must defend margin pools.
Market structure and concentration: what incumbents and challengers should know
Our market concentration analysis shows a moderately consolidated landscape. The top three firms account for roughly 31.5% of market revenue, while the top five capture about 46.8%. This structure creates a duality of opportunity: incumbent brands retain scale advantages in sourcing and retail distribution, but nearly half of the market remains accessible for focused challengers with differentiated formulations, sustainability credentials, or targeted clinical substantiation.
Supply-side realities and raw-material dynamics
Coral calcium’s feedstocks are distinctive: commercially used material is almost exclusively derived from fossilized, above-sea deposits or dead coral washed ashore — not from live reef harvesting. This sourcing pattern is critical for compliance and reputational risk management. The material itself typically includes a blend of calcium (circa 24%), magnesium (circa 12%) and a broad spectrum of trace minerals, which underpins many of the product positioning narratives around bone, dental and digestive health.
Key supply-side considerations for 2026:
- Procurement visibility: Operators must secure multi-year offtake agreements or diversified supplier panels to avoid single-source exposure during peak demand windows.
- Sustainability premiums: Buyers are increasingly willing to pay for certified, traceable coral calcium that demonstrably excludes live-reef extraction — a factor likely to shape commercial terms and margins in B2B channels.
- Processing standards: Pharmaceutical- and nutraceutical-grade processing (cGMP, WHO-GMP) materially affects cost-to-serve and time-to-market; firms lacking compliant facilities face higher regulatory friction and commercial rejection by quality-focused private-label customers.
Regulatory and reputation risk — a prioritization for 2026
Regulatory history in this segment offers both cautionary tales and predictable enforcement vectors. Agencies such as the U.S. Food and Drug Administration have historically targeted unsubstantiated disease claims and the inclusion of non-permitted additives. Earlier actions by the Federal Trade Commission also underscore the long tail of reputation risk when marketing crosses into therapeutic claims. For 2026, firms should treat regulatory and consumer-protection compliance as front-line business priorities:
- Labeling and claims management: Tighten copy and substantiation to align with dietary supplement rules and avoid historical pitfalls tied to medical claims.
- Ingredient scrutiny: Audit formulations for banned or controversial additives; enforcement events tend to cluster around novel or aggressive ingredient positioning.
- Ethical sourcing attestations: Communicate provenance clearly and independently verify that materials come from non-live-reef deposits to mitigate NGO and consumer backlash.
Competitive landscape — who’s shaping the market
The report provides a focused review of the current competitive set — companies that shape raw-material supply, formulation trends, and retail reach. Highlights include:
- Coral LLC (Carson City, Nevada, USA) — Recognized as a leading supplier of fossilized coral calcium and finished supplements; notable for vertically integrated sourcing practices and an emphasis on environmentally friendly operations ( coralcalcium.com ).
- Caltron Clays & Chemicals Pvt. Ltd. (India) — GMP-compliant manufacturer exporting marine-mineral ingredients; recent catalog updates and product promotions in late 2025 and early 2026 signal a push into joint and bone formulation opportunities ( caltronclays.com ).
- West Bengal Chemical Industries Limited (India) — WHO-GMP and ISO-certified producer positioned for pharmaceutical-grade supply chains.
- Trace Minerals, Daily Manufacturing, NOW Foods, GNC and several specialized contract manufacturers — represent a mix of brand, contract-manufacturing, and retail-led capabilities that together shape formulation innovation and go-to-market speed.
Our competitive scoring model evaluates firms on five dimensions: scale of supply, quality certifications, channel access, innovation pipeline, and sustainability credentials. The analysis surfaces white space where niche players can win — for example, clinical-stage bone-health positioning, traceable raw-material branding, and formulation synergies with probiotics or vitamin D in clinically relevant ratios.
Commercial and GTM implications for 2026
Translate market growth into concrete commercial actions:
- Private-label acceleration: Retailers and regional distributors should accelerate private-label plays in segments where scale AND certified sourcing can be demonstrated — capturing margin pools while incumbents focus on branded premiumization.
- Ingredient-to-formulation bundling: Manufacturers investing in end-to-end capabilities (from coral calcium powder to finished capsules/tablets) can compress lead times and extract captive margins — a defensible model in channels with shelf-speed dynamics.
- Channel differentiation: Online-native brands will continue to compete on subscription models and direct-to-consumer clinical storytelling, while brick-and-mortar players will compete on in-store trust signals and third-party certifications.
M&A and partnership opportunities
The market’s mid-level concentration and the capital intensity of compliant processing create clearly defined targets for strategic M&A in 2026:
- Backward integration: Acquiring compliant upstream suppliers or long-term offtake agreements reduces input-price volatility and protects gross margins.
- Scale bolt-ons: Mid-market nutraceutical players can pursue roll-up strategies to consolidate manufacturing expertise, quality credentials, and distributor relationships.
- Joint innovation ventures: Strategic partnerships with contract manufacturers and research labs can accelerate clinical substantiation and open new formulary claims that satisfy regulators.
What PW Consulting’s full report contains (and what we’ve intentionally withheld here)
To support board-level decision-making in 2026, the full PW Consulting Coral Calcium Supplements Market report includes:
- Detailed market-sizing tables and model files (historical and forecast revenue by node)
- Segmented demand analysis across region, form factor and application, with sensitivity scenarios and elasticities
- Supplier maps and a validated list of qualified processors with contactable commercial leads
- Regulatory scenario planning, including remediation roadmaps for formulations at risk of enforcement
- Commercial readiness checklists for private-label versus branded launches
- A prioritized M&A target list and valuation benchmarks
In keeping with the “preview” approach of this release, we have intentionally withheld detailed segment-level figures and proprietary scenario outputs from this public summary. These withheld datasets are included in the full report and accompanying model workbook available through PW Consulting. This approach preserves the competitive value of our analytics while demonstrating the practical utility of our findings.
Practical next steps for executives in 2026
- Immediate (0–3 months): Conduct an ingredient-origin audit and legal review of claims language; suspend any marketing that strays into therapeutic claims.
- Short-term (3–9 months): Secure diversified supplier agreements with documented provenance and invest in quality certification if absent.
- Medium-term (9–18 months): Pilot differentiated SKUs (e.g., traceable-sourced, clinically substantiated blends) in direct channels and test private-label partnerships for margin optimization.
Closing perspective
Coral calcium supplements stand at an inflection point in 2026: steady baseline growth is supported by rising consumer interest in bone and dental health, but the sector is simultaneously exposed to regulatory scrutiny and supply provenance pressures. Companies that treat compliance, traceability, and clinical credibility as strategic assets — and that align procurement with long-term price and reputation management — will capture disproportionate upside as the market grows toward our 2032 forecast horizon.
For boards, corporate development teams, and category leaders preparing 2026 roadmaps, PW Consulting’s full report provides the granular inputs, scenario models, and executable playbooks necessary to convert market opportunity into defensible value. To access the complete dataset, model workbook, and targeted strategic recommendations, visit the PW Consulting Coral Calcium Supplements Market report page or contact our industry practice.
For detailed analysis of this topic, please visit the official page: Coral Calcium Supplyments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Rack-and-Pinion Construction Elevator Market to Expand at a 7.0% CAGR, New Insight Report Shows
By pmarketresearch, 2026-07-13
Rack and Pinion Construction Elevator Market: Strategic Imperatives for 2026 Decision‑Makers
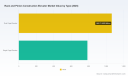
As built environments become taller, more complex and time‑sensitive, rack and pinion construction elevators have moved from niche utility to a strategic asset on active sites and in long‑life industrial facilities. PW Consulting’s latest market study shows the global rack and pinion construction elevator market reached USD 1,852.08 Million in 2025 and is projected to expand at a 7.0% compound annual growth rate through the 2026–2032 forecast window, reaching approximately USD 2,974.03 Million by 2032. This briefing teases the practical, decision‑focused intelligence contained in the full report and highlights the near‑term choices corporate leaders must get right in 2026.
Rack And Pinion Construction Elevator Market
Why this report matters for 2026 strategy
-
Timing and capital allocation: With a steady mid‑single digit CAGR, procurement and replacement cycles for hoists should be integrated into 3– to 7‑year CapEx plans rather than treated as ad‑hoc site purchases.
Rack And Pinion Construction Elevator Market -
Cost‑and‑risk management: Recent raw material inflation and regulatory pressure mean organizations must quantify steel exposure, maintenance frequency and compliance costs before committing to fleet expansion or long‑term leases.
Rack And Pinion Construction Elevator Market -
Competitive positioning: Suppliers and fleet operators are diversifying service portfolios—construction teams and industrial operators must choose between turnkey rental, hybrid service contracts and outright ownership based on lifecycle TCO and operational tempo.
What the report delivers — actionable modules
-
Robust market sizing and scenario forecasts that map demand corridors under several macroeconomic and steel‑price scenarios, enabling finance teams to stress‑test budgets against upside and downside demand paths.
-
Practical procurement playbooks that translate industry standards (OSHA, ANSI/ASME drafts) into tender language, warranty clauses and acceptance tests suited to construction vs industrial shutdown use cases.
-
Fleet optimization tools that compare CapEx ownership, long‑term rental, and managed‑service models using plug‑and‑play financial tables and sensitivity drivers (utilization, downtime cost per hour, mobilization expense).
-
Maintenance and safety matrices specifying periodic testing cadence, spare‑parts inventories, and service‑level KPIs aligned with manufacturer recommendations and common practice for safety devices.
-
Deal screening criteria for M&A and J/V opportunities, including integration checklists and quick valuation heuristics tailored to manufacturers, service providers and fleet operators.
-
Customizable presentation templates and executive one‑pagers for stakeholder buy‑in, permitting and capital committees.
Market dynamics shaping near‑term decisions
Three dynamics are converging on procurement and operations teams in 2026.
-
Raw material volatility. Steel price trajectories have shifted structurally: US hot rolled coil prices moved materially higher between early 2025 and early 2026, and benchmark Chinese steel prices showed incremental increases year‑over‑year into spring 2026. For asset‑heavy equipment such as rack and pinion systems, even modest raw material cost moves can change OEM pricing and spare‑parts economics rapidly. Scenario analysis in the report quantifies breakpoints at which ownership becomes uneconomic versus rental.
-
Regulatory tightening and evolving standards. OSHA rule sets remain the baseline for temporary hoists and material handling on US sites; proposed revisions to the ASME A17.1 code introduce more prescriptive language on equipment locations and periodic testing standards for rack‑and‑pinion systems. Operators must budget for increased inspection frequency and possible retrofits to meet updated definitions and testing requirements.
-
Lifecycle maintenance and safety practice. Industry practice and several OEM manuals recommend semi‑annual testing of safety devices, and component replacement cycles commonly fall in the 3–4 year window for high‑use fleets. These practices directly affect scheduled downtime and spare parts planning; on‑site safety testing influences contractor selection and site sequencing.
Competitive landscape: what to watch in 2026
The market displays a moderate level of concentration: the top three suppliers account for roughly 31.5% of supply capacity, while the top five approach just under half of the market. That structure creates meaningful opportunities for regional specialists and value‑added service providers while preserving scale advantages for global OEMs.
-
Global OEMs with integrated product lines and standards compliance (e.g., Alimak Group AB and associated brands) continue to leverage scale for large, high‑capacity permanent and temporary installations, emphasizing compliance with international standards and high‑capacity personnel/material transport solutions.
-
Specialist European manufacturers (e.g., GEDA, Maspero) offer engineered solutions for industrial and power‑sector projects where custom structural integration and certified compliance are premium purchase drivers.
-
North American players (examples include USA Hoist / Mid‑American and fleet operators like McDonough) bring deep local service networks, rapid mobilization and fleet management experience—attributes that often trump lowest initial price when schedule risk is high.
-
Regional suppliers and assemblers (notably from Asia) are increasing product cadence and feature sets, from CE‑certified designs to higher payload models. Recent model introductions and industry articles through 2025–2026 reflect a steady stream of product refreshes and marketing that will influence procurement cycles.
Recent industry activity underlines these trends: fleet operators and service providers are publishing use‑case analyses emphasizing downtime reduction during industrial shutdowns, while several OEMs announced new model releases in early 2026 targeted at improved payload efficiency and modularity. Taken together, these moves signal a market balancing product innovation with service‑led differentiation.
Strategic playbook for 2026 executives
-
Quantify steel exposure in procurement models. Build sensitivity bands (±10–25% steel cost) into OEM quotations and assess the impact on life‑cycle pricing; negotiate material price pass‑through clauses or multi‑year fixed‑price tranches where appropriate.
-
Adopt a portfolio approach to fleet ownership. Use utilization thresholds to determine whether to buy, rent, or enter managed‑service agreements; run a break‑even analysis that includes mobilization, certification, and scheduled safety testing costs.
-
Standardize technical and contractual specifications across sites. Draft tender documents that enforce minimum safety device testing frequency, spare parts provisioning and KPIs for mean time to repair (MTTR) and availability.
-
Invest in predictive maintenance and telematics. For high‑use assets, telematics reduces unscheduled downtime and optimizes spare parts inventories—capture the ROI within 18–36 months in typical high‑utilization scenarios.
-
Pursue selective partnerships rather than full ownership for new geographies. Collaborate with regional fleet operators for mobilization and local compliance while preserving OEM relationships for technical support and warranty continuity.
-
Prepare for tightening standards. Budget for periodic testing and potential retrofits tied to evolving ASME/ANSI/OSHA guidance; ensure procurement timelines allow for certification and acceptance testing prior to mobilization.
How PW Consulting accelerates your 2026 decision cycle
Our full report goes beyond high‑level forecasts to deliver implementation tools that procurement, operations and corporate development teams can use immediately. Clients receive: detailed scenario models, procurement templates, maintenance and testing matrices, a supplier short‑list methodology tailored to risk appetite, and an acquisition screening pack for targets within manufacturing and fleet services.
If your 2026 agenda includes fleet expansion, rental strategy optimization, or an acquisition in the rack and pinion space, PW Consulting can fast‑track the analytical groundwork and stakeholder materials required for board‑level approval. The published market forecast (including the headline USD 1,852.08 Million market size for 2025 and the 7.0% CAGR through 2032) is only the starting point; the full intelligence package contains the segment‑level and regional breakouts, supplier scorecards and financial models that translate those macro numbers into executable decisions.
Next step
This briefing is a preview of the operational playbook and competitive detail contained in our market research. To access the full dataset, segmented models and supplier scorecards that underpin these recommendations, please consult the PW Consulting report landing page or contact your engagement lead for a secured executive summary and a hosted walk‑through of the decision‑support tools. In a market moving at the rhythm of steel prices, safety standards and project scheduling, having the right data and playbook is the difference between reactive procurement and strategic advantage in 2026.
For detailed analysis of this topic, please visit the official page: Rack And Pinion Construction Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Business Management Consulting Market Reaches USD 1,071.18 Billion in 2025, Poised for a 5.22% CAGR Through 2026–2032
By pmarketresearch, 2026-07-13
PW Consulting Releases Strategic Market Intelligence: Business Management Consulting Services — A 2026 Decision-Maker’s Playbook
Today PW Consulting publishes its flagship Business Management Consulting Service Market report — a practical, strategy-grade briefing designed to inform executive decisions in 2026 and beyond. Built from an original dataset spanning 2020–2025 and a forward-looking forecast to 2032, the study translates macro momentum, competitive dynamics, regulatory inflection points, and operational realities into a concise set of actions that CEOs, CHROs, CFOs, and consulting leaders can operationalize immediately.
Business Management Consulting Service Market
Why this report matters for 2026 strategy
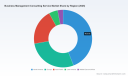
The global business management consulting market is no longer a steady utility; it is a battleground of talent, technology, and trust. After expanding from roughly USD 785 billion in 2020 to about USD 1.07 trillion in 2025, the market continues to show resilience. Our base-case modeling projects a compound annual growth rate (CAGR) of around 5.22% over the 2026–2032 forecast period, with total industry revenue moving past the USD 1.1 trillion threshold in 2026 and approaching the mid-trillion mark by 2032.
Business Management Consulting Service Market
For executives making resource-allocation choices this year, that macro trajectory matters for three decisions in particular: how much to budget for external advisory, which capabilities to buy versus build, and how to structure partnerships with consulting firms that are themselves scaling AI and subscription-enabled offerings.
Business Management Consulting Service Market
What leaders will find inside (practical, actionable content)
- Executive playbooks: concise decision trees for buy/build/partner choices across strategy, operations, finance, HR and technology management.
- Vendor evaluation templates: standardized scorecards and negotiation levers tailored to outcomes-based and subscription pricing models.
- AI adoption roadmaps: phased, compliance-aware sequencing that aligns use cases to risk profiles and expected ROI.
- Commercial models: benchmarked pricing corridors and fee-structure scenarios to inform procurement and in-house capability investments.
- Talent & operating models: talent-sourcing strategies, near- and onshore staffing mixes, and retention levers informed by current wage pressures in strategy, digital and AI domains.
- Regulatory and data hygiene checklists: pre-built controls and contractual clauses responding to recent privacy, cybersecurity and bulk-data rules.
- Scenario tools: three stress-tested market scenarios (conservative, base, accelerated) with trigger indicators and course-correction playbooks for each.
Each toolkit item is accompanied by pragmatic templates and a “ready-to-deploy” checklist so that leadership teams can move from diagnosis to action within weeks, not months.
Market dynamics shaping 2026 decisions
- Technology acceleration and new commercial models : Leading firms are embedding AI and platform economics into offerings and experimenting with subscription and outcome-linked pricing. These shifts change how clients should structure scope, governance and contracting when buying advisory services.
- Talent and cost inflation : Competition for senior strategists and AI-savvy operators is driving persistent wage pressure. Clients should expect higher blended day-rates for premium expertise and should evaluate alternative resourcing strategies—e.g., small elite pods supplemented by scaled delivery centers.
- Regulation and data governance : A more complex regulatory environment — including multiple state privacy regimes, updated financial services cybersecurity requirements, and stricter rules on bulk data handling — creates both risk and opportunity. Firms that can demonstrate robust compliance by design will command price premiums.
- Moderate consolidation of capability, not geography : While the market remains broadly fragmented, the leading global firms continue to capture disproportionate demand for high-value mandates. Top-tier consultancies control a meaningful share of enterprise engagements, creating a two-tier market for premium transformational work versus scalable implementation services.
Competitive landscape: who’s shaping strategy and product innovation
The report includes a focused competitive analysis of incumbent leaders and fast-scaling integrators. It synthesizes public filings, client surveys, and primary interviews to surface where firms are investing and how that affects client choices in 2026.
- McKinsey & Company: continues to anchor large-scale strategic transformations for global clients, combining traditional strategy capabilities with expanding digital and analytics delivery footprints.
- Boston Consulting Group (BCG): has doubled down on capabilities that integrate AI, innovation pipelines and sustainability, reinforcing its position in complex, cross-functional engagements.
- Bain & Company: emphasizes results-driven programs and private equity advisory, focusing on measurable business outcomes and post-deal value capture.
- Deloitte Consulting, PwC, EY and KPMG (Big Four): compete across breadth — from strategy through execution — and are increasingly bringing bundled tax, risk and technology propositions to enterprise clients.
- Accenture and IBM Consulting: lead in integrated technology and operations transformations, leveraging cloud, AI and hybrid delivery models to scale implementations.
- Oliver Wyman and specialist boutiques: retain leadership in sector-specific risk and performance work, particularly in regulated industries.
Recent industry signals illustrate these dynamics: leading publications’ 2026 rankings emphasize the continued prominence of both MBB and top professional services firms, while product launches from major players reflect a pivot to AI-enabled, platform approaches and subscription pricing. In parallel, large consultancies’ financials show robust bookings and revenue growth—evidence of sustained enterprise demand.
Strategic imperatives for buyers in 2026
- Shift from “project-first” to “capability-first” contracting: specify capability transfer milestones in SOWs and tie fees to measurable KPIs.
- Prioritize compliance-aware AI pilots: run limited-scope pilots that stress test privacy, cybersecurity and auditability before scaling.
- Adopt blended delivery models: combine boutique strategy pods with scaled implementation partners to balance innovation and cost control.
- Negotiate price-performance: use our vendor scorecard to compare outcome-based versus input-based pricing and secure favorable governance terms.
- Invest in internal “broker” capability: appoint an internal client owner with the authority to integrate consultancy outputs into enterprise execution plans.
Strategic imperatives for consulting firms in 2026
- Productize repeatable outcomes: convert methodologies into subscription-capable modules with clear ROI metrics.
- Demonstrate compliance & provenance: publish transparent data lineage, model validation and security certifications to win regulated clients.
- Optimize talent economics: invest in upskilling and a two-tier staffing model that preserves access to senior talent while scaling delivery cost-effectively.
- Partner to win scale: form alliances with cloud, data and specialist technology vendors to offer end-to-end transformation journeys.
Methodology and what we intentionally withheld
PW Consulting’s analysis combines a bottom-up market-sizing approach with firm-level revenue triangulation, hundreds of primary client and supplier interviews, and scenario-based financial modeling. We used a multi-layer taxonomy across service types, industry verticals and delivery models to produce a granular picture of market economics.
In keeping with our “trailer” principle, this release highlights the high-value macro conclusions and executable frameworks that executives need today. To preserve the strategic value of the report for subscribers, we have intentionally withheld detailed segmentation tables and proprietary client-level market shares from this public summary. The full report contains detailed breakouts, downloadable datasets, and interactive dashboards for subscribers and licensed clients.
How to use this report for 2026 planning
Use the report as a one-stop reference to:
- Set consulting budgets aligned to scenario-triggered spending corridors;
- Design procurement processes that favor outcome-linked engagements and manage long-term vendor risk;
- Benchmark internal capability investments against market supply costs and expected time-to-value;
- Design compliance-first rollout plans for AI-driven initiatives to avoid regulatory and reputational setbacks.
Access and next steps
Senior executives and consulting partners interested in commissioning custom briefings, licensing the underlying dataset, or getting our interactive dashboards should visit the PW Consulting report page. The full report includes client-ready slide decks, an editable financial model, and the raw, subscriber-only market tables that underpin our forecasts.
PW Consulting’s Business Management Consulting Service Market report is designed to be a pragmatic navigational aid for 2026: it reveals the lines of force shaping the industry and supplies the playbooks organizations need to convert advisory spend into measurable and regulated outcomes. For teams preparing budgets, negotiating vendor contracts, or designing enterprise AI programs, this is the operational intelligence that shortens decision cycles and reduces execution risk.
To download the full report, license datasets, or schedule a briefing with our lead analysts, please visit our official report page and contact the PW Consulting insights team.
For detailed analysis of this topic, please visit the official page: Business Management Consulting Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Desktop Virtualization Software Market to Surge from USD 19,450.6 Million in 2025 to USD 44,029.5 Million by 2032 at a 12.38% CAGR
By pmarketresearch, 2026-07-13
Desktop Virtualization Software Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
Executive summary
The desktop virtualization software market is entering a decisive phase where technology maturation, regulatory pressure, and changing consumption models converge to reshape enterprise IT strategy. Our latest PW Consulting market study — anchored on a 2025 base year and projecting through 2032 — shows the market roughly doubling in size over the last five years and continuing strong, with a compounded annual growth rate of 12.38% across the forecast horizon. By 2025 the market had reached just under USD 19.5 billion (revenue basis, millions USD unit), and our scenario analysis points to an exit market of approximately USD 44.0 billion by 2032 under the base forecast. At the same time, concentration metrics indicate the top vendors control a substantial majority of revenue, underscoring a competitive environment that combines dominant cloud platforms with specialized niche providers.
Desktop Virtualization Software Market
Why this report matters for 2026 decision cycles
For CIOs, CTOs, and procurement leaders finalizing budgets and strategic roadmaps in 2026, the decision to refresh desktop virtualization strategies is no longer tactical — it’s transformational. This report translates macro momentum into actionable intelligence: when to accelerate cloud-first migrations, how to structure hybrid operating models, what cost levers to expect from security and compliance, and how vendor licensing shifts can alter multi‑year TCO. We deliberately present deep, practitioner‑oriented guidance while reserving the full granular segment dataset for subscribers — a design choice that balances public strategic signaling with the confidentiality enterprise buyers require.
Desktop Virtualization Software Market
What’s in the report (practical, operational content)
- Market sizing and forecast methodology, including scenario and sensitivity analyses covering 2026–2032.
- Demand-side drivers and buyer personas mapped to real procurement cycles, with workload classification templates to prioritize migration candidates.
- Deployment decision framework (cloud vs. on‑premises vs. hybrid) with a step‑by‑step playbook for pilots and scale‑up phases.
- Full vendor scorecards and comparative capability matrices covering product architecture, management tooling, security controls, and channel models.
- TCO and ROI models with editable inputs for hardware, licensing, workforce, and operational security add‑ons; a practitioner’s guide to capture hidden costs.
- Compliance and data‑sovereignty checklists aligned to major regimes (GDPR, HIPAA, PCI‑DSS) and guidance on mitigating legal exposure linked to extraterritorial laws.
- Procurement negotiation templates and SLA clauses tuned for cloud desktop engagements and managed service contracts.
- Case studies and migration templates from multi‑industry implementations, plus a risk register for common failure modes.
Note: To preserve the value of the research as a decision‑ready asset, public summaries omit the full segmentation tables. The report contains comprehensive breakouts by region, deployment mode, and desktop type — available through the report portal.
Desktop Virtualization Software Market
Key market dynamics shaping vendor and buyer behavior
- Cloud acceleration vs. hybrid realism: Enterprises are accelerating cloud desktop adoption for scale and management simplicity, yet hybrid deployments remain the pragmatic choice for regulated workloads and latency‑sensitive use cases. Our forecasting reflects persistent demand for both approaches.
- Licensing and activation risk: Vendor moves to cloud‑centric licensing models and mandatory activation services create migration windows that require active vendor engagement and careful cutover planning to avoid service disruption.
- Security and operational cost trade‑offs: Zero Trust enforcement, device compliance checks, and advanced monitoring materially increase operational spend. These are often licensed or delivered as premium modules and must be included in three‑ to five‑year TCO scenarios.
- Regulatory and sovereignty pressures: Data residency concerns and extraterritorial legislation are reshaping provider selection, pushing some buyers toward localized deployments or regionally certified partners.
Competitive landscape — who matters and what to watch
The vendor landscape is a hybrid of hyperscaler cloud platforms, legacy virtualization specialists, and agile niche players. The market’s structure favors integrated cloud ecosystems while leaving room for differentiation around management simplicity, application performance, and enterprise security posture. Key players profiled in the report include:
- Microsoft Corporation — Strong momentum around Azure Virtual Desktop and Windows 365, with deep integration into Microsoft 365 and hybrid options that appeal to organizations standardizing on Microsoft stacks. Recent platform updates have extended application‑attach and session host support, underscoring continued investment in scale and manageability.
- Amazon Web Services (AWS) — Amazon WorkSpaces continues to broaden regional availability and platform capabilities, including recent support for next‑generation Windows server releases and TPM‑enhanced security bundles. AWS’s flexible pricing and global footprint make it a credible choice for cross‑region enterprises.
- Citrix Systems, Inc. — Citrix remains a go‑to for high‑performance remote access and secure application delivery, but recent mandates around cloud‑based licensing activation require customers to plan migrations carefully to maintain continuity.
- Omnissa (formerly VMware) — Enterprise VDI solutions with strong hybrid/on‑prem integration appeal to organizations prioritizing in‑house control and advanced virtual desktop management.
- Nutanix, Parallels, Inuvika, and Oracle — These vendors provide differentiated choices: Nutanix with hybrid integration plays, Parallels for SMB simplicity, Inuvika as a cost‑effective open alternative for Linux workloads, and Oracle for customers seeking tight coupling with enterprise database and cloud services.
Our market concentration analysis shows the largest vendors account for a dominant share of market revenue, creating both strategic dependencies and competitive opportunities for specialized providers. For buyers, this means negotiating power exists but requires a disciplined approach to vendor comparison beyond sticker pricing.
Recent vendor developments to monitor
- AWS expanded WorkSpaces regional availability and enhanced platform support for recent Windows Server releases (notable updates in Q1–Q2 2026).
- Microsoft enhanced application‑attach capabilities to support newer session host versions, improving lifecycle flexibility for application management.
- Nutanix announced public‑preview integrations for hybrid Azure Virtual Desktop scenarios on its AHV hypervisor — a notable signal of increased interoperability between hyperconverged infrastructure vendors and hyperscalers.
- Citrix’s migration to a cloud License Activation Service introduced a hard timeline that has implications for licensing continuity and migration project sequencing.
Risks and compliance considerations
Implementations face a confluence of legal, operational, and technical risks. From a compliance perspective, VDI deployments used in regulated industries must demonstrate workload isolation, encryption, and auditability consistent with HIPAA, PCI‑DSS, and GDPR obligations. Data sovereignty and the potential applicability of extraterritorial laws (for example, the US CLOUD Act) can constrain public cloud choices and necessitate hybrid or localized architectures. Operationally, the incremental workforce and tooling needed to enforce Zero Trust and continuous monitoring are frequently underestimated; our field work shows these items are common drivers of unexpected cost overruns.
Practical next steps for 2026 buyers
- Initiate an application workload mapping exercise this quarter to classify candidates for persistent vs. non‑persistent delivery and to prioritize migration batches.
- Run vendor‑neutral TCO scenarios that include security add‑ons, licensing activation conditions, and regional compliance costs over a five‑year horizon.
- Engage early with incumbent vendors where mandatory license activation or migration windows exist to avoid service interruptions and secure transition discounts.
- Pilot hybrid reference architectures for regulated workloads, validating latency, user experience, and data residency controls before wide rollout.
- Update procurement templates to include SLA points for license portability, data residency guarantees, and clear exit provisions.
How PW Consulting can help
PW Consulting’s Desktop Virtualization Software Market Report is designed to be a working resource for practitioners: not a passive briefing, but a playbook. Subscribers receive the full dataset (detailed segmentation breakouts, vendor scorecards, and editable financial models) alongside advisory hours for customized scenario modeling and implementation planning. For teams gearing up for procurement cycles and board‑level approvals in 2026, our analysts can accelerate vendor evaluations, quantify migration costs, and build defensible roadmaps aligned to your risk tolerance and regulatory footprint.
To access the full intelligence — including the complete regional, deployment‑mode, and desktop‑type breakouts that inform the TCO and segment forecasts — please visit the PW Consulting report landing page for purchase and subscription options. The public summary above highlights the strategic contours; the full report equips your team to make the specific, defensible decisions required this year.
For detailed analysis of this topic, please visit the official page: Desktop Virtualization Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fully Rugged Tablets Market to Expand from USD 1,280.5 Million in 2025 to USD 2,103.8 Million by 2032, Posting a 7.35% CAGR
By pmarketresearch, 2026-07-13
Fully Rugged Tablets Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive summary
The fully rugged tablets market is entering a phase of steady, structurally supported expansion that will matter to procurement leaders, product strategists, and M&A teams in 2026. Our new report, with base year 2025 and a forecast covering 2026–2032, documents a market that has grown from roughly USD 905 million in 2020 to USD 1.28 billion in 2025 and is projected to expand further—reaching roughly USD 1.42 billion in 2026 and continuing to rise to an estimated USD 2.1 billion by 2032 under a compounded annual growth rate (CAGR) of 7.35% across the forecast period.
Fully Rugged Tablets Market
These headline trends are driven by the convergence of digital transformation in mission-critical sectors (defense, public safety, utilities, field services, and logistics), an elevated emphasis on device-level security and certification, and technology inflections including advanced processors, 5G connectivity, and ruggedized battery systems. At the same time, the industry must navigate meaningful supply-side and regulatory headwinds—longer lead times for high-performance processors, rising component costs for hardened display materials, and new certification/regulatory regimes—that materially affect sourcing and go-to-market timing.
Fully Rugged Tablets Market
Why this matters for 2026 decision cycles
- Capital planning and procurement: The combination of steady market growth and persistent component lead times means procurement calendars and inventory strategies developed in late 2025 will directly influence fleet availability in 2026. Organizations that lock strategic partnerships and flexible sourcing windows now will secure first-mover advantage.
- Product selection and compliance: Updates to ruggedization standards and increased demand for certified secure platforms mean that certification timelines (testing and validation) must be incorporated into RFP schedules—especially for government and defense deployments.
- Service and lifecycle economics: As fleet sizes increase, service revenue and total cost of ownership considerations (including battery replacement cycles and rugged display replacement) become decisive in vendor selection and long-term budgeting.
Report contents — practical, operational, and decision-ready
The PW Consulting report combines macro outlooks with granular, actionable modules designed for teams that must act in 2026. Key deliverables include:
Fully Rugged Tablets Market
- Market sizing and forward-looking scenarios: base-case, upside, and downside paths calibrated to supply constraints and regulatory shocks.
- Procurement playbooks and contract templates: practical clauses for lead-time hedging, spares provisioning, and firmware/security update SLAs.
- Vendor evaluation frameworks: a scorecard for capability, certification readiness, aftermarket support, and component diversification.
- Use-case ROI models: pre-built TCO calculators demonstrating lifecycle costs across mission profiles (defense patrols, field maintenance, warehousing operations).
- Risk heatmaps: supplier concentration, geopolitics, and raw-material cost pressure translated into procurement risk factors.
- M&A and partnership shortlists: profiles of strategic targets and partnership candidates with rationale and integration considerations.
- Executive dashboards and downloadable financial models: configurable tools for quickly stress-testing assumptions against supplier lead times and pricing shocks.
These deliverables are intentionally operational — they enable procurement, engineering, and finance teams to convert market intelligence into executable 2026 plans rather than offering only high-level commentary.
Competitive landscape — who matters and why
The fully rugged tablet market displays a concentrated structure at the top of the supplier pyramid, creating a competitive dynamic that favors scale, certification breadth, and integrated services. Our concentration analysis shows that the top three suppliers account for a meaningful majority of market share and the top five extend that dominance—creating both barriers and consolidation opportunities for smaller players and partners.
Against that backdrop, the following vendor archetypes emerge as focal points for 2026 strategy:
- Getac (Taiwan) — Product-led innovator. With recent product introductions emphasizing high-performance Intel Core Ultra processors, larger displays, and stronger ingress protection ratings, Getac is clearly targeting defense and industrial segments that prioritize rugged performance and long-term support. Their product cadence signals a continued emphasis on certified, field-hardened platforms.
- Panasonic (Japan) — Platform & vertical integrator. The Toughbook line continues to be positioned for public safety and logistics, with recent updates incorporating 5G and extended battery life. Panasonic’s strength lies in end-to-end solutions and long-standing OEM relationships in regulated sectors.
- Dell (USA) — Security and enterprise play. Dell’s Latitude Rugged family, augmented by recent certifications for secure government deployments, positions the company as a preferred partner for organizations prioritizing compliance and lifecycle management at scale.
- HP (USA) — Enterprise mobility with lifecycle focus. HP’s recent rugged offerings emphasize enterprise manageability and field-serviceable architecture, attractive for customers needing tight IT integration.
- Zebra / Xplore Technologies (USA) — Sector specialists. Optimized solutions for energy, oil & gas, and utilities demonstrate the value of domain-specific hardware features and certifications.
- DT Research and MobileDemand (USA) — Niche and feature-specialized providers. These firms compete on modularity (hot-swappable batteries), scanning and I/O specialization, and fast customization cycles for first responders and warehousing.
Recent vendor developments — new product launches, 5G-enabled refreshes, and additional security certifications — underscore two market realities: product differentiation is increasingly about certified, mission-ready feature sets rather than basic rugged claims; and time-to-availability will be a gating factor as long as component lead times remain elevated.
Market dynamics and operational constraints
Three cross-cutting dynamics will shape 2026 outcomes:
- Component supply friction: Lead times for premium mobile processors have extended substantially in recent quarters. This increases the value of long-term supply agreements, strategic inventory, and design flexibility to tolerate alternative chip families.
- Certification and standards evolution: An updated MIL-STD-810H (2024 enhancements) tightens thermal and vibration testing criteria. Buyers must demand proof points and updated test documentation during procurement to avoid retrofit costs.
- Geopolitical and regulatory risk: Export controls on high-end semiconductors influence where and how device manufacturers source components and assemble products for markets with restricted access. Regional sourcing strategies and compliance workflows must be integrated into vendor due diligence.
Strategic moves for 2026 — recommended playbook
Based on our scenario modeling and supplier intelligence, enterprises should consider a multi-layered strategy going into 2026:
- Secure supply through diversity: Combine framework agreements with primary suppliers and spot contracts with tier-two manufacturers to protect programs against long processor lead times.
- Anchor on certification as a purchase criterion: Require current certifications (and supporting test reports) in RFPs and include re-test obligations for mid-life upgrades.
- Design for maintainability and modularity: Prioritize platforms with hot-swappable batteries and modular I/O to reduce downtime and spare-parts SKUs.
- Push service-centric procurement: Negotiate bundled managed services (secure updates, depot repair, asset tracking) to lower TCO and enable predictable budget flows.
- Stress-test supplier risk: Use scenario modeling to quantify the impact of component delays and component-cost inflation on program economics and delivery timelines.
- Consider localized assembly or alternative BOMs to navigate export-control friction and shorten logistics legs for critical deployments.
Scenario planning and financial impact
The report’s scenario suite quantifies how small percentage points of market share movement can translate into meaningful revenue changes in a market that is expanding at a mid-single-digit CAGR. More importantly for enterprises, the models show how procurement timing and supplier selection materially influence fleet readiness and total lifecycle cost. We provide downloadable, configurable models that let buyers and channel partners test sensitivity to processor lead times, display-material cost inflation, and certification timelines.
Conclusion — what PW Consulting offers for 2026
For teams making device, supplier, and capital-allocation decisions in 2026, the Fully Rugged Tablets Market report is engineered to be both a strategic compass and a tactical toolkit. It pairs an empirical market outlook (2020–2032) with procurement-ready instruments: contract language, vendor scorecards, risk matrices, and ROI calculators. Our competitive analysis highlights which suppliers are positioned to capture incremental demand and where opportunity exists for nimble challengers and channel partners.
We intentionally keep certain granular split tables and proprietary vendor scoring matrices in the full report to preserve the value of the source research and to enable direct consultation. If your 2026 plans depend on rugged device availability, compliance, or fleet economics, PW Consulting’s report and advisory packages provide the specific levers and scenario-tested recommendations needed to translate market trends into executable results.
To access the full research, database downloads, and customizable models that support the findings summarized here, please visit the official PW Consulting report page or contact our advisory desk for a briefing tailored to your organization’s use cases and timing constraints.
For detailed analysis of this topic, please visit the official page: Fully Rugged Tablets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrolyzed Formula Milk Powder Market Poised to Expand at an 8.8% CAGR Through 2032
By pmarketresearch, 2026-07-13
Hydrolyzed Formula Milk Powder: Strategic Imperatives for 2026 — PW Consulting’s Market Brief
PW Consulting’s new market study on Hydrolyzed Formula Milk Powder positions industry leaders, investors and policy teams to make decisive, risk-calibrated moves in 2026. Built on a consistent historical baseline (2020–2025, base year 2025) and a forward-looking forecast window (2026–2032), the research reconciles granular commercial realities with regulatory inflection points. Key topline context: the global market expanded from roughly USD 4.75 billion in 2020 to about USD 6.98 billion in 2025, and our base-case projection indicates continued expansion at a compound annual growth rate (CAGR) of 8.8%, reaching approximately USD 12.6 billion by 2032.
Hydrolyzed Formula Milk Powder Market
Why 2026 Is a Strategic Pivot
Two systemic shifts elevate 2026 from a routine planning year to a strategic inflection point. First, regulatory adjustments in major jurisdictions are changing formulation boundaries, labeling language and permissible ingredient sets — effectively redefining product development and compliance cost curves. Second, demand-side dynamics (clinical guidance, physician prescribing practices, and caregiver preferences) are converging with supply-side realities (raw material availability, ingredient concentration, and private-label competition), producing differentiated opportunity windows for incumbents and entrants alike.
Hydrolyzed Formula Milk Powder Market
- Regulatory realignment: The European Commission’s December 2025 amendment to Delegated Regulation (EU) 2016/127 — which introduces a new category for protein hydrolysates and expands permitted protein sources effective January 2026 — compels product reformulation and relabeling programs across the region.
- Market momentum: Our dataset shows a resilient post‑pandemic recovery and a sustained structural trajectory supporting near‑double‑digit CAGR over the forecast window, driven by clinical indications, rising diagnostic rates of cow’s milk protein allergy (CMA) in particular markets, and evolving caregiver willingness to pay for hypoallergenic claims.
What the Report Delivers — Practical, Decision-Ready Tools
This report is built for executives who need more than descriptive market histograms. It combines proprietary market-sizing with application-level scenario modeling and executable playbooks. Core deliverables include:
Hydrolyzed Formula Milk Powder Market
- Executive dashboard with macro-to-micro linkage: top-line market growth, scenario-adjusted revenue curves, and sensitivity to price and raw-material shocks.
- Regulatory impact matrix: jurisdiction-by-jurisdiction requirements, compliance timelines and formulation change impact estimates to Q1 2027.
- Product and portfolio playbooks: roadmaps for transitioning existing SKUs, launch sequencing, positioning language and claim architecture under new EU and US constraints.
- Supply‑chain and sourcing scorecards: risk-weighted supplier maps, cost-to-secure models for hydrolyzed whey versus alternatives, and levers to de-risk supply concentration.
- Commercial execution kits: channel prioritization frameworks, e‑commerce acceleration templates and private‑label competitive responses.
- M&A and partnership screeners: value-creation checklists for bolt-ons, ingredient-supplier partnerships and co-development deals.
To preserve the utility of this brief as a strategic “trailer,” we present aggregated market trajectories and actionable guidance here while withholding detailed product / regional / channel splits. The full report and interactive model on our site contain the granular segment tables and dashboards necessary for transaction diligence and country-level go-to-market plans.
Competitive Landscape — Strategic Profiles and Implications
The hydrolyzed formula market remains concentrated: the top three players account for roughly 68% of the market, and the top five approach about 79% — an industry structure that favors scale in R&D, regulatory affairs and distribution. Competitive dynamics are shaped by three interlocking cohorts: multinational brand owners, ingredient suppliers, and private-label / contract-manufacturers.
- Nestlé (Vevey, Switzerland) : High R&D intensity and an extensive global go‑to‑market network position Nestlé to capitalize on medically indicated hydrolyzed products. Its branded extensive hydrolysates cater to clear clinical use-cases, making scale and regulatory bandwidth competitive advantages.
- Danone / Nutricia (Paris, France) : With focused eHF offerings and recent geographic expansion, Danone emphasizes speciality clinical nutrition channels. Strategic play: accelerate clinical evidence generation in priority markets to secure formulary placement and pediatric endorsement.
- Mead Johnson / Reckitt (Evansville, USA) and Abbott Nutrition (Abbott Park, USA) : These players combine established pediatric clinician relationships with portfolio breadth. Expect continued investment in clinician-facing science, and selective reformulation where regulation changes demand alignment.
- Perrigo (Dublin, Ireland) : The private-label and store-brand specialist presents a twofold competitive pressure — downward price pressure in mainstream channels and rapid shelf expansion. Retailers armed with private labels will leverage cost advantages to capture value segments.
- Meiji, HiPP, Arla Foods Ingredients, FrieslandCampina : These manufacturers and ingredient suppliers play specialized roles — from trusted regional brands (Meiji, HiPP) to upstream whey hydrolysate capacity and co‑development (Arla, FrieslandCampina). For manufacturers, securing multi‑sourced hydrolysates is a top priority given the role of milk‑based hydrolysates in the ingredient mix.
Regulatory and Ingredient Dynamics — What to Watch in 2026
Regulation will be a primary driver of near‑term competitive advantage. The EU’s late‑2025 amendment (effective January 2026) changes both compositional and labeling constraints for protein hydrolysate formulas — a change that will affect reformulation lead times, analytical validation and supplier qualification. In the United States, FDA maintains strict nutrient and labeling requirements (including the permissible framing of reduced‑risk statements for specific partially hydrolyzed formulas), and periodic product listings published by the agency signal market availability and clearance.
On the ingredient side, established dairy supply chains favor milk-based hydrolysates: market analysis indicates milk-based hydrolysates (notably whey protein hydrolysate) are projected to account for the majority share of hydrolysate consumption in 2026 due to suitability for infant nutrition and supply chain maturity. That concentration creates both an opportunity (scale economies, consistent clinical profiles) and a risk (price and availability volatility following dairy cycle shocks).
Six Strategic Actions for 2026
We recommend a focused six-point agenda for commercial and corporate leaders planning 2026 moves:
- Build a regulatory acceleration team: Integrate regulatory, clinical and R&D functions into a cross-functional “2026 readiness” program to compress reformulation timelines in the EU and align labeling in the US.
- Prioritize ingredient resilience: Secure diversified supply agreements for hydrolyzed whey and evaluate backward integration or strategic minority stakes in ingredient producers to hedge against supply shocks.
- Segment product portfolios by value creation: Redeploy marketing and R&D spend toward clinically differentiated SKUs that command premium pricing and reduce vulnerability to private-label competition.
- Channel-specific commercialization: Tighten playbooks for pharmacy/clinical channels versus mass retail and e‑commerce — clinician endorsement is critical for specialty hydrolyzed lines, while digital channels accelerate trial and repeat purchase in younger caregiver cohorts.
- Monitor M&A for capability gaps: Target small‑to‑mid‑cap acquisitions that bring regulatory know‑how, clinical data, or ingredient security to accelerate time-to-market under new rules.
- Hedge on clinical evidence: Invest selectively in RCTs and real‑world evidence to support permissible claims and pediatrician adoption, especially where regulatory changes create new categories.
How PW Consulting’s Report Supports Execution
Our study is designed to be operational from day one of 2026 planning cycles. Clients receive not only market sizing and trend analysis but also executable templates: SKU rationalization matrices, capex sensitivity models for co‑packing and manufacturing changes, retailer negotiation playbooks, and a timeline of regulatory milestones tied to cost and revenue impacts. For corporate strategy teams and private equity investors, the report contains scenario-modeled IRR impacts under conservative, base and aggressive commercialization cases.
Given the market’s moderate-to-high concentration (top three ~68% and top five ~79%), consolidation and capability-based M&A are practical levers to reshape competitive dynamics — our M&A module highlights targets, valuation benchmarks and integration risk frameworks.
Next Steps and Access to the Full Study
This brief outlines the strategic stakes and the primary levers companies must pull in 2026. To preserve the report’s utility as a decision-making asset, we have intentionally provided aggregated topline data and strategic frameworks here while reserving the detailed regional, product and channel splits — including the interactive financial model and supplier-level intelligence — for the full report.
To explore the full dataset, download the interactive dashboard, or commission a tailored briefing and scenario run for your organization, visit the full Hydrolyzed Formula Milk Powder Market report on our website or contact PW Consulting’s strategy team. Our experts are available to run bespoke sensitivity analyses keyed to your product portfolio, supply chain footprint and M&A appetite.
PW Consulting — Translating market insight into measurable strategy for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hydrolyzed Formula Milk Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biodegradable Micro Screws Market Set to Climb from USD 308.55 Million in 2025 to USD 544.41 Million by 2032 at an 8.45% CAGR
By pmarketresearch, 2026-07-13
Biodegradable Micro Screws Market — Strategic Outlook for 2026: PW Consulting’s Actionable Intelligence
Executive summary
PW Consulting’s latest market research on biodegradable micro screws arrives at a pivotal moment for orthopedic device strategists. After a steady recovery and expanded adoption across trauma, craniomaxillofacial and soft-tissue fixation, the global market accelerated through the early 2020s and reached an inflection point in 2025. Our analysis shows the market expanding from roughly USD 212 million in 2020 to about USD 308 million in 2025, and we project continued momentum at a compound annual growth rate (CAGR) of approximately 8.45% across the 2026–2032 forecast window. By 2032 the sector is expected to surpass the half‑billion dollar mark, underscoring rising clinical demand and commercial opportunity.
Biodegradable Micro Screws Market
Why this report matters for 2026 decision-makers
- Timing and trajectory: 2026 is the year when regulatory, clinical and reimbursement tailwinds converge to enable commercialization scale for several bioabsorbable platforms. A clear, data-driven forecast helps manufacturers and investors prioritize near-term resource allocation.
- Execution focus: The market is not a binary race; success will depend on integrating regulatory strategy, clinical evidence generation, manufacturing scale‑up and payer engagement in a coordinated program. Our report provides the operational playbooks necessary to execute in 2026 and beyond.
- Risk mitigation: Raw material volatility, emerging competitive product families and evolving regulatory pathways create execution risk. We quantify sensitivities and outline hedging and sourcing strategies that materially reduce time-to-revenue risk.
Market trajectory and what the numbers tell you
High-level volume and revenue trends point to sustained, double-digit momentum in clinically mature indications while newer applications (mini-fracture fixation, resorbable anchors in sports medicine, pediatric trauma) are driving incremental revenue streams. The headline CAGR of 8.45% encapsulates both replacement cycles (migration away from permanent metal implants in indicated patients) and incremental adoption driven by improved device designs and expanded regulatory clearances. For executives evaluating R&D spend or M&A targets, the forecast provides a disciplined basis to model three-year payback scenarios and longer-term IRR expectations.
Biodegradable Micro Screws Market
Competitive landscape — who matters and why
The market is moderately concentrated: leading incumbents and well-capitalized challengers control a meaningful share of commercialized platforms, while a broader cohort pursues niche clinical and geographic opportunities. Key players that shape competitive dynamics include:
Biodegradable Micro Screws Market
- Bioretec Ltd (Tampere, Finland) — A technology-led player with magnesium alloy and self‑reinforced PLGA portfolios. Recent regulatory and commercial milestones (including CE approvals and breakthrough designations) materially lower barriers for scale‑up in regulated markets and create first-mover advantages for magnesium‑based micro fixation systems.
- Inion Oy (Tampere, Finland) — Focused on bioabsorbable polymer implants with product families designed for predictable resorption timelines and compatibility with standard instrumentation. Their smaller-diameter offerings and clinical positioning make them a competitive reference in procedures requiring finer fixation.
- Arthrex, Inc. (Naples, FL, USA) — Brings deep clinical relationships and a broad portfolio of bio-composite and enhanced PLLA devices. Their hybrid product strategy (composite + biologic additives) influences pricing and surgeon preference dynamics in soft‑tissue and ligament repair markets.
- Syntellix AG (Hannover, Germany) — A leader in magnesium alloy resorption chemistry with CE-marked platforms used across trauma and reconstruction. Their real-world clinical footprint and material differentiation are central to the magnesium vs. polymer competitive narrative.
Recent company-level developments materially change competitive positioning. Notably, Bioretec’s regulatory momentum in 2025–2026—including CE approvals, US payment pathway recognitions and breakthrough device designations—creates a tactical window for market penetration in selected segments. Competitive responses should be modeled as part of any commercialization plan for 2026.
Regulatory and reimbursement dynamics
Regulatory pathways for bioabsorbable implants are maturing rapidly. Several magnesium‑based and polymer platforms have benefited from accelerated pathways and novel device designations, which shorten time-to-market for compelling clinical use-cases. Parallel to regulatory progress, early reimbursement decisions and transitional payment mechanisms in key markets are beginning to de-risk adoption economics for hospitals and health systems.
For market entrants, the strategic implication is twofold: invest early in a regulatory strategy that maps device chemistry to the fastest viable pathway, and build evidence dossiers explicitly designed for payer dialogue (health economic models, real-world outcomes and complication-avoidance data sets). PW Consulting’s report includes a step‑by‑step regulatory playbook and payer engagement templates tailored to the major regulatory archetypes.
Supply chain, raw materials and manufacturing considerations
Supply-side factors are a practical constraint that is often underestimated. Medical‑grade biopolymers and specialty magnesium alloys are subject to feedstock price swings, certification timelines and long lead times for qualified suppliers. These inputs interact with device tolerance and sterility processes, which in turn influence yield and cost of goods.
Our analysis highlights actionable levers to protect margin and continuity: dual-sourcing strategies for critical polymers and alloys, qualifying regional partners for buffer capacity, and early vertical integration options for manufacturers seeking to control alloy chemistry. We also present scenario-based cost models that show how raw material price trajectories can affect unit economics across five commercialization scenarios.
Clinical evidence and surgeon adoption
Surgeon acceptance is the proximate driver of adoption. Clinical evidence that addresses two clinician concerns—(1) predictable resorption behavior without adverse tissue response, and (2) mechanical reliability during the biologic remodeling window—wins surgeries. Our clinical mapping identifies the types of trials, registry designs and perioperative training programs that accelerate adoption curves most efficiently.
Commercial strategy and go‑to‑market playbooks for 2026
- Segmented launch sequencing: Prioritize indications and hospital archetypes where economic upside and clinical necessity align, then expand through evidence-led scale.
- Surgeon network activation: Invest in targeted Key Opinion Leader (KOL) engagement and hands-on training rather than broad promotional spend in year one.
- Service bundling: Couple device sales with instrument kits, digital surgical planning, or warranty programs to increase switching costs and justify premium pricing.
- Partnership models: Assess co-development or distribution alliances with firms that offer complementary reach or manufacturing capabilities to accelerate access without full-scale capital outlay.
What’s inside the PW Consulting report (practical components)
Our full report is built as a pragmatic decision-support tool for executives and investors. It includes:
- Bottom-up market sizing and a seven-year forecast with sensitivity analyses by clinical pathway and material platform;
- Competitive benchmarking and product-mapping, including clinical claims, device dimensions, and manufacturing footprint comparisons;
- Regulatory playbooks for major jurisdictions and reimbursement strategy templates targeted to payer evidence requirements;
- Commercialization blueprints: launch sequencing, pricing models, and hospital contracting strategies;
- Supply chain risk assessment with supplier scorecards and sourcing continuity plans;
- Clinical evidence roadmaps and study protocols optimized for scaling adoption;
- M&A and partnership screens with prioritized target profiles for bolt-on acquisitions and strategic alliances;
- Scenario planning tools and financial models you can adapt to your internal assumptions.
Consistent with the “trailer” principle, this public note highlights the substantive insights while preserving detailed segment-level splits and proprietary scenario outputs for report subscribers.
Strategic recommendations — immediate next steps for 2026
- Run a rapid internal gap analysis against the PW Consulting evidence checklist: regulatory readiness, clinical evidence, manufacturing capacity and payer engagement materials.
- Prioritize a pilot commercialization market where regulatory and reimbursement dynamics are the most favorable, and use that launch as a proof point to unlock further investment.
- Secure supply options for medical‑grade polymers and magnesium feedstocks now—qualification cycles can take 6–12 months and will be a gating factor.
- Invest in a focused KOL program tied to prospective registries to accelerate credible real-world evidence generation.
- Evaluate targeted partnerships to obtain distribution or manufacturing scale without dilutive capital raises in the near term.
Conclusion and call to action
The biodegradable micro screws market is entering a commercialization phase where clinical value, regulatory clarity and payer recognition intersect to create sustainable commercial opportunity. PW Consulting’s new report provides the granular, executable intelligence that leadership teams need to make 2026 a year of meaningful progress rather than incrementalism. For teams preparing budgets, prioritizing R&D, or screening acquisition targets, the report serves as both a roadmap and a playbook.
To access the full data tables, segmentation analytics, and executable templates referenced here, please visit our report landing page or contact the PW Consulting healthcare strategy team for a briefing and bespoke modeling session.
For detailed analysis of this topic, please visit the official page: Biodegradable Micro Screws Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: GPS & GNSS Receivers in Aviation Market to Grow at a 6.75% CAGR Through 2032
By pmarketresearch, 2026-07-13
GPS and GNSS Receivers in Aviation Market — Strategic Insights for 2026 Decision-Makers
As airspace modernization, geostrategic tensions, and higher integrity requirements reshape airborne navigation, organizations must translate technical trends into actionable strategy. PW Consulting’s latest market study on GPS and GNSS receivers in aviation frames that translation for 2026 decision cycles. The report shows that the global market — having reached approximately USD 1,850 million in the 2025 base year — is on a sustained growth path, with projections reaching roughly USD 2,923 million by 2032 at a compound annual growth rate (CAGR) of 6.75% over the 2026–2032 forecast window. These headline figures understate the structural shifts driving procurement, R&D, and partnership priorities across airlines, OEMs, defense programmes, and avionics suppliers.
Gps And Gnss Receivers In Aviation Market
What this report delivers — practical, decision-ready intelligence
-
A concise executive framework that maps regulatory catalysts, threat vectors (jamming/spoofing), and mission requirements to receiver-class decisions — civilian, business/general aviation retrofit, and military assured PNT.
Gps And Gnss Receivers In Aviation Market -
Vendor benchmarking and capability matrices covering certification status, anti-jam/anti-spoofing effectiveness, multi-frequency support, GNSS+INS integration, and roadmap alignment with NextGen/SESAR programmes.
Gps And Gnss Receivers In Aviation Market -
Procurement playbooks and retrofit / new-build total cost of ownership (TCO) models that operationalize certification timelines, lifecycle support, and avionics integration risk.
-
Scenario-based stress tests quantifying operational exposure to localized interference and global service degradation, with recommended mitigation portfolios (hardware, software, and operational procedures).
-
Commercial opportunities and M&A scouting templates for investors and corporates seeking to position across the value chain — from OEM modules to integrated avionics and cyber-resilient PNT services.
Why 2026 is a pivot point
Several converging drivers make 2026 a decisive planning year. Regulatory programmes (notably NextGen and SESAR) are accelerating adoption of L5 and DFMC-capable receivers to enable performance-based navigation and precision approaches. At the same time, aviation authorities have published updated interference guidance, reflecting a steep increase in jamming and spoofing incidents over recent years. National mandates and regional rules — such as dual-frequency compliance requirements from major airworthiness authorities — are accelerating retrofit demand and shaping OEM specifications.
For operators and systems integrators, this creates a dual challenge: deploy technology that meets emergent safety and navigation performance standards while also hedging against an increasingly contested signal environment. The commercial implication is that buyers are no longer making decisions based purely on position accuracy metrics; resilience, certification velocity, and integration risk dominate procurement criteria.
Technology and capability trends to watch
-
Resilient PNT architectures — Multi-frequency, multi-constellation receivers paired with inertial measurement systems (GNSS+INS) are now baseline design choices for mission-critical platforms. Anti-jam and anti-spoofing countermeasures, both at the RF front-end and in signal-processing algorithms, are becoming de facto requirements for defense and key commercial applications.
-
Certification and retrofit readiness — Suppliers who can demonstrate certified retrofit pathways (EASA/FAA/CAAC compliance) and offer installation-friendly form factors are gaining faster adoption in the business and general aviation segments.
-
Modularization and OEM ecosystems — There is a divergence between vertically integrated avionics suites and modular OEM receiver suppliers. The former target full-system value capture; the latter focus on high-precision modules and software IP that can be embedded across platforms.
-
Software-defined resilience — Firmware-upgradeable anti-jam/anti-spoofing and the ability to ingest alternative PNT sources (e.g., terrestrial ranging, timing over data links) are strategic differentiators that reduce hardware replacement cycles.
Competitive landscape — what the market structure implies
The market exhibits moderate concentration: the top-three vendors control a meaningful portion of market value, and the top-five capture a clear majority share. This structure favors players who combine certification credentials, breadth across civil and military portfolios, and demonstrable operational deployments.
Key incumbent profiles illustrate the strategic segmentation:
-
Garmin (Schaffhausen) — Strength in certified avionics and retrofit solutions for general aviation and business jets; competitive advantage lies in panel-mount and embedded options that meet FAA/EASA standards and fast aftermarket adoption cycles.
-
Honeywell — Broad avionics integration capability with GNSS receivers and inertial systems for commercial and defense platforms. Honeywell’s value is in aircraft-system integration and lifecycle support at fleet scale.
-
Collins Aerospace (RTX) — Supplier of multi-constellation receivers and integrated navigation products for commercial and military applications, with an emphasis on mission systems and upgrade paths for secure navigation services.
-
Thales — Focused on resilient PNT with certified receivers offering LPV/RNP and anti-jam features; recent product launches underline a push into compact, high-assurance solutions for both crewed and unmanned platforms.
-
Trimble and NovAtel — OEM-grade, high-precision positioning specialists that feed aircraft manufacturers and government programmes where centimeter-level accuracy and SBAS integrity are priority criteria.
-
Defense-focused suppliers (Northrop Grumman, L3Harris, BAE Systems) — Emphasize M-code capable receivers, embedded GPS/INS modernizations, and solutions designed for contested electromagnetic environments.
-
Specialist entrants (Septentrio) — Offer advanced multi-frequency modules with strong anti-jam and anti-spoofing claims targeting a niche of high-precision and high-integrity applications.
Recent product and regulatory developments underscore this dynamic. Strategic deliveries of modernized embedded navigation systems and new anti-jam compact receivers have emerged alongside aviation authority guidance that raises operational reporting and mitigation expectations for interference events. For purchasers, this means vendor selection must account for both product capability and the supplier’s ability to meet evolving regulatory evidence requirements.
Operational and commercial implications — recommended actions for 2026 planners
Leaders must treat receiver procurement as a systems decision that spans policy, operations, and engineering. The following priorities distill the most consequential moves:
-
Prioritize resilient PNT in capital plans — Require demonstrable anti-jam/anti-spoofing performance and GNSS+INS integration capability in procurement specifications. Incorporate certification milestones into supplier contract terms.
-
Diversify supplier risk — Balance incumbents with specialist OEMs to avoid single-source exposure, and require modular interfaces to enable later upgrades without full-system replacement.
-
Accelerate retrofit strategies — For mixed fleets, develop prioritized retrofit roadmaps that align with airworthiness mandates and minimize downtime through staged installation plans and common avionics baselines.
-
Embed scenario planning — Quantify operational exposure to localized interference and plan contingency navigation procedures, pilot training updates, and ATC coordination protocols.
-
Invest in software and data — Allocate R&D to firmware upgradability, anomaly detection, and integration of alternative PNT data feeds to extend product life and reduce hardware refresh costs.
-
Evaluate partnership and M&A plays — Identify technology niches (e.g., front-end anti-jam RF, INS sensor fusion, certified retrofit packaging) that are attractive for bolt-on acquisitions or strategic alliances.
Why PW Consulting’s report is a 2026 boardroom tool
This study translates market projections and technical intelligence into executable plans. Beyond headline growth — the projected market expansion from the 2025 base to 2032 at a 6.75% CAGR — the report delivers templates for procurement, a vendor capability scoring system, regulatory compliance matrices, and tailored scenario analyses. These deliverables are built for executives and functional leads who must justify capital allocations, adjust product roadmaps, and defend resilience investments to boards and auditors.
Importantly, PW Consulting’s approach follows the “need-to-act” principle: highlight where decisions materially affect operational continuity and cost, then provide the tactical tools necessary to execute. For firms that must reconcile fleet modernization with constrained budgets and certification timelines, the report frames the trade-offs and prescribes concrete next steps.
Next steps — how to use the intelligence
-
For procurement teams: use the vendor scorecards and TCO models to short-list suppliers and negotiate milestone-based contracts that link payment to certification and field-proven performance.
-
For product and engineering: adopt the technology roadmap and integration checklists to prioritize firmware modularity and sensor fusion investments that extend platform life.
-
For risk and operations leadership: operationalize the scenario stress-tests to update emergency procedures, ATC coordination, and crew training materials.
-
For investors and corporate strategists: interrogate the market consolidation metrics and M&A templates to identify value-creation targets across OEM modules, avionics integration, and PNT services.
PW Consulting’s full report contains the granular segmentation, regional and application-level forecasts, and detailed vendor market shares that many teams will need to finalize procurement and investment decisions. These datasets and the full suite of practical tools are available in the report’s comprehensive deliverables; PW Consulting can also provide tailored workshops to map the findings to a client’s specific fleet and programme constraints.
For organizations preparing budgets, specification documents, or M&A theses in 2026, this report converts macro momentum into pragmatic action: the growth runway is clear, but the winners will be those who couple technology selection with regulatory foresight and operational resilience.
For detailed analysis of this topic, please visit the official page: Gps And Gnss Receivers In Aviation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com