

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Rack-and-Pinion Construction Elevator Market to Expand at a 7.0% CAGR, New Insight Report Shows

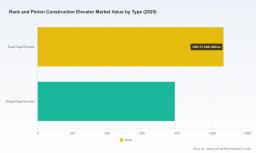
Rack and Pinion Construction Elevator Market: Strategic Imperatives for 2026 Decision‑Makers
As built environments become taller, more complex and time‑sensitive, rack and pinion construction elevators have moved from niche utility to a strategic asset on active sites and in long‑life industrial facilities. PW Consulting’s latest market study shows the global rack and pinion construction elevator market reached USD 1,852.08 Million in 2025 and is projected to expand at a 7.0% compound annual growth rate through the 2026–2032 forecast window, reaching approximately USD 2,974.03 Million by 2032. This briefing teases the practical, decision‑focused intelligence contained in the full report and highlights the near‑term choices corporate leaders must get right in 2026.
Rack And Pinion Construction Elevator Market
Why this report matters for 2026 strategy
-
Timing and capital allocation: With a steady mid‑single digit CAGR, procurement and replacement cycles for hoists should be integrated into 3– to 7‑year CapEx plans rather than treated as ad‑hoc site purchases.
Rack And Pinion Construction Elevator Market -
Cost‑and‑risk management: Recent raw material inflation and regulatory pressure mean organizations must quantify steel exposure, maintenance frequency and compliance costs before committing to fleet expansion or long‑term leases.
Rack And Pinion Construction Elevator Market -
Competitive positioning: Suppliers and fleet operators are diversifying service portfolios—construction teams and industrial operators must choose between turnkey rental, hybrid service contracts and outright ownership based on lifecycle TCO and operational tempo.
What the report delivers — actionable modules
-
Robust market sizing and scenario forecasts that map demand corridors under several macroeconomic and steel‑price scenarios, enabling finance teams to stress‑test budgets against upside and downside demand paths.
-
Practical procurement playbooks that translate industry standards (OSHA, ANSI/ASME drafts) into tender language, warranty clauses and acceptance tests suited to construction vs industrial shutdown use cases.
-
Fleet optimization tools that compare CapEx ownership, long‑term rental, and managed‑service models using plug‑and‑play financial tables and sensitivity drivers (utilization, downtime cost per hour, mobilization expense).
-
Maintenance and safety matrices specifying periodic testing cadence, spare‑parts inventories, and service‑level KPIs aligned with manufacturer recommendations and common practice for safety devices.
-
Deal screening criteria for M&A and J/V opportunities, including integration checklists and quick valuation heuristics tailored to manufacturers, service providers and fleet operators.
-
Customizable presentation templates and executive one‑pagers for stakeholder buy‑in, permitting and capital committees.
Market dynamics shaping near‑term decisions
Three dynamics are converging on procurement and operations teams in 2026.
-
Raw material volatility. Steel price trajectories have shifted structurally: US hot rolled coil prices moved materially higher between early 2025 and early 2026, and benchmark Chinese steel prices showed incremental increases year‑over‑year into spring 2026. For asset‑heavy equipment such as rack and pinion systems, even modest raw material cost moves can change OEM pricing and spare‑parts economics rapidly. Scenario analysis in the report quantifies breakpoints at which ownership becomes uneconomic versus rental.
-
Regulatory tightening and evolving standards. OSHA rule sets remain the baseline for temporary hoists and material handling on US sites; proposed revisions to the ASME A17.1 code introduce more prescriptive language on equipment locations and periodic testing standards for rack‑and‑pinion systems. Operators must budget for increased inspection frequency and possible retrofits to meet updated definitions and testing requirements.
-
Lifecycle maintenance and safety practice. Industry practice and several OEM manuals recommend semi‑annual testing of safety devices, and component replacement cycles commonly fall in the 3–4 year window for high‑use fleets. These practices directly affect scheduled downtime and spare parts planning; on‑site safety testing influences contractor selection and site sequencing.
Competitive landscape: what to watch in 2026
The market displays a moderate level of concentration: the top three suppliers account for roughly 31.5% of supply capacity, while the top five approach just under half of the market. That structure creates meaningful opportunities for regional specialists and value‑added service providers while preserving scale advantages for global OEMs.
-
Global OEMs with integrated product lines and standards compliance (e.g., Alimak Group AB and associated brands) continue to leverage scale for large, high‑capacity permanent and temporary installations, emphasizing compliance with international standards and high‑capacity personnel/material transport solutions.
-
Specialist European manufacturers (e.g., GEDA, Maspero) offer engineered solutions for industrial and power‑sector projects where custom structural integration and certified compliance are premium purchase drivers.
-
North American players (examples include USA Hoist / Mid‑American and fleet operators like McDonough) bring deep local service networks, rapid mobilization and fleet management experience—attributes that often trump lowest initial price when schedule risk is high.
-
Regional suppliers and assemblers (notably from Asia) are increasing product cadence and feature sets, from CE‑certified designs to higher payload models. Recent model introductions and industry articles through 2025–2026 reflect a steady stream of product refreshes and marketing that will influence procurement cycles.
Recent industry activity underlines these trends: fleet operators and service providers are publishing use‑case analyses emphasizing downtime reduction during industrial shutdowns, while several OEMs announced new model releases in early 2026 targeted at improved payload efficiency and modularity. Taken together, these moves signal a market balancing product innovation with service‑led differentiation.
Strategic playbook for 2026 executives
-
Quantify steel exposure in procurement models. Build sensitivity bands (±10–25% steel cost) into OEM quotations and assess the impact on life‑cycle pricing; negotiate material price pass‑through clauses or multi‑year fixed‑price tranches where appropriate.
-
Adopt a portfolio approach to fleet ownership. Use utilization thresholds to determine whether to buy, rent, or enter managed‑service agreements; run a break‑even analysis that includes mobilization, certification, and scheduled safety testing costs.
-
Standardize technical and contractual specifications across sites. Draft tender documents that enforce minimum safety device testing frequency, spare parts provisioning and KPIs for mean time to repair (MTTR) and availability.
-
Invest in predictive maintenance and telematics. For high‑use assets, telematics reduces unscheduled downtime and optimizes spare parts inventories—capture the ROI within 18–36 months in typical high‑utilization scenarios.
-
Pursue selective partnerships rather than full ownership for new geographies. Collaborate with regional fleet operators for mobilization and local compliance while preserving OEM relationships for technical support and warranty continuity.
-
Prepare for tightening standards. Budget for periodic testing and potential retrofits tied to evolving ASME/ANSI/OSHA guidance; ensure procurement timelines allow for certification and acceptance testing prior to mobilization.
How PW Consulting accelerates your 2026 decision cycle
Our full report goes beyond high‑level forecasts to deliver implementation tools that procurement, operations and corporate development teams can use immediately. Clients receive: detailed scenario models, procurement templates, maintenance and testing matrices, a supplier short‑list methodology tailored to risk appetite, and an acquisition screening pack for targets within manufacturing and fleet services.
If your 2026 agenda includes fleet expansion, rental strategy optimization, or an acquisition in the rack and pinion space, PW Consulting can fast‑track the analytical groundwork and stakeholder materials required for board‑level approval. The published market forecast (including the headline USD 1,852.08 Million market size for 2025 and the 7.0% CAGR through 2032) is only the starting point; the full intelligence package contains the segment‑level and regional breakouts, supplier scorecards and financial models that translate those macro numbers into executable decisions.
Next step
This briefing is a preview of the operational playbook and competitive detail contained in our market research. To access the full dataset, segmented models and supplier scorecards that underpin these recommendations, please consult the PW Consulting report landing page or contact your engagement lead for a secured executive summary and a hosted walk‑through of the decision‑support tools. In a market moving at the rhythm of steel prices, safety standards and project scheduling, having the right data and playbook is the difference between reactive procurement and strategic advantage in 2026.
For detailed analysis of this topic, please visit the official page: Rack And Pinion Construction Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com