

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Desktop Virtualization Software Market to Surge from USD 19,450.6 Million in 2025 to USD 44,029.5 Million by 2032 at a 12.38% CAGR

Desktop Virtualization Software Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
Executive summary
The desktop virtualization software market is entering a decisive phase where technology maturation, regulatory pressure, and changing consumption models converge to reshape enterprise IT strategy. Our latest PW Consulting market study — anchored on a 2025 base year and projecting through 2032 — shows the market roughly doubling in size over the last five years and continuing strong, with a compounded annual growth rate of 12.38% across the forecast horizon. By 2025 the market had reached just under USD 19.5 billion (revenue basis, millions USD unit), and our scenario analysis points to an exit market of approximately USD 44.0 billion by 2032 under the base forecast. At the same time, concentration metrics indicate the top vendors control a substantial majority of revenue, underscoring a competitive environment that combines dominant cloud platforms with specialized niche providers.
Desktop Virtualization Software Market
Why this report matters for 2026 decision cycles
For CIOs, CTOs, and procurement leaders finalizing budgets and strategic roadmaps in 2026, the decision to refresh desktop virtualization strategies is no longer tactical — it’s transformational. This report translates macro momentum into actionable intelligence: when to accelerate cloud-first migrations, how to structure hybrid operating models, what cost levers to expect from security and compliance, and how vendor licensing shifts can alter multi‑year TCO. We deliberately present deep, practitioner‑oriented guidance while reserving the full granular segment dataset for subscribers — a design choice that balances public strategic signaling with the confidentiality enterprise buyers require.
Desktop Virtualization Software Market
What’s in the report (practical, operational content)
- Market sizing and forecast methodology, including scenario and sensitivity analyses covering 2026–2032.
- Demand-side drivers and buyer personas mapped to real procurement cycles, with workload classification templates to prioritize migration candidates.
- Deployment decision framework (cloud vs. on‑premises vs. hybrid) with a step‑by‑step playbook for pilots and scale‑up phases.
- Full vendor scorecards and comparative capability matrices covering product architecture, management tooling, security controls, and channel models.
- TCO and ROI models with editable inputs for hardware, licensing, workforce, and operational security add‑ons; a practitioner’s guide to capture hidden costs.
- Compliance and data‑sovereignty checklists aligned to major regimes (GDPR, HIPAA, PCI‑DSS) and guidance on mitigating legal exposure linked to extraterritorial laws.
- Procurement negotiation templates and SLA clauses tuned for cloud desktop engagements and managed service contracts.
- Case studies and migration templates from multi‑industry implementations, plus a risk register for common failure modes.
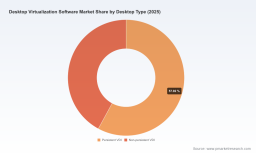
Note: To preserve the value of the research as a decision‑ready asset, public summaries omit the full segmentation tables. The report contains comprehensive breakouts by region, deployment mode, and desktop type — available through the report portal.
Desktop Virtualization Software Market
Key market dynamics shaping vendor and buyer behavior
- Cloud acceleration vs. hybrid realism: Enterprises are accelerating cloud desktop adoption for scale and management simplicity, yet hybrid deployments remain the pragmatic choice for regulated workloads and latency‑sensitive use cases. Our forecasting reflects persistent demand for both approaches.
- Licensing and activation risk: Vendor moves to cloud‑centric licensing models and mandatory activation services create migration windows that require active vendor engagement and careful cutover planning to avoid service disruption.
- Security and operational cost trade‑offs: Zero Trust enforcement, device compliance checks, and advanced monitoring materially increase operational spend. These are often licensed or delivered as premium modules and must be included in three‑ to five‑year TCO scenarios.
- Regulatory and sovereignty pressures: Data residency concerns and extraterritorial legislation are reshaping provider selection, pushing some buyers toward localized deployments or regionally certified partners.
Competitive landscape — who matters and what to watch
The vendor landscape is a hybrid of hyperscaler cloud platforms, legacy virtualization specialists, and agile niche players. The market’s structure favors integrated cloud ecosystems while leaving room for differentiation around management simplicity, application performance, and enterprise security posture. Key players profiled in the report include:
- Microsoft Corporation — Strong momentum around Azure Virtual Desktop and Windows 365, with deep integration into Microsoft 365 and hybrid options that appeal to organizations standardizing on Microsoft stacks. Recent platform updates have extended application‑attach and session host support, underscoring continued investment in scale and manageability.
- Amazon Web Services (AWS) — Amazon WorkSpaces continues to broaden regional availability and platform capabilities, including recent support for next‑generation Windows server releases and TPM‑enhanced security bundles. AWS’s flexible pricing and global footprint make it a credible choice for cross‑region enterprises.
- Citrix Systems, Inc. — Citrix remains a go‑to for high‑performance remote access and secure application delivery, but recent mandates around cloud‑based licensing activation require customers to plan migrations carefully to maintain continuity.
- Omnissa (formerly VMware) — Enterprise VDI solutions with strong hybrid/on‑prem integration appeal to organizations prioritizing in‑house control and advanced virtual desktop management.
- Nutanix, Parallels, Inuvika, and Oracle — These vendors provide differentiated choices: Nutanix with hybrid integration plays, Parallels for SMB simplicity, Inuvika as a cost‑effective open alternative for Linux workloads, and Oracle for customers seeking tight coupling with enterprise database and cloud services.
Our market concentration analysis shows the largest vendors account for a dominant share of market revenue, creating both strategic dependencies and competitive opportunities for specialized providers. For buyers, this means negotiating power exists but requires a disciplined approach to vendor comparison beyond sticker pricing.
Recent vendor developments to monitor
- AWS expanded WorkSpaces regional availability and enhanced platform support for recent Windows Server releases (notable updates in Q1–Q2 2026).
- Microsoft enhanced application‑attach capabilities to support newer session host versions, improving lifecycle flexibility for application management.
- Nutanix announced public‑preview integrations for hybrid Azure Virtual Desktop scenarios on its AHV hypervisor — a notable signal of increased interoperability between hyperconverged infrastructure vendors and hyperscalers.
- Citrix’s migration to a cloud License Activation Service introduced a hard timeline that has implications for licensing continuity and migration project sequencing.
Risks and compliance considerations
Implementations face a confluence of legal, operational, and technical risks. From a compliance perspective, VDI deployments used in regulated industries must demonstrate workload isolation, encryption, and auditability consistent with HIPAA, PCI‑DSS, and GDPR obligations. Data sovereignty and the potential applicability of extraterritorial laws (for example, the US CLOUD Act) can constrain public cloud choices and necessitate hybrid or localized architectures. Operationally, the incremental workforce and tooling needed to enforce Zero Trust and continuous monitoring are frequently underestimated; our field work shows these items are common drivers of unexpected cost overruns.
Practical next steps for 2026 buyers
- Initiate an application workload mapping exercise this quarter to classify candidates for persistent vs. non‑persistent delivery and to prioritize migration batches.
- Run vendor‑neutral TCO scenarios that include security add‑ons, licensing activation conditions, and regional compliance costs over a five‑year horizon.
- Engage early with incumbent vendors where mandatory license activation or migration windows exist to avoid service interruptions and secure transition discounts.
- Pilot hybrid reference architectures for regulated workloads, validating latency, user experience, and data residency controls before wide rollout.
- Update procurement templates to include SLA points for license portability, data residency guarantees, and clear exit provisions.
How PW Consulting can help
PW Consulting’s Desktop Virtualization Software Market Report is designed to be a working resource for practitioners: not a passive briefing, but a playbook. Subscribers receive the full dataset (detailed segmentation breakouts, vendor scorecards, and editable financial models) alongside advisory hours for customized scenario modeling and implementation planning. For teams gearing up for procurement cycles and board‑level approvals in 2026, our analysts can accelerate vendor evaluations, quantify migration costs, and build defensible roadmaps aligned to your risk tolerance and regulatory footprint.
To access the full intelligence — including the complete regional, deployment‑mode, and desktop‑type breakouts that inform the TCO and segment forecasts — please visit the PW Consulting report landing page for purchase and subscription options. The public summary above highlights the strategic contours; the full report equips your team to make the specific, defensible decisions required this year.
For detailed analysis of this topic, please visit the official page: Desktop Virtualization Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com