

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: GPS & GNSS Receivers in Aviation Market to Grow at a 6.75% CAGR Through 2032

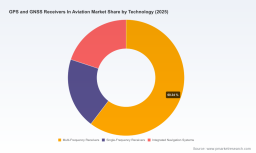
GPS and GNSS Receivers in Aviation Market — Strategic Insights for 2026 Decision-Makers
As airspace modernization, geostrategic tensions, and higher integrity requirements reshape airborne navigation, organizations must translate technical trends into actionable strategy. PW Consulting’s latest market study on GPS and GNSS receivers in aviation frames that translation for 2026 decision cycles. The report shows that the global market — having reached approximately USD 1,850 million in the 2025 base year — is on a sustained growth path, with projections reaching roughly USD 2,923 million by 2032 at a compound annual growth rate (CAGR) of 6.75% over the 2026–2032 forecast window. These headline figures understate the structural shifts driving procurement, R&D, and partnership priorities across airlines, OEMs, defense programmes, and avionics suppliers.
Gps And Gnss Receivers In Aviation Market
What this report delivers — practical, decision-ready intelligence
-
A concise executive framework that maps regulatory catalysts, threat vectors (jamming/spoofing), and mission requirements to receiver-class decisions — civilian, business/general aviation retrofit, and military assured PNT.
Gps And Gnss Receivers In Aviation Market -
Vendor benchmarking and capability matrices covering certification status, anti-jam/anti-spoofing effectiveness, multi-frequency support, GNSS+INS integration, and roadmap alignment with NextGen/SESAR programmes.
Gps And Gnss Receivers In Aviation Market -
Procurement playbooks and retrofit / new-build total cost of ownership (TCO) models that operationalize certification timelines, lifecycle support, and avionics integration risk.
-
Scenario-based stress tests quantifying operational exposure to localized interference and global service degradation, with recommended mitigation portfolios (hardware, software, and operational procedures).
-
Commercial opportunities and M&A scouting templates for investors and corporates seeking to position across the value chain — from OEM modules to integrated avionics and cyber-resilient PNT services.
Why 2026 is a pivot point
Several converging drivers make 2026 a decisive planning year. Regulatory programmes (notably NextGen and SESAR) are accelerating adoption of L5 and DFMC-capable receivers to enable performance-based navigation and precision approaches. At the same time, aviation authorities have published updated interference guidance, reflecting a steep increase in jamming and spoofing incidents over recent years. National mandates and regional rules — such as dual-frequency compliance requirements from major airworthiness authorities — are accelerating retrofit demand and shaping OEM specifications.
For operators and systems integrators, this creates a dual challenge: deploy technology that meets emergent safety and navigation performance standards while also hedging against an increasingly contested signal environment. The commercial implication is that buyers are no longer making decisions based purely on position accuracy metrics; resilience, certification velocity, and integration risk dominate procurement criteria.
Technology and capability trends to watch
-
Resilient PNT architectures — Multi-frequency, multi-constellation receivers paired with inertial measurement systems (GNSS+INS) are now baseline design choices for mission-critical platforms. Anti-jam and anti-spoofing countermeasures, both at the RF front-end and in signal-processing algorithms, are becoming de facto requirements for defense and key commercial applications.
-
Certification and retrofit readiness — Suppliers who can demonstrate certified retrofit pathways (EASA/FAA/CAAC compliance) and offer installation-friendly form factors are gaining faster adoption in the business and general aviation segments.
-
Modularization and OEM ecosystems — There is a divergence between vertically integrated avionics suites and modular OEM receiver suppliers. The former target full-system value capture; the latter focus on high-precision modules and software IP that can be embedded across platforms.
-
Software-defined resilience — Firmware-upgradeable anti-jam/anti-spoofing and the ability to ingest alternative PNT sources (e.g., terrestrial ranging, timing over data links) are strategic differentiators that reduce hardware replacement cycles.
Competitive landscape — what the market structure implies
The market exhibits moderate concentration: the top-three vendors control a meaningful portion of market value, and the top-five capture a clear majority share. This structure favors players who combine certification credentials, breadth across civil and military portfolios, and demonstrable operational deployments.
Key incumbent profiles illustrate the strategic segmentation:
-
Garmin (Schaffhausen) — Strength in certified avionics and retrofit solutions for general aviation and business jets; competitive advantage lies in panel-mount and embedded options that meet FAA/EASA standards and fast aftermarket adoption cycles.
-
Honeywell — Broad avionics integration capability with GNSS receivers and inertial systems for commercial and defense platforms. Honeywell’s value is in aircraft-system integration and lifecycle support at fleet scale.
-
Collins Aerospace (RTX) — Supplier of multi-constellation receivers and integrated navigation products for commercial and military applications, with an emphasis on mission systems and upgrade paths for secure navigation services.
-
Thales — Focused on resilient PNT with certified receivers offering LPV/RNP and anti-jam features; recent product launches underline a push into compact, high-assurance solutions for both crewed and unmanned platforms.
-
Trimble and NovAtel — OEM-grade, high-precision positioning specialists that feed aircraft manufacturers and government programmes where centimeter-level accuracy and SBAS integrity are priority criteria.
-
Defense-focused suppliers (Northrop Grumman, L3Harris, BAE Systems) — Emphasize M-code capable receivers, embedded GPS/INS modernizations, and solutions designed for contested electromagnetic environments.
-
Specialist entrants (Septentrio) — Offer advanced multi-frequency modules with strong anti-jam and anti-spoofing claims targeting a niche of high-precision and high-integrity applications.
Recent product and regulatory developments underscore this dynamic. Strategic deliveries of modernized embedded navigation systems and new anti-jam compact receivers have emerged alongside aviation authority guidance that raises operational reporting and mitigation expectations for interference events. For purchasers, this means vendor selection must account for both product capability and the supplier’s ability to meet evolving regulatory evidence requirements.
Operational and commercial implications — recommended actions for 2026 planners
Leaders must treat receiver procurement as a systems decision that spans policy, operations, and engineering. The following priorities distill the most consequential moves:
-
Prioritize resilient PNT in capital plans — Require demonstrable anti-jam/anti-spoofing performance and GNSS+INS integration capability in procurement specifications. Incorporate certification milestones into supplier contract terms.
-
Diversify supplier risk — Balance incumbents with specialist OEMs to avoid single-source exposure, and require modular interfaces to enable later upgrades without full-system replacement.
-
Accelerate retrofit strategies — For mixed fleets, develop prioritized retrofit roadmaps that align with airworthiness mandates and minimize downtime through staged installation plans and common avionics baselines.
-
Embed scenario planning — Quantify operational exposure to localized interference and plan contingency navigation procedures, pilot training updates, and ATC coordination protocols.
-
Invest in software and data — Allocate R&D to firmware upgradability, anomaly detection, and integration of alternative PNT data feeds to extend product life and reduce hardware refresh costs.
-
Evaluate partnership and M&A plays — Identify technology niches (e.g., front-end anti-jam RF, INS sensor fusion, certified retrofit packaging) that are attractive for bolt-on acquisitions or strategic alliances.
Why PW Consulting’s report is a 2026 boardroom tool
This study translates market projections and technical intelligence into executable plans. Beyond headline growth — the projected market expansion from the 2025 base to 2032 at a 6.75% CAGR — the report delivers templates for procurement, a vendor capability scoring system, regulatory compliance matrices, and tailored scenario analyses. These deliverables are built for executives and functional leads who must justify capital allocations, adjust product roadmaps, and defend resilience investments to boards and auditors.
Importantly, PW Consulting’s approach follows the “need-to-act” principle: highlight where decisions materially affect operational continuity and cost, then provide the tactical tools necessary to execute. For firms that must reconcile fleet modernization with constrained budgets and certification timelines, the report frames the trade-offs and prescribes concrete next steps.
Next steps — how to use the intelligence
-
For procurement teams: use the vendor scorecards and TCO models to short-list suppliers and negotiate milestone-based contracts that link payment to certification and field-proven performance.
-
For product and engineering: adopt the technology roadmap and integration checklists to prioritize firmware modularity and sensor fusion investments that extend platform life.
-
For risk and operations leadership: operationalize the scenario stress-tests to update emergency procedures, ATC coordination, and crew training materials.
-
For investors and corporate strategists: interrogate the market consolidation metrics and M&A templates to identify value-creation targets across OEM modules, avionics integration, and PNT services.
PW Consulting’s full report contains the granular segmentation, regional and application-level forecasts, and detailed vendor market shares that many teams will need to finalize procurement and investment decisions. These datasets and the full suite of practical tools are available in the report’s comprehensive deliverables; PW Consulting can also provide tailored workshops to map the findings to a client’s specific fleet and programme constraints.
For organizations preparing budgets, specification documents, or M&A theses in 2026, this report converts macro momentum into pragmatic action: the growth runway is clear, but the winners will be those who couple technology selection with regulatory foresight and operational resilience.
For detailed analysis of this topic, please visit the official page: Gps And Gnss Receivers In Aviation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com