

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Composite Sandwich Panels to Grow at 7.15% CAGR and Reach USD 8,514.6 Million by 2032

Composite Sandwich Panels Market — 2026 Strategic Outlook and Decision Playbook
Executive summary
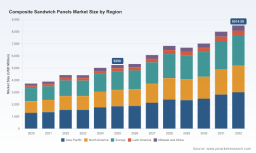
PW Consulting’s latest market study frames composite sandwich panels as a strategic inflection point for building, transport and aerospace OEMs and their suppliers entering 2026. The global market, with a measured progression from approximately USD 3.7 billion in 2020 to USD 5.25 billion in 2025 (base year), is projected to continue expanding at a compound annual growth rate of 7.15% through a 2026–2032 forecast horizon. By 2032 the market is expected to exceed USD 8.5 billion, underscoring a durable recovery and structural growth driven by energy-efficiency mandates, materials innovation and demand for lightweight, fire-rated envelope and structural solutions.
Composite Sandwich Panels Market
This briefing is written as a strategic “trailer”: it samples the report’s analytical depth to establish confidence in our models and conclusions, while deliberately omitting the granular sub-segment tables and region-by-application breakdowns that form the proprietary core of the full PW Consulting deliverable. Executive teams seeking the full dataset, scenario matrices and supplier-level scorecards should refer to the report landing page for access.
Composite Sandwich Panels Market
Why this report matters for 2026 corporate decisions
- CapEx prioritization: Our demand modelling links capital allocation to near-term regulatory timelines for fire and thermal performance. For firms with production decisions on the table in 2026, the report quantifies payback windows under three cost- and demand- scenarios so executives can prioritise expansions, retrofits or brownfield vs greenfield choices.
- M&A and alliance screening: A mid-consolidation market structure (CR3 ~32.5%, CR5 ~44.8%) points to pockets of opportunity for bolt-on acquisitions and technology licensing. The report supplies a prioritized shortlist of technology and capacity targets, with fit-for-purpose valuation multipliers and integration risk flags tailored to strategic buyers.
- Procurement and raw-material risk management: We provide bottom-up cost models that map composite panel BOMs to feedstock price pathways—highlighting sensitivity to polyurethane (PUR) and polyisocyanurate (PIR) foam inputs, petroleum-derived resins and the growing influence of thermoplastic core procurement. These models convert commodity scenarios into margin and pricing levers for OEMs and contractors.
- Product roadmap and certification planning: For product leaders, the report lays out a prioritized certification and product-development calendar, reflecting rising fire-safety and embodied-carbon requirements across major end-markets.
Practical contents you'll find in the full PW Consulting report
- Market-sizing and forecast model (historical 2020–2025; forecast 2026–2032) with interactive scenario toggles for price, regulation and technology adoption.
- Supply-side analytics including a supplier map, capacity-by-technology overlays, and break-even analyses for typical production lines.
- Cost build-ups for core panel configurations and sensitivity outputs to oil-price, resin supply and recycled-polyolefin adoption.
- Regulatory matrix linking regional/market compliance timelines to expected product obsolescence risk.
- Go-to-market playbooks for construction, transportation and aerospace segments, including tender-readiness checklists and sample commercial terms.
- M&A playbook: target screening, valuation yardsticks, due-diligence templates and integration checklists.
- Technology roadmap highlighting where thermoplastic cores, honeycomb innovations and recycled-material integration will create competitive edge.
Competitive landscape: who matters and what to watch
The sector features a mix of global materials players, specialized composites manufacturers and regional panel producers. This hybrid competitive set creates an environment where technical differentiation, scale and regulatory compliance capability determine value capture.
Composite Sandwich Panels Market
- Kingspan Group (Ireland): Market leader behaviorally focused on high-performance insulated panels with advanced core packages and a clear emphasis on thermal efficiency and fire safety for building envelopes.
- Hexcel Corporation (United States): Competitive differentiation in aerospace-grade honeycomb and lightweight structural panels — innovations there set performance benchmarks that cascade into other high-value transport segments.
- The Gill Corporation (United States): Specialist in multi-opening press production and tailored structural panels for aerospace and transportation OEMs.
- ArcelorMittal (Luxembourg): Traditional steel player that competes through metal-faced panel systems engineered for load-bearing, thermal and fire-rated requirements.
- Tata Steel (India) and regional manufacturers such as Assan Panel A.S. and DANA Group: These players combine localized production with portfolio breadth targeted at industrial, commercial and modular construction customers.
- 3A Composites, EconCore, Rock West Composites and advanced custom manufacturers: These suppliers focus on lightweight facings, novel core technologies and thermoplastic honeycomb solutions for architecture, transportation and industrial niches.
Recent vendor-level developments underscore the direction of travel: capacity expansions in Asia for thermoplastic fiberglass panels, new mid-temperature honeycomb cores for aircraft interiors, product launches aimed at high-thermal and load-bearing roofing, and aerospace-focused thermoplastic system certifications. These moves are consistent with a market where technology leadership and compliant product portfolios are prerequisites for winning large-volume contracts.
Materials, technology and regulation — the structural drivers through 2032
Three interconnected trends will shape returns in 2026 and beyond:
- Feedstock volatility and cost pass-through: Foam cores (PUR, PIR) along with petroleum-based resin inputs remain cost drivers; our scenario work translates oil-price shocks into margin erosion timeframes and suggests hedging and supplier diversification strategies. The broader honeycomb market—valued at roughly USD 4.35 billion in 2025—continues to be a major demand sink for the composite sandwich sector.
- Material substitution and circularity: Thermoplastic cores and recycled polyolefins are moving from pilot to production scale in targeted applications. These materials improve recyclability and cost position in high-volume transport and construction use-cases, and we map practical substitution pathways in the report.
- Stringent fire and energy regulations: Tighter fire-safety and thermal-insulation standards are compressing design windows for legacy products and elevating certified materials and tested systems. Successful suppliers are coupling R&D investments with accelerated certification timelines—this is a gating factor for market access.
Opportunities and risks for 2026 strategic plans
- Opportunities: Modular construction, retrofit programs for energy efficiency, and the electrification of transport (where lightweighting reduces energy consumption) create high-growth pockets. Suppliers offering lower embodied-carbon panels or faster on-site installation will command premium positioning.
- Risks: Raw material price spikes, non-aligned regulatory approvals across jurisdictions, and production bottlenecks for advanced core materials can delay revenue recognition. Trade measures and localized content requirements in certain markets also add complexity to global sourcing strategies.
- Mitigants: Our report recommends layered mitigations: flexible BOM designs, forward-purchase and index-linked contracts for critical feedstocks, modular manufacturing setups to accelerate local content compliance, and investment in certification-ready pilot lines to shorten time-to-market.
How commercial and technical teams should use PW Consulting’s findings
Procurement officers can apply our cost models for supplier negotiation and to construct indexed contracts tied to resin and foam benchmarks. R&D and product teams should use the technology-roadmap timelines to sequence certification investments and prioritize thermoplastic integration where lifecycle benefits are highest. Corporate development teams will find the M&A playbook and target prioritization useful for executing roll-up or capability buys within defined valuation bands.
Next steps
PW Consulting’s Composite Sandwich Panels Market report is intentionally structured to move organizations from insight to action. The full report contains the granular segmentation, regional and application breakdowns, supplier scorecards, and downloadable financial models referenced in this briefing. For decision-makers preparing 2026 budgets and strategic roadmaps, the full dataset and scenario tools are the recommended foundation for investments, procurement commitments and M&A diligence.
To obtain the complete report, detailed appendices and proprietary datasets, please visit PW Consulting’s report page or contact our industry practice for a tailored briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Composite Sandwich Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com