

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
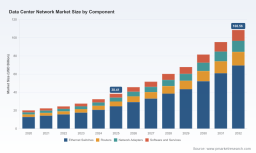
PW Consulting: Data Center Network Market to Rise from USD 38.41 Billion in Base Year 2025 to USD 108.56 Billion by 2032, Fueled by a 15.9% CAGR

Data Center Network Market 2026: Strategic Imperatives for Decision-Makers
PW Consulting’s latest Data Center Network Market report (base year 2025, forecast 2026–2032) is designed for boards, CIOs, infrastructure investors, and procurement leaders needing a concise, practicable intelligence package to make high‑stakes decisions in 2026. The market has shifted from a multi-year hardware refresh cycle into an era defined by AI‑scale interconnects, power constraints, and platform‑level differentiation. Our research synthesizes historical performance with forward scenarios to translate complexity into clear action. Below we present a high‑level preview of the report’s strategic value—deliberately omitting detailed segment tables and vendor shares so that decision‑makers access the full, sourced datasets via our report page.
Data Center Network Market
Executive snapshot
- Market trajectory: The Data Center Network market expanded materially during 2020–2025, rising from USD 20.15 Billion in 2020 to USD 38.41 Billion in 2025. The acceleration is continuing into 2026 with an expected step change as AI workloads penetrate broader deployments.
- Near‑term forecast: Our base forecast projects the market to grow at a compound annual growth rate (CAGR) of 15.9% through the 2026–2032 horizon, reaching USD 108.56 Billion by 2032 under the central scenario.
- Structure and concentration: The market exhibits meaningful concentration—our analysis shows that the top three vendors command a substantial share of revenue, and the top five capture an even larger portion—indicating an environment where strategic vendor selection and risk mitigation are critical.
- Why this matters now: Capital intensity from hyperscalers, regulatory change around power, and new silicon and optics launches are changing both procurement calculus and architecture decisions for 2026.
Why this report matters for 2026 decisions
- AI as the growth vector: Hyperscaler and AI customer investment behavior is the prime near‑term demand driver. Industry CapEx into data center infrastructure surged in the lead‑up to 2025, and large public cloud and AI platform investments materially altered upgrade cadences and density requirements. This report quantifies those dynamics and translates them into procurement and capacity plans.
- Power and interconnection risk: New regulatory arrangements and commercial pledges have reframed who bears incremental grid and generation costs. Simultaneously, operators face multi‑year grid connection queues that force consideration of behind‑the‑meter generation, battery storage, and staged capacity approaches. Our models allow you to stress‑test financials under these constraints.
- Vendor consolidation and differentiated silicon: Rapid introductions of new switch‑chip and DPU families are shifting value from box vendors to silicon and software ecosystems. The convergence of ASIC capability, DPU offload, and optical fabric design requires an integrated vendor and architecture assessment—our vendor scoring matrix and scenario planner operationalize that evaluation.
What the report contains: operational, repeatable outputs
- Market sizing & scenario suite: Annual historical series (2020–2025) and multiple forecast scenarios (2026–2032) with sensitivity to AI workload penetration, capex cycles, and regulatory shocks.
- Investment & procurement playbooks: Practical templates for RFIs/RFPs, TCO calculators, lifecycle cost models (power, cooling, optics), and contract clauses that allocate interconnection and grid upgrade risk.
- Vendor scorecards and decision tree: Independent comparative assessments of hardware, silicon, DPU, and software capabilities; recommended win‑/loss criteria for enterprise, colocation, and hyperscale procurement tracks. (Detailed vendor share tables and segment‑level numbers are available in the full report.)
- Deployment case studies: Real‑world examples of scaled AI fabric deployments, power‑constrained colo expansions, and retrofit programs that reduced TCO and deployment lead times.
- Regulatory impact toolkit: A playbook that converts state and federal policy developments into actionable procurement and siting strategies, including models for behind‑the‑meter investments and battery co‑location economics.
- M&A and partnership diligence: Checklists and valuation adjustments tailored to network‑centric deals and strategic alliances with silicon/optics suppliers.
Competitive landscape: who matters and why
The data center networking ecosystem is evolving into a multi‑layered competitive battleground where silicon, software, and systems integration determine customer outcomes. Leading players exhibit differentiated strengths:
Data Center Network Market
- Cisco Systems, Inc. — Continues to dominate with integrated stacks that combine switch silicon, routing, and fabric software optimized for hyperscale and enterprise requirements. Recent advancements in high‑performance switch chips and routing platforms signal Cisco’s intent to defend scale deployments and AI fabric footprints.
- Arista Networks, Inc. — Focused on high‑speed Ethernet and AI‑optimized fabrics, Arista’s platform strategies emphasize low latency, power efficiency, and operational simplicity for cloud and AI clusters. Its product cadence targets reduced TCO for service providers and hyperscalers.
- Juniper (now integrated with Hewlett Packard Enterprise) — The HPE–Juniper combination positions a stronger integrated edge‑to‑core portfolio, blending Juniper’s routing and switching innovations with HPE’s systems and channel reach—an important strategic consolidation to watch for enterprise adoption cycles.
- NVIDIA Corporation — By bringing high‑performance switching and DPU capabilities together with its GPU leadership, NVIDIA is shaping a new class of AI fabrics where packet processing, telemetry, and application offload are tightly coupled with GPU compute.
- Broadcom Inc. — As a core silicon supplier, Broadcom’s ASIC roadmaps influence the entire vendor ecosystem; network vendors’ competitiveness increasingly depends on how they leverage Broadcom silicon variants and value‑add software.
- Dell Technologies, Huawei, Extreme Networks, Nokia and others — Each brings complementary strengths: integrated IT stacks, regional market penetration, fabric innovation, and optical interconnect capabilities. Competitive differentiation will hinge on software monetization, service delivery, and geographic/regulatory positioning.
Recent product and corporate developments—such as major new silicon launches and the large strategic acquisition activity in 2025–2026—are compressing windows for procurement decisions. Our vendor matrices show how these moves change supplier risk profiles and strategic fit for particular customer segments.
Data Center Network Market
Regulatory and infrastructure dynamics shaping 2026 strategies
- Power and community impact frameworks: Several major cloud and AI companies have publicly committed to covering incremental grid upgrade costs to protect residential ratepayers. This changes the commercial negotiation dynamics for large data center projects and introduces new forms of long‑term contractual exposure and reputational risk.
- Grid connection lead times: Prolonged interconnection queues in primary markets are forcing operators to consider behind‑the‑meter generation, battery storage, and phased buildouts. Our financial models quantify break‑even points for on‑site generation versus extended wait times.
- State‑level cost allocation: Emerging state policies that require large load customers to bear interconnection costs mean that location decisions must be evaluated not only on land and tax incentives, but on foreseeable utility upgrade liabilities.
- Standards and resiliency expectations: With Uptime Institute Tier standards remaining the benchmark for mission‑critical performance, networking architecture choices must align with maintainability and redundancy expectations—especially for Tier III/IV environments.
Top strategic recommendations for 2026
- Adopt a portfolio approach to supplier risk: Combine a primary strategic partner with two specialty providers—one focused on silicon/optics and another on software/DPU capabilities—to avoid lock‑in and exploit rapid innovation cycles.
- Model power and interconnection as first‑order costs: Include multi‑year grid delay scenarios and behind‑the‑meter options in CapEx/OpEx models; treat battery storage as a deployment accelerant, not only a resiliency add‑on.
- Prioritize software and telemetry capabilities: Operationalization and intent‑based networking deliver disproportionate downstream savings for dense AI deployments—ask vendors for measurable OPEX reduction commitments backed by SLAs.
- Leverage staged capacity designs: Where connection permits are uncertain, adopt modular POD architectures that allow incremental density increases and selective silicon upgrades without wholesale rip‑and‑replace.
- Embed regulatory scenarios into site selection: Use our regulatory impact score to quantify state and local policy exposure and fold this into TCO and NPV models used in siting decisions.
How to use PW Consulting’s full report
This article is a strategic trailer that highlights the operational insights and decision tools contained in PW Consulting’s full Data Center Network Market report. The complete publication includes granular vendor share data, regional and end‑user segmentations, downloadable financial models, full vendor scorecards, and the datasets that underpin our scenarios. Those core segment numbers and vendor allocations are deliberately withheld here to ensure you consult the authoritative source for procurement‑grade figures and bespoke modeling templates.
For procurement teams, investors, and technical architects making binding decisions in 2026, the full report converts market dynamics into executable plans—RFx artifacts, supplier due‑diligence protocols, and energy‑aware TCO models that can be applied immediately. Access the full report and the interactive dataset on our website to download the detailed charts, tables, and scenario workbooks that support rapid, defensible decision‑making.
For detailed analysis of this topic, please visit the official page: Data Center Network Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com