

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
How Asia Pacific Dominates the Global MPP Films Market's 5.72% CAGR Path
By pmarketresearch, 2026-09-18
Navigating Strategic Shifts in the Global Metallised Polypropylene Films Market
Market Status and Core Challenges
The global metallised polypropylene films (MPP films) market has transitioned into a phase of steady expansion, underpinned by consistent demand across electrical, packaging, and industrial applications. Revenue grew from approximately $2.75 billion in 2020 to around $3.65 billion by 2025, with a compound annual growth rate of 5.72 percent projected through 2032. This trajectory reflects a market that has successfully navigated recent macroeconomic turbulence while maintaining structural momentum. The expansion is not uniform across all pathways, however, as growth is increasingly shaped by how different industrial sectors absorb cost pressures, adapt to regulatory expectations, and integrate newer manufacturing technologies.
Polypropylene Pp Synthetic Paper Market
Understanding the market today requires acknowledging that scale alone no longer guarantees advantage. The industry operates with a moderately concentrated structure, where a handful of established players command significant share, yet regional manufacturing footprints and application-specific expertise create meaningful differentiation. This concentration presents both stability and vulnerability: established supply relationships and brand recognition provide resilience, but they also raise the bar for new entrants seeking to compete on price or performance alone. At the same time, the market’s breadth spans highly technical capacitor-grade films and broader packaging-grade variants, meaning that competitive positioning depends heavily on which segment a manufacturer prioritizes and how well it aligns with downstream demand patterns.
MCPP Film for Packaging Market
Several converging challenges define the current inflection point. First, raw material volatility has become a persistent operational reality. Polypropylene feedstock pricing has exhibited sharp regional swings, with certain markets experiencing double-digit year-over-year increases driven by tighter supply conditions and fluctuating monomer costs. These movements compress margins for film producers who cannot easily pass costs downstream, particularly in price-sensitive packaging applications. Second, the gap between high-performance technical films and commodity packaging films is widening in terms of required investment. Manufacturers pursuing capacitor-grade or specialized industrial films face higher qualification standards, tighter tolerances, and longer customer validation cycles, while those focused on packaging must contend with intensifying competition from alternative barrier materials and converter-level integration. Third, regulatory and sustainability expectations are reshaping procurement criteria across end-use sectors. Electrical and automotive buyers increasingly prioritize components that support energy efficiency, thermal durability, and extended service life, while food and beverage packaging customers face mounting pressure to balance barrier performance with recyclability and reduced material complexity. These forces are not isolated; they interact to create a market where strategic clarity matters more than ever.
For executives and investors, the core question is no longer whether the market will grow, but where value will accrue as these challenges reshape cost structures, qualification pathways, and competitive dynamics. The companies that navigate this environment most effectively will be those that treat raw material exposure, application specialization, and regulatory alignment as integrated strategic variables rather than separate operational concerns.
Key Drivers of Market Change
The trajectory of the MPP films market is being shaped by a combination of technological advancement, regulatory pressure, demand-side evolution, and shifting supply chain economics. Each driver reinforces the others in ways that create both operational challenges and structural opportunities for well-positioned players.
Innovation in film architecture and metallisation techniques continues to raise the performance ceiling for both capacitor-grade and packaging-grade applications. Advances in vacuum deposition control, layer uniformity, and precision etching have improved dielectric consistency, insulation resistance, and breakdown voltage characteristics, enabling films to meet increasingly demanding specifications in power electronics, lighting, and motor control systems. In packaging, higher barrier uniformity and tighter thickness control support longer shelf life and reduce the need for multi-layer laminates, which appeals to brands seeking simpler material streams. These technical gains are not merely incremental; they expand the addressable use cases for MPP films into applications where alternatives previously held an advantage. The result is a market where performance differentiation is becoming a more reliable route to pricing power than volume alone.
Policy and regulatory environments are exerting a comparable influence, particularly in regions where energy efficiency standards, automotive qualification requirements, and packaging sustainability mandates are tightening in tandem. In the electrical and automotive sectors, stricter qualification frameworks and thermal durability expectations are filtering out lower-specification materials, favouring suppliers that can demonstrate consistent performance under elevated temperatures and prolonged electrical stress. At the same time, packaging regulations that encourage reduced waste, improved recyclability, and lower carbon intensity are pushing converters and brand owners to re-evaluate film choices. When MPP films can deliver required barrier properties with fewer composite layers or support closed-loop packaging design, they gain relevance in tenders and specification updates. Regulatory pressure therefore acts as a filter, rewarding manufacturers that can align product attributes with evolving compliance and procurement criteria.
Demand-side behaviour is shifting in ways that reinforce these technical and regulatory trends. In consumer electronics and automotive electrification, the push toward higher power density, smaller form factors, and more robust energy conversion systems is increasing reliance on reliable dielectric films that can operate reliably in challenging thermal and electrical environments. Renewable energy infrastructure and industrial power utilities are also expanding their requirement for capacitors and insulation materials that support grid stability and long-duration performance. On the packaging side, brand owners are balancing consumer expectations for convenience and shelf life with corporate sustainability commitments, creating demand for films that combine barrier functionality with material efficiency. These demand shifts are not uniform across regions or sectors, but they share a common direction: buyers are placing greater weight on reliability, efficiency, and material optimisation, and they are willing to qualify suppliers that can demonstrate those attributes credibly.
Supply chain and cost structure dynamics complete the picture. Feedstock pricing has become more regionally divergent, with some markets experiencing sharp upward movements while others see more moderate or even temporarily softening trends. These differences influence where production is competitive, how inventory is managed, and which customers face the greatest pressure to absorb cost increases. Manufacturers with integrated operations, flexible sourcing strategies, or the ability to pass through value-based pricing in high-specification applications are better positioned to manage this volatility. Conversely, companies dependent on single-region feedstock or heavily exposed to commodity packaging margins face a more difficult path. In this environment, cost management is increasingly tied to strategic decisions about product mix, geographic footprint, and customer segmentation rather than simple procurement optimization.
Taken together, these drivers suggest a market in which advantage is increasingly defined by the ability to combine technical credibility, regulatory alignment, and resilient cost positioning. Suppliers that treat these elements as interconnected are more likely to capture premium demand and sustain margins through cycles of raw material fluctuation and specification tightening.
Competitive Landscape and Leading Strategies
The competitive landscape in MPP films reflects a blend of regional manufacturing strength, application specialization, and varying degrees of vertical integration. Rather than competing on a single dimension, leading companies are building advantage through focused positioning, whether that means deep expertise in capacitor-grade dielectrics, scale in packaging-grade barrier films, or the ability to serve both high-performance and broader commercial applications with differentiated product lines.
In the capacitor and industrial electronics space, several manufacturers have established strong reputations by concentrating on metallised film quality, electrical consistency, and qualification support. Companies such as Cosmo Films, Anhui Saifu, Nantong Jiangsen Electronic Technology, Steiner Film GmbH, and Anhui Tongfeng Electronics illustrate different models within this segment. Some emphasise broad capacitor-grade portfolios that span lighting, motor run/start, and industrial power applications, while others focus on integrated production that links film manufacturing directly to capacitor assembly or specific bidirectional film outputs. This specialization allows them to respond to technical procurement requirements more effectively, offering variants such as aluminium-zinc, pure aluminium, and slope or RMF configurations that address insulation resistance and breakdown voltage needs. Their strategic value lies in reducing qualification friction for buyers who require predictable dielectric behaviour and documented performance under demanding conditions.
In packaging and broader industrial applications, a different set of players competes on barrier performance, capacity scale, and converter-oriented service. Jindal Films, Toray Plastics, Flex Films, Vibac, and Dunmore each bring distinct strengths, from vacuum-deposited aluminium barrier films designed for long-shelf-life food and beverage products to high-capacity BOPP portfolios and technical metallised substrates for diverse industrial uses. Their differentiation often centres on uniformity, coating and metallising control, and the ability to supply consistent material to downstream converters who require dependable runnability and barrier reliability. In this part of the market, scale and process reliability are critical, but so is the capacity to adapt film specifications to changing packaging architectures and brand-owner requirements.
The recent product activity from major component manufacturers further underscores how competitive advantage is increasingly tied to specification leadership. In 2025, Vishay Intertechnology introduced an AEC-Q200 qualified DC-link metallised polypropylene film capacitor rated for operation up to 125°C with enhanced robustness, targeting automotive, energy, and industrial use. Around the same period, TDK Corporation launched compact double-sided metallised polypropylene film capacitors suited for resonant topologies, and later updated technical specifications for additional series with detailed application and performance data. These moves highlight a broader dynamic: upstream film producers benefit when downstream component makers invest in higher-temperature, higher-voltage, and more tightly qualified solutions, because such products raise the performance baseline and expand demand for consistent, high-specification dielectric films.
Market concentration remains moderate, with the largest players holding meaningful but not dominant share. This structure leaves room for both consolidation and continued differentiation. Consolidation is likely where scale, feedstock access, or geographic reach can strengthen cost resilience, while fragmentation may persist where application-specific know-how, local qualification relationships, or specialised metallisation capabilities create defensible niches. New entrants face a challenging path unless they bring a clear technical or cost advantage, but regional expansion and targeted product launches remain viable strategies for established players seeking to deepen their footprint in high-growth demand areas. The overarching trend is toward a landscape where strategic positioning is defined less by total volume than by the ability to align product performance, qualification support, and supply reliability with the most valuable end-use segments.
Future Trends and Commercial Opportunities
Looking ahead three to five years, the MPP films market is likely to be defined by three interrelated trends. The first is the continued elevation of performance requirements in electrical and automotive applications. As power electronics become denser, operating temperatures rise, and qualification standards tighten, demand for capacitor-grade and DC-link films with proven thermal and electrical durability will expand. This creates opportunity for suppliers that can document high-temperature behaviour, long-term stability, and application-specific performance, particularly where downstream component makers are investing in qualified solutions for electrification and energy infrastructure.
The second trend is a gradual re-weighting of packaging demand toward material efficiency and simpler material streams. Brand owners and converters are under pressure to reduce multi-material complexity while preserving barrier performance and shelf life. Films that can deliver reliable moisture and gas barrier properties with fewer layers, or that integrate well into recycling-oriented design goals, are likely to gain preference in specification updates. This shift favours manufacturers that can balance metallised barrier consistency with flexible formatting and converter-friendly processing, especially in segments where shelf-life requirements remain stringent.
The third trend is regional cost divergence becoming a more persistent strategic variable. Because feedstock and monomer costs are moving differently across geographies, competitive positioning will increasingly depend on where capacity is located, how sourcing is managed, and which customer segments can absorb price movement through value-based differentiation. Manufacturers with diversified geographic exposure or the ability to shift product mix toward higher-specification, less price-elastic applications will be better insulated from regional volatility. At the same time, buyers in sensitive segments will continue to seek supply partners who offer predictable pricing frameworks and resilient availability.
These trends point to clear commercial opportunities, but they also carry risk. Overexposure to commodity packaging margins in a volatile cost environment can erode profitability, while over-concentration in a single application may leave a company vulnerable if qualification cycles lengthen or competing materials improve. There is also uncertainty around how quickly sustainability mandates translate into material substitution in packaging, and whether new capacitor technologies or alternative dielectrics eventually pressure certain MPP use cases. The most resilient strategies will be those that treat these uncertainties as inputs to portfolio design rather than as reasons to defer investment.
Strategic Recommendations for Decision-Makers
Manufacturers should use the current environment to sharpen product mix strategy. Prioritising segments where performance, qualification, and reliability command pricing power can reduce exposure to commodity margin pressure, while targeted investment in metallisation precision and high-temperature film consistency can strengthen position in electrical and automotive demand pools. Supply chain flexibility, including diversified feedstock sourcing and geographic balancing, remains essential to managing regional cost volatility without sacrificing service reliability.
PW Consulting
Investors should evaluate opportunities based on company positioning within application-specific value chains rather than headline scale alone. Assets and businesses that serve qualified capacitor, power electronics, or higher-barrier packaging applications are more likely to capture durable demand than undifferentiated commodity producers. It is equally important to assess whether a target’s cost structure and geographic footprint can withstand continued raw material divergence, and whether its product roadmap aligns with tightening qualification and sustainability expectations.
Procurement and supply chain leaders should treat film sourcing as a strategic specification decision, not just a cost exercise. Mapping suppliers by technical capability, qualification support, and regional cost resilience can improve both performance security and long-term pricing stability. Building multi-supplier strategies for critical applications, while consolidating volume where a single supplier offers clear technical or service advantage, can help balance risk and efficiency.
For organisations seeking a deeper view of segment-level demand patterns, regional dynamics, and company-specific positioning, the full PW Consulting market analysis provides a more granular foundation for planning. The complete report expands on the trends outlined here with detailed segmentation data, competitive profiles, and scenario-based insight designed to support investment, sourcing, and product strategy decisions across the MPP films value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Metallised Polypropylene Films (MPP Films) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Hot Tapping Machines Market: The Real Drivers Behind 4.7% CAGR Growth
By pmarketresearch, 2026-09-18
Hot Tapping Machines Market: Strategic Trends, Commercial Opportunities, and the Path Forward
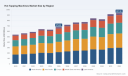
The global hot tapping machines market has settled into a steady growth trajectory, anchored by recurring pipeline intervention needs across energy and industrial sectors. Valued at approximately USD 679.66 million in 2025, the market expanded from around USD 540.21 million in 2020 and is projected to reach roughly USD 937.39 million by 2032, translating to a compound annual growth rate of about 4.7%. This pace reflects a sector that is neither in a speculative boom nor in contraction, but rather in a mature, reliability-driven expansion where incremental gains are earned through operational resilience, compliance, and targeted innovation. The growth is broad-based, spanning multiple product types and application verticals, yet underlying segments show distinct velocity and margin profiles that shape where value is created. A glance at the revenue mix clarifies the competitive battlefield: hydraulic machines command the largest revenue pool, followed by pneumatic systems, with manual and electric variants occupying niche but strategically important positions. Application demand is similarly distributed, with oil and gas pipelines representing the most substantial revenue contributor, while water and wastewater treatment, chemical and industrial processing, and power generation plants collectively sustain a diversified demand base.
Framing the market solely by size, however, obscures the operational realities that determine winners and laggards. The sector is navigating a series of inflection points that test supply resilience, technical sophistication, and commercial agility. First, demand is increasingly defined by in-service continuity. Utilities, energy operators, and industrial plants are reluctant to accept full shutdowns for routine maintenance, branch connections, or emergency repairs, which elevates the strategic importance of equipment that can operate safely under pressure and varying flow conditions. Second, the cost of downtime has become a dominant economic variable. In tightly coupled supply chains and constrained labor markets, a single unplanned outage can cascade into production losses, contract penalties, and reputational damage. Third, regulatory and standards expectations continue to raise the technical bar. Operators and contractors must align procedures with widely referenced safety and design guidelines, which increases the importance of documented process control, material integrity, and operator training. Fourth, raw material specifications matter more than ever. Equipment constructed from pressure vessel–grade materials, with impact toughness at sub-zero temperatures and resistance to sulfide stress cracking, is increasingly favored in demanding service environments. These dynamics are reshaping procurement criteria, pricing power, and service expectations across the value chain.
For executives and investors, the practical implication is that market growth is not a simple function of new capital deployment. The most actionable opportunities lie in reducing total cost of intervention, improving uptime assurance, and aligning product capabilities with evolving compliance expectations. Companies that can demonstrate repeatable performance in live systems, shorten mobilization time, and support diverse pipe materials and pressure classes are better positioned to capture share in a fragmented but increasingly demanding market.
Key Drivers Reshaping the Hot Tapping Machines Market
Technical Capability as the New Differentiator
Innovation in hot tapping is moving beyond mechanical capacity toward integrated performance. The industry is seeing a push toward machines that handle a wider range of pipe diameters, wall thicknesses, and operating pressures without compromising alignment, seal integrity, or cut quality. Proprietary cutter and drive designs, double block and bleed sealing arrangements, and purpose-built accessories are increasingly central to competitive positioning. High-pressure capability is particularly significant in complex service environments, where operators require equipment that can tolerate sour gas conditions, subsea or offshore constraints, and challenging metallurgical profiles. In parallel, there is growing interest in systems that simplify setup and reduce operator dependence, enabling faster mobilization and more consistent outcomes in the field. These capabilities matter because they directly influence whether a contractor can accept a job, how long it takes to complete, and how much risk is transferred back to the asset owner.
Tamping Machine Market
The practical effect is a shift in purchasing logic. Buyers are less focused on unit price alone and more attentive to total intervention cost, including preparation time, tooling availability, spare parts access, and post-operation support. Manufacturers that can package equipment with clear operating envelopes, robust material specifications, and documented procedure support are gaining credibility in segments where failure tolerance is low. This is especially visible in applications where pipelines remain in service during branch connections or line stops, since even minor deviations can create operational or safety exposure.
Regulatory Expectations and Standards Alignment
Standards and guidance documents continue to shape both procurement and field practice. Widely referenced safety and design frameworks provide structured expectations for welding and hot tapping on equipment in service, while pressure equipment and pipeline design codes influence the technical envelope within which machines must operate. Compliance is not merely a procedural formality; it affects liability, insurability, and contractor qualification. As a result, suppliers that can demonstrate alignment with recognized engineering expectations and provide documentation that supports safe execution are better positioned to win work in regulated markets.
This regulatory backdrop also influences product design. Equipment intended for demanding service environments increasingly requires materials and fabrication practices that address sub-zero impact toughness, corrosion resistance, and resistance to sulfide stress cracking. These requirements elevate the importance of supply chain control, quality assurance, and traceability. For operators, the implication is that machine selection is increasingly a risk management decision. For manufacturers, it creates a premium on consistency, certification readiness, and transparent documentation.
Demand-Side Shifts Toward Continuity and Resilience
A structural change in operator behavior is reinforcing demand for in-service connection and repair solutions. Many organizations are prioritizing continuity over the simplicity of a shutdown, particularly where interruptions would disrupt downstream operations, customer commitments, or critical infrastructure services. This shift is visible across multiple verticals, including water distribution, industrial processing, and energy transport. In water systems, for example, there is sustained interest in under-pressure connection methods that allow branch installation without service interruption. In industrial and energy contexts, the emphasis is on minimizing exposure to process upsets while maintaining throughput.
This demand pattern changes the commercial equation. It rewards equipment that is versatile across pipe materials such as steel, copper, brass, and aluminum, and across pressure classes. It also favors suppliers who can support both planned maintenance and urgent response scenarios. From a market perspective, this broadens the addressable opportunity beyond large-scale energy projects into municipal, industrial, and distributed infrastructure work, where frequency of intervention may be higher even if individual project sizes are smaller.
Supply Chain, Cost Structure, and Manufacturing Concentration
Cost dynamics in the hot tapping market are being reshaped by material input requirements, fabrication complexity, and the concentration of manufacturing capability. The top three competitors account for a meaningful share of revenue, and the top five collectively represent more than half of market output. This level of concentration suggests that scale, engineering depth, and established service relationships confer real advantages, particularly in high-stakes applications. At the same time, the presence of specialized manufacturers and regional suppliers ensures that niche requirements, faster turnaround, and application-specific configurations remain viable competitive positions.
Investment in in-house manufacturing capacity is one sign of how companies are responding to these pressures. Strengthening machine shop capability allows suppliers to reduce dependency on external fabrication, improve lead-time predictability, and maintain tighter control over critical components. In an environment where equipment specifications are demanding and downtime costs are high, predictability in production and support can be as valuable as the machine itself. Cost structures are therefore not only about material prices; they are about the ability to deliver repeatable quality, maintain inventory of key parts, and respond to customized requests without excessive premium pricing.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field in hot tapping machines is diverse, spanning established global specialists, regional manufacturers, and equipment providers that serve narrower application sets. Leadership is not uniformly defined by portfolio breadth; it is increasingly defined by the ability to match machine capability with service requirements, demonstrate reliability in live systems, and support customers through installation, operation, and maintenance. Several firms have built recognizable positions by emphasizing either high-pressure performance, application specialization, or broad coverage across pipe sizes and materials.
One cluster of competitors has focused on comprehensive hot tapping capability for live pipeline connections across a wide diameter and pressure range, including onshore and offshore use. This type of positioning appeals to operators who need a single supplier relationship for multiple project conditions. The strategic advantage here is versatility, supported by a portfolio that spans smaller branch connections and much larger interventions. Another group has built its differentiation around proprietary high-pressure machines with sealing architectures designed for demanding service environments, including sour service and subsea-related applications. In this segment, credibility is tied to documented performance envelopes and the ability to manage risk in challenging conditions. A third group serves water and municipal applications with equipment optimized for under-pressure connections and live service insertion. These companies often compete on long experience, ease of use, and familiarity with local utility practices. A fourth group addresses smaller diameter or lower-pressure needs, including hand-operated or specialized systems for active lines. These offerings may not dominate headline revenue, but they can be strategically important where speed, simplicity, and accessibility matter more than maximum operating pressure.
Differentiation Paths and Commercial Logic
Across these positions, several common success factors emerge. The first is technical clarity. Suppliers that define operating envelopes precisely, specify compatible pipe materials and pressure ranges, and provide accessories that reduce field complexity tend to earn stronger customer confidence. The second is service integration. Hot tapping is not purely an equipment sale; it often involves procedure support, training, spare parts availability, and rapid response when field conditions change. Companies that treat support as part of the core offering can command better retention and more predictable demand. The third is manufacturing discipline. Recent investments in advanced machine tools by established players reflect an intent to control critical production steps internally, which can improve consistency and reduce dependence on external sources for key components. Such moves are especially meaningful when equipment must meet stringent material and performance expectations.
How the Landscape Is Evolving
The market structure appears likely to remain moderately fragmented while rewarding scale in the upper end of the pressure and diameter spectrum. Consolidation may continue where companies seek broader application coverage, stronger service networks, or deeper manufacturing capability. At the same time, the presence of specialized and regional players is likely to persist because many projects have localized requirements, specific material constraints, or limited scope that favors agile suppliers over large portfolios. New entrants face a meaningful barrier in credibility, documentation, and field validation, but they can still gain traction by targeting underserved size ranges, particular materials, or specific application workflows. In parallel, industry events and technical exchanges continue to accelerate the spread of best practices, especially around repair methods, in-service welding considerations, and safe intervention procedures. These forums matter because they influence operator expectations and elevate the importance of demonstrable competence over generic capability claims.
Forward Outlook: Trends and Opportunity Windows for 2026–2032
The next several years are likely to be shaped by a combination of steady demand growth and selective performance upgrades. One clear direction is the continued emphasis on in-service operations. As operators weigh the cost of shutdowns against the complexity of live interventions, equipment that enables safe branch connections and line stops without service interruption will remain central. This favors designs that improve alignment control, sealing reliability, and adaptability across pipe types. A second direction is the expansion of application coverage in water, wastewater, and industrial processing. While energy pipelines remain a major revenue pillar, diversified infrastructure spending and the need to maintain existing systems create repeated intervention opportunities in other verticals. A third direction is increasing attention to material integrity and compliance documentation. As expectations around pressure equipment, pipeline design, and safe field practice remain elevated, suppliers will be rewarded for transparent specifications and repeatable quality.
These trends create several commercial opportunity windows. For manufacturers, there is room to strengthen high-pressure and specialty portfolios while also improving accessibility for smaller-diameter or lower-pressure applications where demand frequency can be high. For equipment distributors and service providers, the value lies in combining suitable machines with procedure support, training, and rapid parts availability, since field outcomes depend on more than hardware alone. For investors, the more attractive exposure is likely to be in companies that can demonstrate consistent execution, controlled manufacturing, and the ability to serve regulated or high-risk applications where failure is costly. At the same time, uncertainty remains. Demand can shift with project cycles, maintenance budgets, and macroeconomic conditions. Raw material and fabrication costs may compress margins if not managed carefully. And competitive pressure can intensify where products become more comparable, especially in commoditized size and pressure ranges. The net effect is that growth will likely continue, but profitability and market share will be determined by execution quality rather than market tailwinds alone.
Actionable Implications for Decision-Makers
For manufacturers and equipment suppliers, the strategic priority is to align product capability with the economics of uptime. That means sharpening the definition of operating envelopes, investing in manufacturing control for critical components, and treating documentation and support as core commercial assets. Companies that can reduce setup complexity, improve reliability across materials, and shorten mobilization timelines will be better positioned to compete in both planned and urgent intervention scenarios. It also pays to evaluate where portfolio breadth genuinely adds value and where focused specialization can protect margin.
For investors and strategic planners, the key is to look beyond headline market size and assess where value is being retained. Attention should be given to suppliers with credible high-pressure or specialty positions, disciplined production capabilities, and service models that reduce customer risk. Portfolio exposure should be evaluated against demand diversification across oil and gas, water and wastewater, chemical and industrial processing, and power generation, since segment mix influences both growth resilience and sensitivity to project cycles. In a market where the top five competitors hold a majority share, scale advantages are real, but differentiated application expertise can still create durable niches.
For procurement teams and end users, machine selection should be evaluated through a total-intervention lens. The relevant questions include how well the equipment matches pipe material and pressure class, how quickly it can be deployed, how restrictive its documentation and compliance support are, and whether spare parts and field support are available when conditions change. Buying on unit price alone can understate operational risk and long-cycle cost. Selecting equipment that aligns with service conditions and support expectations typically reduces exposure to delays, rework, and downtime-related losses.
For decision-makers who need precise segmentation, regional demand patterns, product-type breakdowns, application-level revenue detail, and competitive benchmarking, a comprehensive market study can provide the granularity required for planning and investment judgment. A full research report can also support scenario analysis around pricing, capacity investments, and entry strategy across different application verticals and geographic markets.
Worldwide Single Axis Automatic Tapping Machine Market
For detailed analysis of this topic, please visit the official page: Worldwide Hot Tapping Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Diethyl Chlorophosphate Market: Why 5.03% CAGR and Asia Pacific’s 94M Shift Redefine Growth
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Diethyl Chlorophosphate Market
The global diethyl chlorophosphate market has evolved into a specialized yet strategically vital segment within the broader organophosphorus chemicals landscape. Valued at approximately USD 205.0 million in 2025, the market reflects a compound annual growth rate of 5.03 percent from 2020 through 2032, translating into a projected valuation of nearly USD 289.0 million by the end of the forecast period. This trajectory indicates steady expansion rather than speculative volatility, underpinned by sustained demand across chemical synthesis, flame retardant manufacturing, and agrochemical production. The market has demonstrated resilience through recent macroeconomic fluctuations, with 2024 recording a notable recovery to USD 196.6 million following a temporary contraction in 2023. Such patterns underscore an industry that is structurally anchored yet sensitive to input cost dynamics, regulatory shifts, and regional demand reallocation.
Despite this steady upward course, the sector confronts several structural friction points that will shape competitive positioning and investment priorities. First, the classification of diethyl chlorophosphate as a hazardous material under international transport frameworks introduces compliance complexity that disproportionately affects smaller manufacturers and cross-border traders. Logistics constraints, labeling requirements, and carrier restrictions elevate operational overhead and can delay time-sensitive deliveries to downstream formulators. Second, the market remains moderately concentrated, with the top three players capturing roughly 35 percent of global revenue and the top five accounting for just over half. This distribution leaves substantial headroom for fragmentation, yet it also means that scale advantages in procurement, purification, and regulatory documentation are increasingly decisive. Third, the industry is navigating a transitional phase in feedstock economics, where volatility in primary intermediary pricing has compelled producers to recalibrate margin structures and explore cost-pass-through mechanisms without alienating price-sensitive buyers.
Key Challenges at an Inflection Point
The intersection of regulatory scrutiny and supply chain recalibration has created an inflection point for market participants. Companies that once relied on incremental capacity additions and standardized distribution models are now compelled to rethink how they manage hazard compliance, quality consistency, and customer segmentation. The pressure is particularly acute in regions where transportation infrastructure is undergoing upgrades or where environmental enforcement is becoming more stringent. At the same time, downstream buyers are demanding greater transparency regarding material sourcing, batch consistency, and safety documentation. These expectations are reshaping procurement criteria and elevating the importance of supplier reliability over pure price competition. For executives evaluating exposure to this segment, the immediate question is not whether growth will continue, but which operational and strategic capabilities will determine who captures the most profitable share of that growth.
Key Drivers Shaping Market Trajectory
The expansion of the diethyl chlorophosphate market is being pulled forward by a convergence of technological, regulatory, and demand-side forces. Understanding these drivers requires looking beyond headline growth figures and examining the operational and commercial mechanisms that convert industry momentum into tangible value creation.
Technological Innovation and Process Refinement
Advancements in synthesis pathways and purification techniques are steadily improving the cost-efficiency and quality consistency of diethyl chlorophosphate production. Manufacturers are investing in optimized chlorination and esterification processes that reduce impurity profiles, particularly for applications requiring high-purity grades. In research and specialty chemical contexts, tighter control over moisture content and byproduct formation has become a differentiator, enabling suppliers to serve demanding applications in pharmaceutical intermediate synthesis and fine chemical production with greater reliability. These process improvements are not merely incremental; they are reshaping the value proposition of the high-purity segment by lowering rejection rates, reducing batch-to-batch variability, and expanding the range of downstream reactions that can be supported with confidence. As a result, suppliers that can demonstrate reproducible purity levels and robust analytical documentation are gaining preference in procurement decisions where performance consistency outweighs marginal price differences.
PW Consulting
Regulatory and Compliance Evolution
The regulatory environment continues to act as both a constraint and a competitive filter. Diethyl chlorophosphate is classified as a hazardous substance under international transport codes, requiring specific labeling, packaging, and carrier coordination in line with Department of Transportation and IATA standards. This classification is not merely a logistical footnote; it influences sourcing decisions, inventory positioning, and the economics of cross-border distribution. In parallel, European Union registration requirements under REACH impose additional obligations for volumes exceeding one tonne per year, with ongoing safety assessments evaluating reprotoxic classification potential. These requirements elevate the compliance burden for manufacturers and distributors operating in or supplying into Europe, but they also create a barrier that favors organizations with established regulatory expertise and document management capabilities. The practical effect is a market where compliance readiness increasingly functions as a strategic asset, enabling better-positioned players to secure long-term supply agreements and expand into regulated end markets with fewer friction points.
Demand-Side Shifts and Application Breadth
On the demand side, end-use industries are driving sustained consumption through both volume growth and application diversification. Agrochemical synthesis remains the largest application channel, reflecting the ongoing need for organophosphorus building blocks in crop protection and specialty pesticide formulations. This segment benefits from structural agricultural demand and the continued modernization of pest management portfolios in multiple regions. Flame retardant manufacturing represents another significant demand pillar, as materials used in electronics, construction, and transportation increasingly require halogen-free or lower-hazard fire resistance solutions. Diethyl chlorophosphate serves as a functional intermediate in certain formulations, linking its consumption to broader materials innovation cycles. Pharmaceutical and fine chemical intermediates, while smaller in aggregate volume, contribute disproportionately to margin profiles because these applications typically require higher purity, stricter documentation, and more responsive technical support. The cumulative effect is a demand base that is broad enough to buffer sector-specific downturns while offering multiple pathways for value creation.
Tris (Clorisopropyl) Phosphate Market
Supply Chain and Cost Structure Dynamics
Supply chain conditions have emerged as a decisive factor in shaping market economics. Feedstock availability and pricing, particularly for phosphorus oxychloride, directly influence production costs and margin resilience. Early 2024 saw a notable increase in intermediary pricing driven by supply chain disruptions in China, a shift that rippled through procurement cycles and prompted manufacturers to reassess inventory strategies. Some producers responded by securing longer-term supply agreements, diversifying source origins, or adjusting product mix toward grades with stronger margin characteristics. The broader lesson is that cost structure flexibility is becoming a competitive requirement rather than an optional optimization. Companies that can dynamically manage input exposure, maintain buffer inventory where justified, and communicate transparent cost drivers to customers are better positioned to preserve profitability during periods of input volatility. Conversely, rigid cost models and single-source dependencies increase vulnerability to regional disruptions and price shocks.
Competitive Landscape and Leading Strategies
The competitive structure of the diethyl chlorophosphate market reflects a blend of established specialty chemical suppliers and regional manufacturers with focused application expertise. Rather than a race to the bottom on price, the leading players are competing on reliability, technical support, purity assurance, and the ability to navigate evolving compliance requirements.
Differentiation Among Key Participants
Several companies have carved out recognizable strategic positions based on their product orientation and end-market focus. Major reagent and research chemical suppliers emphasize high-purity offerings for organic synthesis, phosphorylation reactions, and laboratory-scale applications. Their value proposition centers on consistent batch quality, comprehensive safety documentation, and accessibility for research and development teams. These players often benefit from broad catalog reach, global distribution networks, and strong brand recognition in scientific procurement channels. In contrast, manufacturers oriented toward industrial and agrochemical applications prioritize scale, export capability, and the ability to supply intermediates in volumes that support sustained downstream production. Their differentiation often lies in manufacturing flexibility, the capacity to serve organophosphorus compound supply chains, and responsiveness to bulk procurement requirements. A third group of specialty chemical producers focuses on fine chemical synthesis and pharmaceutical intermediate pathways, where technical service, purification consistency, and regulatory alignment with research-grade expectations matter more than sheer throughput.
Dicalcium Phosphate Market
Strategic Positioning and Competitive Advantages
The most effective competitive strategies in this market combine product-grade focus with operational discipline. High-purity suppliers gain advantage by reducing customer risk in sensitive applications, backing their products with analytical data, and maintaining inventory availability for time-sensitive research and pilot-scale demand. Industrial-focused producers compete by stabilizing supply, managing feedstock exposure, and offering dependable logistics even under hazardous-material transport constraints. Across both models, an increasingly important advantage is regulatory fluency. Suppliers that can anticipate compliance obligations, prepare necessary registration and safety documentation, and communicate transport requirements clearly reduce friction for buyers and strengthen long-term supply relationships. Another differentiating factor is customer segmentation discipline. Companies that align grade offerings, documentation depth, and service levels with specific application needs tend to protect margins more effectively than those pursuing undifferentiated volume growth.
Market Structure Evolution
The market structure appears poised for selective consolidation and parallel specialization. Moderate concentration leaves room for new entrants and regional expansion, particularly where demand growth outpaces local supply or where import dependence creates opportunities for domestic production. At the same time, the compliance, logistics, and quality assurance demands of the sector favor players with established infrastructure and process maturity. Over time, this dynamic is likely to encourage partnership models, capacity alignment with key downstream users, and gradual consolidation among smaller suppliers that lack the scale or capability to keep pace with regulatory and cost pressures. New entrants will need a clearly defined angle, whether through niche purity standards, regional supply reliability, or application-specific technical support, rather than competing purely on availability. The broader trend is toward a more segmented market in which competitive success depends on matching the right grade, the right compliance posture, and the right service model to the right end-use segment.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to shape how value is created and captured in the diethyl chlorophosphate market. These trends are not isolated developments; they interact with one another and will influence both opportunity selection and risk management.
Continued Growth with Graded Maturity
Market expansion is expected to remain positive, but the pace and composition of growth will likely diverge by segment and region. High-purity applications may continue to command stronger margins as research, fine chemical, and specialized intermediate demand grows more exacting. Industrial and agrochemical channels will still contribute substantial volume, but their profitability will depend more heavily on cost management, feedstock stability, and logistics efficiency. For commercial leaders, this implies that strategy should be calibrated by grade and application rather than treating the market as a single growth pool. The most resilient portfolios will likely combine reliable volume sources with higher-value specialty positions that benefit from stricter quality and documentation requirements.
Regulatory and Transport Compliance as a Strategic Lever
Compliance expectations are likely to intensify rather than plateau. Transport classification, labeling discipline, and regional registration processes are already shaping purchasing behavior, and this influence should deepen as enforcement becomes more consistent and documentation expectations rise. Organizations that proactively invest in compliance infrastructure, standardize safety and transport documentation, and monitor regulatory signals will be better equipped to expand into regulated channels and maintain supply continuity. The commercial opportunity here lies in reducing buyer friction: when a supplier can streamline compliance-related overhead for customers, it becomes a preferred partner in procurement decisions where reliability and risk management matter. The risk is equally clear. Operators that treat compliance as a reactive administrative task may face increasing delays, restricted market access, and customer attrition as buyers shift toward partners with stronger readiness.
Feedstock Volatility and Supply Chain Resilience
Input cost dynamics will remain a central theme. Intermediary pricing sensitivity, regional supply disruptions, and logistics constraints can quickly alter margin outlooks. The trend is pushing the market toward greater supply chain resilience through diversified sourcing, inventory planning that balances carrying costs against disruption risk, and closer coordination with downstream users to anticipate demand swings. Companies that build flexibility into procurement and production planning will be more capable of protecting margins while maintaining service levels. At the same time, the market may see increased interest in regional supply hubs and localized distribution strategies to reduce exposure to long-haul hazardous transport constraints and cross-border regulatory variation. The uncertainty lies in how quickly feedstock markets rebalance after disruptions and whether regional production capacity expands fast enough to absorb demand shifts without creating new bottlenecks.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align grade strategies with the realities of cost structure and compliance readiness. High-purity lines should be supported by robust analytical control and documentation that justifies premium positioning, while industrial-grade operations should focus on feedstock diversification, logistics reliability, and disciplined inventory management. Companies that define their target applications clearly and avoid overextending into segments where they lack technical or regulatory capability are more likely to protect margins and build durable customer relationships.
For investors, the most attractive exposure may not come from undifferentiated volume plays but from operators that combine application focus with compliance strength and supply chain flexibility. Due diligence should assess feedstock exposure, hazardous-material logistics capability, regional regulatory readiness, and the extent to which a company’s product mix aligns with stable or growing end-use channels. Capabilities that reduce customer friction in regulated environments often translate into stronger retention and pricing power over time.
For procurement and sourcing leaders, supplier selection should extend beyond unit price to include batch consistency, documentation quality, transport compliance, and responsiveness under disruption. Long-term agreements can be valuable when paired with suppliers that demonstrate process maturity and regulatory alignment, particularly where production continuity and safety assurance are critical to downstream operations. Ongoing visibility into regional demand shifts, feedstock movements, and regulatory developments will help sourcing teams adjust specifications and inventory posture before disruptions cascade into operational risk. Detailed market intelligence that tracks these signals at a segment and regional level can materially improve planning accuracy and partnership decisions.
For decision-makers seeking a deeper view of segment-level demand structure, regional dynamics, and company-specific positioning, the full PW Consulting market research report provides the supporting detail needed to translate these strategic themes into actionable plans. The complete analysis offers a more granular breakdown of market size trajectories, segmentation intensity, and competitive moves that can inform capacity allocation, sourcing strategy, and investment prioritization with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide Diethyl Chlorophosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Main-Chain Liquid Crystalline Polymer Market: How a 7.42% CAGR Reshapes Strategy Through 2032
By pmarketresearch, 2026-09-18
Main-Chain Liquid Crystalline Polymer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Structural Challenges
The main-chain liquid crystalline polymer (LCP) market has established itself as a critical enabler for high-performance engineering applications, driven by an unambiguous demand trajectory. Revenue expanded from approximately $1,024 million in 2020 to $1,466 million in 2025, and forward projections indicate sustained momentum toward $2,420 million by 2032. This trajectory translates to a compound annual growth rate of 7.42 percent across the 2026 to 2032 forecast horizon, reflecting a market that is no longer niche but structurally embedded in advanced manufacturing ecosystems. Growth is not evenly distributed across applications or geographies, yet the underlying expansion is anchored by sectors where dimensional stability, thermal resilience, and flow characteristics during precision molding are non-negotiable.
Despite the positive macro trajectory, the industry confronts several structural friction points that will define competitive positioning in the coming years. First, supply chain fragility around specialty monomers creates persistent cost and availability volatility. Purified terephthalic acid and hydroxybenzoate derivatives, which form the backbone of main-chain LCP chemistry, operate within constrained global supply networks. Limited supplier concentration, coupled with batch polymerization requirements, means producers cannot easily decouple from raw material price swings or logistical bottlenecks. This structural premium, often trading at roughly double the cost of high-temperature nylons, limits aggressive substitution in cost-sensitive applications while simultaneously reinforcing the material's value proposition where performance justifies expense.
Second, the regulatory environment is lengthening qualification cycles and raising compliance overhead. Updated chemical safety review frameworks in major markets, alongside evolving disclosure expectations under prevailing chemical strategies, require more extensive testing, traceability documentation, and lifecycle transparency for new LCP grades. These requirements are not peripheral; they directly impact time-to-market for formulation adjustments, additive packages, and biologically balanced variants. For high-volume electronics and mobility customers operating on tight product launch schedules, extended qualification timelines create planning uncertainty and can delay adoption even when technical performance is compelling.
Liquid Crystal Polymers (LCPs) Market
Third, the market is transitioning from performance-driven acceptance to sustainability-conditioned procurement. Original equipment manufacturers and tier suppliers increasingly expect certified green feedstocks, mass-balance traceability, and circular chemistry options alongside thermal and mechanical specifications. This shift does not eliminate demand for conventional main-chain LCPs, but it reshapes purchasing criteria and rewards producers who integrate environmental credentials into product architecture rather than treating them as aftermarket messaging. The convergence of raw material constraints, regulatory elongation, and sustainability-conditioned demand creates a market where scale alone is insufficient. Competitive advantage is migrating toward formulation agility, feedstock diversification, and qualification speed.
Key Drivers Shaping Market Trajectory
Technical Innovation and Formulation Breakthroughs
Material science progress remains the most direct catalyst for expanded LCP adoption. Recent chemistry refinements have focused on balancing high-heat resistance, flame retardancy, and injection flow without sacrificing dimensional tolerances. For high-frequency electronics, 5G infrastructure, and electric vehicle power management, formulators have engineered grades that maintain signal integrity and thermal stability while enabling thinner wall sections and higher component density. The ability to tailor monomer ratios, modify end-group terminations, and integrate specialty additives without disrupting liquid crystalline ordering has extended LCP relevance into applications that previously relied on metal substitution or lower-performance thermoplastics.
A notable example of formulation direction is the introduction of biomass-balanced grades that preserve performance while addressing procurement decarbonization requirements. By applying mass-balance accounting to bio-derived feedstocks, producers have delivered LCP variants that maintain thermal and mechanical characteristics while providing a credible pathway for customers seeking scope reductions in their supply chain emissions. This development signals a broader shift: sustainability is increasingly being engineered into polymer architecture rather than layered on through end-of-life messaging alone.
Policy and Regulatory Environment
Regulatory frameworks are actively reshaping how LCP grades are developed, qualified, and deployed. Chemicals legislation in major jurisdictions continues to tighten testing protocols, disclosure expectations, and substance evaluation timelines. For LCP producers, this means new grades and modified formulations face longer qualification cycles, and customers require more visible documentation around chemical safety, traceability, and compliance status. The operational effect is twofold: it raises barriers to rapid product churn and rewards companies with mature regulatory infrastructure, standardized testing data packages, and established customer qualification relationships.
Simultaneously, policy emphasis on safer chemistries and circular solutions is altering feedstock preferences. Procurement teams increasingly weigh certified feedstocks, mass-balance traceability, and lower-impact sourcing as material selection criteria, particularly in automotive, electronics, and medical supply chains. This environment favors producers that can deliver both performance assurance and verifiable sustainability credentials, while it pressures laggards who must retrofit compliance or feedstock strategy after product architecture decisions are already locked.
Liquid Crystal Polymer (LCP) Films and Laminates Market
Demand-Side Evolution in Key End-Use Markets
Demand is shifting not only in magnitude but in specification. Electrical and electronics applications continue to anchor volume, driven by miniaturization, high-speed data transmission, and thermal management requirements in consumer devices, network infrastructure, and advanced driver-assistance systems. Automotive demand is growing as electrification expands the need for lightweight, heat-resistant, and dimensionally stable components in battery-related assemblies, charging systems, and under-hood modules. Aerospace and defense applications reinforce the market's high-performance core, where strict qualification standards and long service-life expectations reward materials that deliver consistent behavior under extreme thermal and mechanical stress.
Industrial and medical applications add a different growth pattern: lower volume per grade but higher specification precision, especially in semiconductor processing equipment, medical device components, and precision instrumentation. Across these segments, purchasing decisions are becoming more integrated. Procurement, engineering, and sustainability teams increasingly evaluate LCP grades against a combined scorecard of thermal performance, flow behavior, regulatory readiness, and feedstock credentials. The result is a market where multi-attribute value propositions outperform single-dimension price competition.
Supply Chain and Cost Structure Dynamics
Cost structure remains a defining constraint and opportunity. Main-chain LCP pricing carries a structural premium relative to high-temperature nylons because of batch polymerization economics and the reliance on specialty monomers sourced through narrow supply channels. This cost gap limits broad displacement into commoditized applications but protects margins for producers who can deliver differentiated performance, regional supply proximity, and qualification support. Capacity expansions in localized manufacturing footprints are increasingly important for reducing logistics risk, shortening lead times, and improving service levels for high-volume customers who require consistent supply more than marginal unit-cost savings.
The competitive response to cost and supply complexity has been uneven. Leading producers are expanding regional capacity, integrating feedstock strategy into product design, and shortening qualification timelines through standardized data packages. Smaller or less diversified players face the strain of raw material volatility, longer compliance cycles, and customer expectations that increasingly demand more than technical specifications. In this environment, the market's cost structure is not merely a pricing issue; it is a strategic variable that shapes regional supply strategy, customer partnerships, and the pace at which new grades can be commercialized.
Competitive Landscape and Leading Strategies
The main-chain LCP market is characterized by concentrated leadership, with a core group of producers capturing a substantial share of volume and value. The competitive field reflects both legacy formulation expertise and accelerating strategic maneuvering across capacity, acquisition, and sustainability-driven product development. Rather than competing purely on price, leading companies are competing on technical specificity, regional supply assurance, qualification speed, and feedstock strategy.
Among the most prominent participants, Celanese Corporation has positioned its Vectra and Zenite resin and compound portfolio around high-performance electronics, connectors, and automotive applications, emphasizing flow, heat resistance, and dimensional stability. Its recent commissioning of additional LCP production capacity in China reflects a strategic emphasis on local supply for electronics and 5G-related applications, shortening lead times and improving service responsiveness in a region that remains central to electronics demand growth. Polyplastics Co., Ltd. has built its LAPEROS brand around precision molding for semiconductors, medical technology, and automotive applications, and has advanced a biomass-balanced variant using a mass-balance approach with bio-derived raw materials. This move illustrates a broader competitive trend: sustainability is being incorporated as a product attribute rather than a separate communications exercise.
Sumitomo Chemical Co., Ltd. supplies Sumikasuper resins for electronics and high-heat applications, and its acquisition of an additional LCP neat resin business from Syensqo signals a deliberate effort to strengthen offerings in ICT and mobility applications. The transaction highlights a consolidation dynamic in which incumbents are acquiring formulation capability, customer relationships, and product breadth to accelerate positioning in high-growth applications. Toray Industries, Inc. manufactures SIVERAS main-chain LCP materials for electronics and high-frequency applications, with particular emphasis on films and precision components, reinforcing a strategy centered on specialized form factors rather than commodity resin volume. Solvay S.A. through Syensqo provides Xydar grades, including high-heat and flame-retardant variants for EV battery insulation and industrial uses, aligning its portfolio with thermal safety and electrification-driven demand. Ueno Fine Chemicals Industry, Ltd. focuses on main-chain LCP production for high-performance engineering plastics in electronics and other demanding sectors, while Kuraray Co., Ltd. offers main-chain LCP materials including films and fibers for electronics and high-strength applications, extending the material's reach into structural and functional formats beyond conventional molding resins.
The competitive landscape is evolving along several vectors. Consolidation is evident through targeted acquisitions that expand resin portfolios and deepen application coverage, particularly in ICT and mobility. Differentiation is increasingly based on formulation specificity, regulatory readiness, and sustainability-enabled product variants rather than generic performance claims. Regional supply strategy has become a competitive lever, as customers prioritize local or near-local production to mitigate logistics risk and improve responsiveness. At the same time, the market is not closing to new entrants entirely, but entry barriers are rising. Specialty monomer access, batch polymerization know-how, qualification relationships, and sustainability certification infrastructure all raise the threshold for meaningful market participation. The likely trajectory is continued concentration among established producers with diversified application coverage, while niche players survive by serving highly specialized grades or regional demand pockets that larger portfolios do not prioritize. Competitive success will increasingly depend on how effectively companies integrate technical performance with regulatory compliance, feedstock strategy, and localized supply reliability.
PW Consulting Chemical & Energy Research Center
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the main-chain LCP market is likely to follow three interlocking trends that will shape both opportunity and risk. First, demand growth will remain anchored in electrification, advanced electronics, and precision engineering, but the growth will be increasingly grade-specific. General-purpose thermal materials will face substitution pressure, while LCPs engineered for high heat, flame resistance, signal integrity, and precision molding will capture disproportionate value. This means commercial opportunity will concentrate in applications where LCP's structural advantages are difficult to replicate, especially in battery-related assemblies, high-frequency electronics, connector systems, and demanding medical or aerospace components.
Second, sustainability-enabled product architecture will move from differentiator to baseline expectation in premium procurement channels. Biomass-balanced grades, certified feedstocks, and mass-balance traceability will increasingly appear in supplier selection criteria, especially for multinational OEMs and tier suppliers with public decarbonization commitments. Companies that can pair verified sustainability credentials with consistent performance and fast qualification will gain access to a widening premium procurement segment. The risk is that sustainability claims become commoditized if they are not supported by credible mass-balance accounting, transparent disclosure, and robust qualification data.
Third, regional supply strategy and qualification speed will become more decisive in capturing volume. As raw material constraints persist and regulatory review lengthens, customers will favor suppliers that can reduce logistics risk, maintain consistent lot quality, and provide standardized compliance documentation. Capacity expansions in or near key demand regions, paired with efficient qualification support, will help secure long-term supply agreements. The downside risk is that supply expansion without feedstock diversification or regulatory readiness can strand capital in grades that lose competitiveness as customer expectations evolve.
Actionable Recommendations for Decision Makers
For manufacturers and material specifiers, the priority is to align grade selection with application-specific performance thresholds while building sustainability and regulatory readiness into the sourcing decision early. Evaluate LCP grades not only on thermal and flow properties but also on qualification timelines, feedstock credentials, and regional supply reliability. Where electrification, high-frequency electronics, or precision components are involved, prioritize grades with demonstrated performance in relevant thermal, flame, and dimensional stability conditions, and confirm that the supplier can support traceable documentation and accelerated qualification.
For investors and corporate strategists, the market rewards focused exposure to high-value applications and producers with diversified resin portfolios, regional supply footprints, and credible sustainability integration. Monitor consolidation activity, capacity additions, and product launches that deepen positioning in ICT, mobility, and precision medical or aerospace segments. Assess feedstock strategy and regulatory preparedness as leading indicators of commercial resilience, since these factors increasingly determine how quickly new grades can reach customers and how sustainably margins can be defended amid raw material volatility.
For procurement and supply chain leaders, the strategic question is no longer whether LCP delivers performance, but which supplier can deliver performance consistently under evolving compliance and sourcing expectations. Negotiate for data transparency, qualification support, and regional supply assurance alongside unit pricing. Build multi-grade sourcing strategies that balance performance-critical applications with cost-sensitive uses, and ensure that sustainability claims are supported by verifiable mass-balance or feedstock certification rather than generic messaging. Detailed segment-level volume patterns, regional demand distribution, and customized procurement or investment scenarios can sharpen these decisions significantly, and the complete market report provides the granular data needed to translate these strategic insights into concrete sourcing, investment, and product-development actions.
For detailed analysis of this topic, please visit the official page: Main-Chain Liquid Crystalline Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Pharmaceutical Grade Taurine Market: 5.24% CAGR Signals Next Growth Phase
By pmarketresearch, 2026-09-18
Strategic Horizons: Navigating Growth and Complexity in the Global Pharmaceutical-Grade Taurine Market
Market Landscape: Sizing the Opportunity, Recognizing the Fault Lines
The global pharmaceutical-grade taurine market has entered a phase of measured, structurally reinforced expansion. Between 2020 and 2025, the market value progressed from approximately USD 194.5 million to an estimated USD 245.5 million, reflecting a compound annual growth rate of 5.24 percent over the historical period. Looking ahead to 2032, the trajectory points toward a valuation exceeding USD 351 million, with growth gradually stabilizing as the market matures. This expansion is not merely a reflection of incremental demand; it signals a broader integration of taurine into standardized clinical nutrition protocols, essential ophthalmic formulations, and standardized parenteral support systems. Despite the steady growth profile, the market operates within a tightly structured ecosystem. The top three players command more than two-thirds of global commercial volume, while the leading five entities collectively represent over 84 percent of total revenue generation. Such concentration shapes pricing dynamics, supply reliability, and regulatory responsiveness across downstream buyers. It also creates structural dependencies that become increasingly visible when external shocks emerge. Several critical challenges and turning points define the current operating environment. First, the transition from commodity-grade to pharmaceutical-grade material requires stringent purity thresholds, rigorous impurity controls, and batch-level traceability. Manufacturers face mounting pressure to align chemical synthesis workflows, energy-intensive purification cycles, and documentation practices with increasingly demanding pharmacopeial expectations. Second, raw material and operational cost volatility introduces margin compression risks. Periods of sharp price escalation, driven by feedstock availability, energy expenditures, and logistical bottlenecks, have forced procurement teams and manufacturers to rethink contractual frameworks and inventory buffering strategies. Third, regulatory scrutiny continues to deepen as taurine moves deeper into clinical nutrition, hospital-based formulations, and specialized pediatric applications. Compliance expectations now extend beyond basic certification toward continuous audit readiness, pharmacopeial alignment, and demonstrable supply chain transparency. These overlapping pressures are not merely operational friction points; they represent structural filters that will determine which organizations capture sustainable value in the coming years.
Market Structure and Concentration Dynamics
The geographic and application distribution of demand reveals a market shaped by regional manufacturing ecosystems, clinical practice patterns, and regulatory traditions. Asia Pacific anchors a substantial share of global volume, reflecting integrated production capacity, expanding nutraceutical and pharmaceutical demand, and established export-oriented manufacturing networks. North American and European markets contribute a combined share that underscores mature clinical nutrition frameworks, established ophthalmic product pipelines, and strong pharmacopeial compliance expectations. More emerging demand regions, while currently smaller in absolute scale, are gradually institutionalizing procurement standards that favor documented quality systems over purely cost-driven purchasing. Purity segmentation further clarifies market evolution. High-purity segments exceeding 99.5 percent purity capture the majority of value, a pattern that highlights the premium placed on clinical reliability and regulatory acceptability. Mid-tier purity ranges, while still commercially relevant, increasingly serve applications where formulation requirements or cost structures allow slightly broader specification windows. This bifurcation illustrates how buyers are progressively aligning specification requirements with clinical risk profiles, rather than applying uniform quality thresholds across all use cases.
Core Drivers Reshaping the Market Trajectory
Several interconnected forces are steering the market’s evolution. Understanding these drivers is essential for organizations evaluating capacity expansion, procurement strategy, or partnership positioning.
Technological Innovation and Manufacturing Precision
The shift toward pharmaceutical-grade taurine has elevated the importance of controlled synthesis pathways, purification efficiency, and impurity management. Traditional production relies on chemical synthesis from petrochemical-derived intermediates, followed by multi-stage purification to meet pharmacopeial thresholds. Achieving consistent purity above 99.0 percent requires careful control over energy consumption, reagent quality, crystallization conditions, and analytical verification. Recent operational developments illustrate how manufacturers are responding. Several leading producers have reaffirmed or expanded international quality certifications, reinforcing capabilities that span food, pharmaceutical, and nutraceutical channels. Such certification portfolios do more than satisfy audit requirements; they signal operating discipline that enables participation in regulated supply chains where documentation, traceability, and process consistency carry commercial weight. In parallel, certain international producers have invested in biologically derived or fermentation-based pathways to differentiate in quality perception and sourcing narrative. While synthetic routes remain dominant in terms of volume, alternative production approaches are gaining attention in specialized pediatric and clinical nutrition segments, where source transparency and refinement standards influence procurement decisions. The broader implication is that technology strategy is no longer limited to yield optimization. It now encompasses qualification readiness, batch-to-batch consistency, and alignment with region-specific pharmacopeial expectations.
Regulatory and Compliance Evolution
Regulatory environments continue to shape product specifications, documentation requirements, and market access pathways. Pharmaceutical-grade taurine is expected to align with major pharmacopeial monographs and associated impurity limits, particularly when used as an active pharmaceutical ingredient or functional excipient in hospital formulations, clinical nutrition, and ophthalmic products. Compliance is increasingly understood as a continuous operating state rather than a periodic certification event. Audit readiness, quality management integration, environmental controls, and food-safety-aligned systems have become baseline expectations for suppliers targeting regulated applications. This regulatory tightening is also changing how buyers assess risk. Procurement teams are placing greater emphasis on documented GMP compliance, standardized testing protocols, and transparent chain-of-custody arrangements. In ophthalmic and infant nutrition segments, where clinical stakes are higher and formulation tolerances are narrower, the cost of quality lapses exceeds the cost of prevention by a wide margin. Regulatory alignment therefore functions as both a market entry requirement and a strategic differentiator that supports premium positioning and long-term customer retention.
Demand-Side Shifts Across Clinical and Nutritional Applications
Demand growth is being reinforced by continued use of taurine in established clinical applications, including infant formula, ophthalmic solutions, parenteral nutrition, and selected oral pharmaceutical preparations. In infant nutrition, taurine remains relevant because of its functional role in early development formulations and its historical integration into specialized pediatric nutrition frameworks. In ophthalmology, taurine continues to appear in eye strain relief and supportive eye care formulations, a usage pattern reinforced by recent product introductions that incorporate taurine into pediatric and general eye drop platforms. These product developments illustrate that taurine’s clinical relevance is not static; it is being adapted into contemporary formulation strategies that address consumer expectations, pediatric safety considerations, and supportive care positioning. Parenteral nutrition and oral pharmaceutical use add further demand layers, particularly where standardized amino acid support and metabolic stabilization are required. In these settings, pharmaceutical-grade assurance is a prerequisite, not an optional enhancement. As hospital formularies and clinical nutrition protocols become more standardized across regions, taurine’s inclusion in approved preparation lists and institutional supply specifications creates a recurring demand base that is less sensitive to short-term consumer trends and more dependent on consistent supply performance.
Supply Chain Stress, Cost Volatility, and Strategic Sourcing
Cost volatility remains a defining market theme. Periods of sharp price movement have been linked to raw material constraints, energy-intensive purification demands, and shifting supply-demand balance across regions. A notable surge pattern observed in recent sector assessments underscores how quickly input costs can affect downstream pricing and contracting behavior. For manufacturers, this environment rewards operating flexibility, forward sourcing discipline, and cost transparency. For buyers, it underscores the importance of multi-source strategies, specification-aligned supplier qualification, and contractual structures that balance stability with responsiveness. The concentration of production among a limited set of large-scale manufacturers amplifies these dynamics. While scale and export readiness provide supply reliability advantages, they also create dependency risks. Organizations that rely heavily on single-source relationships may face greater exposure to production disruptions, certification changes, or regional logistics interruptions. As a result, supply chain strategy is shifting from purely cost-based buying toward resilience-based sourcing, where quality documentation, production redundancy, and geographic diversification receive greater weight in supplier selection.
Competitive Landscape: Strategic Positioning and Emerging Shifts
The competitive field is characterized by a mix of large-scale producers, quality-differentiated manufacturers, and region-specific API suppliers. Rather than competing solely on price, leading participants increasingly align their positioning with certification breadth, purity consistency, pharmacopeial compliance, and channel specialization. Several Chinese manufacturers dominate global output and export volumes, building commercial strength through scale, established international certifications, and broad application coverage across pharmaceutical and nutraceutical segments. Their competitive advantage lies in capacity, cost efficiency, and the ability to serve multiple regulated and semi-regulated markets simultaneously. Certification reaffirmation and expansion across quality, environmental, and food-safety standards further reinforce their ability to operate in demanding supply chains. International players introduce differentiation through production approach, sourcing narrative, and quality systems. A New Zealand-based manufacturer has carved out a position around naturally derived taurine, particularly for infant formula and pharmaceutical applications, using source origin and refinement standards as part of its commercial identity. Japanese producers emphasize fermentation-based manufacturing, rigorous testing, and traceability frameworks that support clinical nutrition and pharmaceutical use cases. Indian manufacturers have established presence through pharmacopeial-aligned offerings with defined purity levels, while United States-based suppliers position themselves around GMP-listed API supply and documented regulatory filings. These differing strategic postures illustrate that the market is not converging toward a single business model. Instead, it is fragmenting around distinct value propositions tied to sourcing, compliance narrative, and application focus.
Differentiation Levers and Strategic Positioning
Across the landscape, several differentiation levers consistently shape competitive outcomes. Purity assurance and impurity control remain foundational, with ≥99.5 percent purity attracting premium positioning in higher-risk clinical applications. Certification breadth functions as a commercial enabler, supporting access to multiple regulatory and customer environments. Traceability and quality documentation increasingly determine whether suppliers can participate in hospital procurement, clinical nutrition programs, and specialized ophthalmic supply channels. Geographic and sourcing narratives matter as well, particularly where buyers associate natural origin, fermentation pathways, or region-specific manufacturing standards with reduced perceived risk. These levers are becoming more important as the market matures. Buyers are no longer choosing suppliers based on unit price alone. They are evaluating total qualification cost, supply reliability, regulatory resilience, and alignment with application-specific risk profiles. In this environment, differentiation is less about claiming broad capability and more about demonstrating consistent performance in the segments that matter most to a given customer base.
Evolution Toward Consolidation, Specialization, and Selective Entry
Market concentration suggests further consolidation pressure, particularly as regulatory expectations rise and qualification costs increase. Smaller or less-documented producers may find it harder to access tightly controlled procurement channels unless they secure partnerships, niche application focus, or regional distribution alignment. At the same time, specialization is creating room for targeted entrants that can serve specific clinical or nutraceutical niches with strong documentation and purity consistency. New entrants are therefore more likely to succeed by addressing distinct specification requirements, regional compliance preferences, or sourcing narratives rather than attempting to compete broadly across all applications. This dual dynamic — consolidation among scale players and specialization among targeted suppliers — is likely to define the next phase of competitive evolution. Organizations that can combine operational reliability with clear application focus will be best positioned to capture value without entering an undifferentiated price competition.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The market’s next stage will be influenced by a combination of quality-driven procurement, formulation evolution, and supply chain restructuring. These trends are interdependent and will shape both opportunity and risk.
Quality, Compliance, and Specification Premiumization
One of the clearest forward signals is the continued premium on high-purity, well-documented material. As pharmacopeial alignment and GMP expectations become more embedded in procurement decisions, buyers will increasingly reward suppliers who can demonstrate consistent purity, impurity control, and traceability. This does not mean lower-tier specifications will disappear, but their commercial role will increasingly be defined by cost structure and application risk tolerance rather than by default purchasing. Suppliers that can reliably meet the highest specification tiers are likely to see stronger retention in regulated channels, while margin opportunities in commodity-adjacent segments will remain sensitive to input cost cycles.
Application Diversification and Formulation Refresh
Demand will likely be reinforced by continued use in infant nutrition, ophthalmic care, parenteral support, and specialized oral formulations, but the distribution of growth will depend on how manufacturers refresh product portfolios and adapt to regional clinical preferences. The recent introduction of taurine-containing eye care products for pediatric use reflects a broader pattern: taurine is not only maintaining its place in established applications but also being incorporated into contemporary formulations that address specific consumer and clinical needs. Over the next few years, suppliers that can provide formulation-ready quality, stable batch consistency, and application-specific documentation will have an advantage in supporting product pipeline development.
Supply Chain Reconfiguration and Resilience-Driven Sourcing
The combination of production concentration, cost volatility, and regulatory sensitivity is likely to encourage more deliberate supply chain redesign. Buyers may diversify sourcing bases, qualify alternate suppliers, and negotiate contracts that account for energy, feedstock, and logistics variability. Manufacturers may invest more heavily in quality infrastructure, certification continuity, and customer-facing traceability systems to reduce qualification friction and strengthen long-term supply relationships. In this environment, resilience will become a commercial asset, and the ability to demonstrate uninterrupted compliance will matter as much as baseline cost competitiveness. Potential risks include continued raw material and energy price fluctuations, regulatory shifts that alter specification expectations, and geopolitical or logistics disruptions affecting export-heavy supply chains. For high-concentration markets, any production interruption among leading suppliers can have disproportionate downstream effects. Organizations should therefore treat volatility not as a temporary anomaly but as a structural condition that requires planning, flexibility, and documented backup options.
Strategic Actions for Decision Makers
For manufacturers and suppliers, the priority is to reinforce differentiation through certification continuity, purity consistency, and application-focused documentation. Investing in quality systems that support audit readiness and pharmacopeial alignment will reduce commercial friction with regulated buyers. Suppliers should also evaluate whether their positioning is broad enough to serve multiple channels or focused enough to defend premium segments where consistency and traceability are valued more than unit cost. For investors, the most relevant signals are concentration patterns, certification momentum, pricing volatility cycles, and application-specific demand resilience. Markets with strong regulatory alignment and recurring institutional demand tend to reward operators with documented quality systems and stable supply performance. Investment evaluation should therefore weigh not only volume orientation but also qualification capability, geographic exposure, and sensitivity to input cost fluctuations. For procurement and sourcing leaders, the strategic imperative is to balance cost efficiency with resilience. Qualifying multiple suppliers, establishing specification-aligned acceptance criteria, and monitoring certification status can reduce exposure to single-source dependency and price shock. Procurement strategy should also account for application risk: higher-stakes clinical or pediatric use cases warrant stronger documentation and stability requirements than lower-risk formulations. Understanding these dynamics at a segment and supplier level is essential for making informed decisions in a concentrated and specification-sensitive market. Detailed segmentation data, regional breakdowns, and company-level competitive signals can sharpen planning and reduce the uncertainty that often accompanies procurement, capacity, or investment decisions in pharmaceutical-grade ingredient markets.
Taurine Market
Worldwide Pharmaceutical Grade L-Carnitine Market
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade Taurine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Worldwide Hands-Free Caddie Market
The global hands-free caddie market has entered a phase of accelerated expansion, transforming from a niche accessory into a strategic hardware category at the intersection of mobility automation and sports technology. Valued at approximately $165.15 million in 2020, the segment has grown consistently to reach $292.8 million by 2025. Projections indicate sustained momentum through the forecast horizon, with annual revenue expected to climb past $587 million by 2032. This trajectory reflects a compound annual growth rate of 10.45%, a pace that signals structural adoption rather than cyclical consumer spending. The growth is underpinned by shifting golfer preferences, mature autonomous navigation stacks, and increasing operator willingness to diffuse capital-intensive assets across higher-volume usage scenarios.
Golf GPS Market
Against this backdrop, three critical inflection points shape the current landscape. First, the technology stack is bifurcating between mature remote-control architectures and rapidly advancing autonomous follow systems that rely on sensor fusion and visual guidance. Second, course operators and equipment managers are reevaluating total cost of ownership as hands-free units begin to influence pace-of-play metrics, labor allocation, and customer retention. Third, safety and interoperability expectations are tightening. Think staggering incidents on inclines, and battery and navigation reliability standards that must hold across varied terrain and weather conditions. These pressure points are not merely compliance hurdles; they are becoming core design parameters that separate durable product lines from short-lived feature experiments.
For executives and investors, the implication is clear: the market is large enough to attract serious engineering investment, yet fragmented enough that strategic positioning, reliability engineering, and go-to-market execution will determine which players capture lasting share. Volume leadership in individual consumer adoption continues to anchor baseline demand, while institutional buyers are increasingly evaluating hands-free assets as operational tools rather than premium add-ons. This dual demand structure creates both scale potential and segmentation complexity, requiring product roadmaps that can serve recreational users and fleet operators without compromising either value proposition.
Key Drivers Reshaping the Hands-Free Caddie Market
Technology Innovation and Autonomous Navigation Maturation
The most consequential driver is the rapid maturation of autonomous following technology. Early remote-control carts solved convenience but left the golfer tethered to a handheld interface. Today, sensor-based follow systems combine radio frequency, ultrasound, visual tracking, and increasingly LiDAR or time-of-flight sensing to maintain a stable hands-free walking experience across uneven terrain and moderate slopes. The practical effect is a shift from reactive remote operation to proactive caddie behavior: obstacle detection, terrain adaptation, reverse-follow modes, and gesture-based control are moving from marketing differentiators to baseline expectations. This evolution lowers the cognitive load for the golfer, improves consistency on hilly layouts, and expands the addressable experience beyond flat, predictable courses.
PW Consulting
From a product strategy perspective, the innovation curve is creating clear trade-offs. High-end autonomous stacks increase unit cost and introduce greater software maintenance, calibration, and sensor lifecycle considerations. Meanwhile, simpler remote-control and assisted-walking configurations remain attractive for price-sensitive segments and fleet deployments where simplicity and durability outweigh advanced autonomy. The competitive question is no longer whether hands-free features exist, but how reliably they perform in edge cases: wet conditions, narrow cart paths, dense tree cover, and steep descents where braking and stability become decisive. Manufacturers that solve these real-world reliability issues are gaining a defensible position in a market where reputation for ruggedness directly influences referral velocity and repeat purchase.
Policy, Safety Standards, and Operational Regulation
Regulatory and safety frameworks are increasingly shaping product architecture. Automatic downhill braking and stability controls are now central design requirements to prevent runaway incidents, particularly on courses with significant elevation changes. This is not only a liability issue; it affects insurance considerations for courses, fleet operators, and rental programs that deploy hands-free units at scale. In parallel, broader occupational safety concerns in the golf sector highlight the value of reducing human exposure to hazards on the course. The industry is witnessing a subtle but meaningful shift: hands-free equipment is being evaluated not only for golfer convenience but also as part of a broader risk-reduction and operational efficiency narrative.
For commercial strategy, this creates an opening for brands that can document safety performance with transparent engineering specifications and consistent testing protocols. It also raises the importance of service and assurance. A hands-free caddie is increasingly treated like a light autonomous asset rather than a simple mobility accessory, which means buyers look for durability certifications, clear maintenance pathways, and product documentation that supports fleet deployment. Companies that proactively align product development with these expectations can convert safety requirements into trust capital, particularly in markets where institutional procurement and course operator adoption are gaining momentum.
Demand-Side Shifts in Golfer Behavior and Course Economics
On the demand side, the market is being reshaped by changing expectations around the walking golf experience. A growing segment of golfers seeks ways to preserve the physical and experiential benefits of walking while minimizing burden and improving pace. Hands-free caddies address this by offering assistance without removing the golfer from a mobile, course-immersive experience. This demand is reinforced by a broader interest in lightweight, foldable, and quick-deploy designs that simplify transport, storage, and daily use. At the same time, individual buyers are increasingly sensitive to battery runtime, terrain performance, and multi-mode flexibility, which means product value is judged across an experience arc rather than a single feature.
Institutional demand is following a different but complementary logic. Golf clubs, resort operators, and rental fleets are evaluating hands-free units as tools that can enhance the guest experience while supporting operational flexibility. For high-traffic properties, the ability to offer a walking option that feels modern and supportive can improve perceived quality, widen appeal to fitness-oriented players, and reduce friction in cart allocation during peak periods. However, fleet adoption introduces distinct buying criteria: robustness, serviceability, theft resistance, battery management, and predictable maintenance costs. This divergence means the market is being pulled in two directions at once, by consumer experience demands and by operator economics, and the winners will be those who design for both without forcing a compromise that weakens either segment.
Cost Structure, Battery Systems, and Supply Chain Realities
Cost dynamics remain a foundational driver. Lithium battery systems, lightweight frames, compact actuation, and integrated electronics have improved the value equation for hands-free caddies, but they also tie product economics to component availability, manufacturing consistency, and after-sales support. As demand scales, manufacturers must manage the tension between performance differentiation and cost discipline. A premium autonomous model may win on capability, but margin sustainability depends on BOM control, service parts availability, and the ability to scale without introducing quality variance. Conversely, value-oriented product lines must avoid the trap of under-specifying critical safety and terrain features in pursuit of lower price points, since poor reliability can damage adoption more quickly than a higher sticker price.
Supply chain considerations are increasingly strategic. Product lines that can modularize core components, standardize battery platforms, and reduce assembly complexity are better positioned to manage cost volatility and accelerate refreshes. At the same time, distribution and service networks matter more as the category grows. A hands-free caddie that performs well in demonstrations but lacks local support can lose momentum quickly in mature golf markets. The commercial opportunity is therefore not only in building a better product, but in building a repeatable delivery model that includes warranty handling, battery replacement pathways, and regional support infrastructure.
Competitive Landscape and Leading Strategies
Differentiated Positioning Across the Value Chain
The competitive field shows clear strategic clusters rather than a single race to the top. MGI Golf has emphasized intelligent navigation and autonomous capability, pairing patented gyroscope and AI-based navigation with rugged terrain performance and expanding its innovation pipeline with new launches at major industry gatherings. Its positioning centers on combining hands-free autonomy with the practical durability expected from a mass-market electric caddie brand. Stewart Golf has leaned into premium engineering and stability on hilly courses, using advanced follow technology to reinforce the walking experience and pace-of-play benefits. CaddyTrek has built recognition around robotic follow models that span ultrasound or RF-based tracking and Smart Vision AI with gesture control, emphasizing terrain capability and flexible operating modes. Robera has focused on gesture-based autonomous following with visual guidance, precision ranging technologies for obstacle avoidance, reverse follow, and remote options, distinguishing its product narrative through high-precision hands-free operation.
Beyond these autonomous-oriented players, other leaders have taken different routes. Kangaroo Golf has emphasized remote-control electric caddies with ergonomic interfaces, lithium batteries, autobrake, and quick-fold designs, prioritizing assisted walking performance and usability. Motocaddy has integrated GPS and remote control into its electric lineup, supporting directional control and an enhanced golfer experience. Club Car has signaled interest in fully autonomous hands-free robotic caddies designed to replicate a caddie-like following experience for walking golfers through wireless integration. PowaKaddy has continued to build electric trolley options that combine GPS and remote features for assisted hands-free walking. Alphard Golf has offered remote electric carts and systems that convert push carts into motorized hands-free operation with strong terrain performance. QOD Golf USA has targeted compact remote and electric caddies with stability features for both hands-free and hands-on walking. This diversity shows a market where autonomy, remote control, and hybrid assisted designs all remain commercially relevant, each serving different price points, user expectations, and deployment contexts.
Market Structure, Concentration, and Strategic Drift
Market concentration provides useful context for competitive strategy. A relatively small group of leading players accounts for a meaningful portion of revenue, with the top three holding around 42.5% and the top five approaching 58.2%. This level of concentration suggests that scale, brand recognition, distribution reach, and product reliability have given established players a structural advantage. At the same time, the share held by the broader field indicates room for specialized entrants, regional differentiation, and technology-led disruption. The market is not yet locked into a winner-take-most pattern, but it is moving toward clearer category leadership in both premium autonomy and value-focused remote-control segments.
The strategic implications are threefold. First, incumbents gain from repeat trust, service ecosystems, and course-level relationships that reduce buyer risk in fleet adoption. Second, specialized players can compete by owning a niche with exceptional execution, whether that means superior hill stability, richer sensor-based autonomy, lighter weight, or better ergonomics. Third, new entrants and adjacent brands can gain traction by bridging gaps between consumer convenience and operator practicality, especially where current offerings are either too premium or too utilitarian for a growing middle segment. The likely evolution is a combination of consolidation among complementary assets and continued fragmentation in feature sets, as brands differentiate around autonomy level, terrain capability, design language, and service economics rather than competing on a single dimension.
Future Trends and Commercial Implications
Over the next three to five years, the hands-free caddie market is likely to be shaped by three interconnected trends. The first is deeper autonomy with more robust perception. Follow systems will continue to integrate visual and ranging sensors, improving consistency in cluttered environments and on challenging terrain. This will raise customer expectations for hands-free behavior and push the category closer to light robotics in terms of reliability, calibration, and user interaction design. Commercially, this favors manufacturers that can pair advanced sensing with practical safety engineering, because the value of autonomy is only realized when it works predictably in real course conditions.
The second trend is broader institutional diffusion. As course operators and rental businesses gain more experience with hands-free units, adoption will increasingly be driven by operational considerations: guest experience, labor optimization, equipment utilization, and service predictability. That shift expands the addressable market beyond individual golfers and encourages product designs that support fleet management, battery logistics, and consistent handling across multiple units. The opportunity lies in offering platforms that can be configured for both retail and institutional use without fragmenting the supply base or sacrificing reliability.
Hand Trucks Market
The third trend is tighter integration with the broader golf technology ecosystem. GPS integration, connectivity features, and software-driven modes will become more common, enabling richer user experiences and better usage visibility for operators. This creates opportunities for services around data-informed maintenance, usage analytics, and upgrades, but it also introduces dependency on software lifecycle management and interoperability. The uncertainty here is not whether connectivity will expand, but whether manufacturers can sustain software support, manage cybersecurity expectations, and avoid fragmented ecosystems that frustrate buyers. Companies that treat the hands-free caddie as a connected mobility product rather than a static accessory will be better positioned to capture recurring value, provided they can deliver dependable support over time.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Prioritize reliability where it affects trust most: braking and stability on inclines, terrain adaptability, battery consistency, and intuitive mode switching. Differentiate through engineering substance rather than feature claims alone. Build modular architectures that allow cost control while preserving the ability to introduce advanced autonomous capabilities selectively. Equally important, invest in regional service capacity and parts availability, because post-purchase support increasingly determines long-term reputation in a category where hands-free performance must be proven over repeated use.
For Investors and Strategic Allocators
Focus on companies that combine defensible product differentiation with scalable distribution and clear service economics. The strongest opportunities are likely to emerge where autonomy, durability, and operational support intersect, especially in firms that can address both consumer and institutional demand without forcing an either-or strategy. Assess whether product roadmaps are aligned with sensor maturation, safety expectations, and fleet-ready design, since these factors will shape margin resilience and competitive durability as the market expands.
For Procurement Teams and Course Operators
Evaluate hands-free caddies as operational assets, not just consumer conveniences. Weight total cost of ownership, terrain performance, service response, and battery management alongside user experience. Pilot deployments should test real-course scenarios, not only showroom demonstrations, with particular attention to slope handling, obstacle response, and maintenance turnaround. A disciplined procurement approach reduces downtime risk and improves the likelihood of consistent guest satisfaction.
The market trajectory points to continued growth, but durable advantage will come from execution discipline: safety-led engineering, practical autonomy, cost-aware product design, and support infrastructure that matches commercial ambition. For decision-makers seeking segment-level sizing, regional breakdowns, pricing dynamics, and customized strategy scenarios, the full research report provides the detailed data and scenario analysis needed to translate these trends into precise operating plans.
For detailed analysis of this topic, please visit the official page: Worldwide Hands-Free Caddie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Zhi Mu Extract Market: 6.74% CAGR Transforming Asia Pacific Growth
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Zhi Mu Extract Market
Market Overview and Critical Challenges
The global market for Zhi Mu extract, derived from the rhizome of Anemarrhena asphodeloides , has demonstrated steady growth over the past five years, expanding from approximately 37.85 million USD in 2020 to an estimated 52.48 million USD in 2025. Looking ahead, the market is projected to continue its upward trajectory, reaching roughly 82.86 million USD by 2032. This expansion translates to a compound annual growth rate of 6.74 percent between 2026 and 2032, signaling sustained commercial momentum across multiple downstream sectors.
Geographically, the Asia Pacific region accounts for the largest share of total market activity, reflecting both Deep-rooted traditional usage patterns and growing domestic demand for standardized botanical ingredients. North America and Europe represent substantial secondary markets, driven largely by the incorporation of herbal extracts into dietary supplements, personal care formulations, and functional foods. Latin America and the Middle East and Africa collectively represent a smaller but gradually expanding footprint as awareness of botanical ingredients broadens across emerging consumer bases. In terms of physical form, powder extracts command the majority of market activity, while liquid extracts maintain a meaningful but secondary position. Application-wise, cosmetics and personal care represent the largest end-use segment, followed by pharmaceuticals and nutraceuticals, with food and beverages accounting for a more modest share of total demand.
PW Consulting
Despite this favorable growth trajectory, the industry is navigating several structural challenges that will define competitive outcomes over the next decade. First, supply chain concentration and raw material sourcing remain critical vulnerabilities. The primary botanical source for Zhi Mu is cultivated under controlled conditions in China, where extraction processes involve cleaning, drying, and specialized isolation techniques to capture active compounds such as timosaponins. Any disruption in cultivation cycles, quality variability across harvests, or shifts in agricultural input costs can quickly cascade through downstream pricing and availability.
Second, regulatory divergence across key markets is creating compliance complexity for manufacturers and buyers alike. In the United States, herbal products including Zhi Mu extracts are regulated as dietary supplements under DSHEA 1994, which mandates testing for pesticides, heavy metals, and microbial contamination but does not require full pharmaceutical-grade good manufacturing practices. This framework provides operational flexibility but also introduces quality assurance variability that sophisticated buyers increasingly scrutinize. Meanwhile, import dynamics have intensified cost pressures. As of April 2025, US tariffs on China-sourced botanicals reached a minimum rate of 145 percent, significantly altering the cost structure for herbal ingredients entering one of the largest consumer markets globally. This policy shift is forcing supply chain actors to reconsider sourcing strategies, formulation economics, and margin expectations.
Third, market fragmentation presents both a challenge and an opportunity. The competitive landscape remains relatively dispersed, with no single entity commanding dominant market share. This dispersion creates price competition, inconsistent quality standards across smaller producers, and limited brand differentiation in commoditized segments. Companies that can institutionalize quality control, traceability, and application-specific formulation expertise will be best positioned to capture premium positioning as buyers move beyond basic ingredient procurement toward partnership-driven supply models.
Worldwide Picrorhiza Extract Market
Key Drivers Shaping Market Trajectory
Several interlocking forces are accelerating structural change within the Zhi Mu extract market. Understanding these drivers is essential for anticipating where value will concentrate and which capabilities will separate outperforming players from the rest of the field.
Technological innovation and extraction methodology advancement represent the first major driver. The isolation of active botanical compounds, particularly timosaponins, requires precise processing to maintain potency, consistency, and stability across batches. Producers that have invested in standardized extraction protocols, controlled drying stages, and purification methods are better equipped to deliver repeatable specifications demanded by pharmaceutical, nutraceutical, and cosmetic formulators. The ability to offer extracts at defined concentration ratios, maintain low variability in active marker compounds, and document process controls has become a baseline expectation rather than a differentiator. Over time, technological maturity in extraction efficiency will also influence cost structures, enabling producers to manage input volatility while preserving margin integrity.
Policy and regulatory evolution forms the second driver, with direct implications for market access and operating costs. The US tariff environment for China-sourced botanicals has introduced a sharp cost adjustment for importers reliant on Zhi Mu materials. In response, market participants are evaluating diversified sourcing arrangements, inventory planning adjustments, and formulation cost rebalancing. Simultaneously, the regulatory framework governing herbal supplements continues to shape buyer expectations around testing, documentation, and quality assurance. While the current supplement pathway does not mandate pharmaceutical GMP, large buyers in cosmetics and nutraceuticals increasingly impose their own supplier qualification standards that exceed minimum regulatory thresholds. This dynamic rewards manufacturers with robust certification portfolios and documented process controls.
Demand-side shifts in consumer and corporate behavior constitute the third driver. Interest in botanical ingredients continues to grow across personal care, wellness, and functional nutrition categories. Consumers are increasingly attentive to ingredient provenance, clean-label positioning, and transparent sourcing narratives. For Zhi Mu specifically, its traditional usage background and expanding application in modern formulations create a bridge between heritage appeal and contemporary product development. On the corporate side, formulators are seeking botanical ingredients that can be integrated into stable, scalable production processes without compromising product claims or sensory profiles. This has elevated the importance of technical support, specification reliability, and application guidance from ingredient suppliers.
Supply chain and cost structure dynamics represent the fourth driver. Raw material cultivation, extraction processing, certification maintenance, and logistics all influence total delivered cost. As tariff pressures and input variability affect landed costs, companies are reweighting the importance of supply resilience. This includes evaluating supplier geographic concentration, understanding seasonal raw material availability, and assessing the financial impact of certification requirements such as HACCP, ISO22000, ISO9001, BRC, and organic certifications. Producers that can combine cost discipline with verifiable quality credentials are gaining negotiating leverage with downstream buyers who face their own margin and compliance pressures.
Recent commercial activity illustrates how these drivers are already playing out. Several manufacturers have increased visibility at international trade platforms, showcasing botanical ingredients to procurement teams and product developers in Europe and North America. At the same time, certain US-based producers have continued to emphasize organic-certified powder and liquid formats aimed at clean-label applications, reflecting the market's shift toward transparency and specification clarity. These developments suggest that competitive advantage is increasingly tied to market access strategy, certification depth, and the ability to serve application-specific buyer needs rather than price alone.
Competitive Landscape and Leading Strategies
The competitive environment in the Zhi Mu extract market is characterized by a mix of established botanical ingredient manufacturers, specialized extract producers, and regional suppliers with distinct strategic postures. No single company currently dominates the market, which keeps competition dynamic and creates room for differentiation through quality, certifications, and application focus.
Chinese-based manufacturers form the backbone of global supply, reflecting the concentration of raw material cultivation and extraction infrastructure in the region. Several producers have built profiles around standardized herbal extracts for global distribution, backed by certifications such as HACCP, ISO22000, and ISO9001. These credentials support export-oriented business models by signaling process reliability to international buyers. Other manufacturers emphasize customized botanical extracts tailored for human health applications, positioning themselves as flexible suppliers capable of serving bulk demand across pharmaceutical and nutraceutical channels.
A subset of producers is differentiating through organic and sustainable production emphasis. These companies pursue certifications such as BRC, organic approvals, and ISO9001 to serve buyers in pharmaceutical, nutraceutical, and cosmetic applications where ingredient integrity and documentation are especially valued. This orientation aligns with growing buyer interest in traceability and environmentally conscious sourcing narratives. Another group of manufacturers specializes in defined extract ratios for pharmaceutical-focused applications, leveraging long operating histories in botanical extracts and natural ingredients to serve formulators that require consistent specification ranges.
Outside China, US-based production represents a strategically distinct segment. One Honolulu-based manufacturer has maintained a focus on alcohol-free and alcohol-based liquid extracts and tinctures produced in small batches under GMP standards within an FDA-registered facility. This positioning appeals to buyers seeking domestically manufactured options, smaller lot flexibility, and formulation formats suited to tincture and liquid-based product development. Such offerings also respond indirectly to import cost and sourcing risk concerns by providing an alternative supply path, albeit at a different cost profile and scale.
Regional specialists also play important roles. Some suppliers concentrate on natural medical herbs and rhizoma Anemarrhenae for traditional Chinese medicine applications, servicing demand that remains closely tied to heritage usage and specific formulation traditions. Others focus on high-purity extract lines for pharmaceutical and nutraceutical applications, emphasizing product specificity and application-targeted production. The presence of multiple specialized players indicates a market that is not yet fully consolidated and where niche expertise can command meaningful buyer interest.
Leading companies are pursuing differentiation along several axes. One is certification and quality documentation. Manufacturers with multiple recognized certifications are better positioned to pass supplier qualification processes and enter regulated or semi-regulated supply chains. Another axis is application breadth. Companies that can support cosmetics, personal care, pharmaceutical, nutraceutical, and food and beverage buyers with appropriate extract formats and technical support gain cross-market optionality and reduce dependence on a single demand cycle. A third axis is market access and visibility. Participation in major trade shows and regional industry events allows producers to engage directly with international procurement teams, showcase specification capabilities, and gather market feedback that informs product and certification strategy.
The market structure appears likely to evolve through a combination of consolidation, specialization, and new entry. Consolidation may accelerate as larger botanical ingredient groups seek to secure reliable supply, expand certification portfolios, and reduce supplier fragmentation in their own value chains. Specialization will continue to reward producers that commit to specific extract formats, purity thresholds, or application segments. New entrants may emerge where import cost dynamics, domestic manufacturing incentives, or certification advantages create viable niches. Overall, the strategic imperative is moving from volume-based competition toward capability-based competition, where quality consistency, documentation depth, and buyer-facing technical support determine commercial outcomes.
Future Trends and Risk Outlook
Over the next three to five years, several trends are likely to shape how value is created and captured in the Zhi Mu extract market. The first trend is the elevation of specification and traceability as commercial defaults. As downstream buyers in cosmetics, nutraceuticals, and functional foods face greater scrutiny from retailers, regulators, and consumers, ingredient suppliers will be expected to provide more granular documentation, batch-to-batch consistency, and clearer sourcing narratives. This will reward manufacturers that invest in process control and transparent quality systems, while pressuring those that compete primarily on price without supporting documentation.
The second trend is supply chain reconfiguration in response to cost and access pressures. The current tariff environment for China-sourced botanicals is already prompting buyers to reexamine sourcing mix, inventory timing, and formulation economics. While China will likely remain a central source of raw material supply for the foreseeable future, market participants may pursue diversified sourcing strategies, regional manufacturing options, or reformulated product economics to manage cost volatility. This trend creates opportunities for producers with strong certifications, stable supply continuity, and flexible export capabilities, but it also raises the importance of risk planning for buyers dependent on single-source procurement.
The third trend is application expansion beyond traditional use cases. While cosmetics and personal care currently represent the largest demand segment, interest in nutraceuticals, functional food and beverage formats, and specialized liquid extract applications continues to broaden the commercial canvas. Companies that can translate raw botanical material into application-ready ingredients with appropriate stability, sensory compatibility, and claim-supportable specifications will be best positioned to capture growth across these emerging demand pockets.
Worldwide Houttuynia Extract Market
Potential risks and uncertainties should not be overlooked. Regulatory requirements may tighten in key markets, changing testing expectations or documentation thresholds and increasing compliance costs. Trade policy volatility could continue to affect landed costs and disrupt established procurement patterns. Raw material supply remains exposed to agricultural variability, climate influences, and cultivation scale limitations, which could affect availability and pricing at times. Finally, quality inconsistency across smaller producers may trigger buyer consolidation toward fewer, more credible suppliers, intensifying competitive pressure on manufacturers without differentiated credentials or technical capabilities.
Strategic Recommendations for Decision Makers
For manufacturers and ingredient producers, the priority is to strengthen specification reliability, certification depth, and application-specific support. Investing in process controls, documentation, and recognized quality credentials will improve access to downstream buyers with stricter supplier qualification standards. At the same time, producers should evaluate how supply chain risks, including raw material variability and import cost pressures, can be mitigated through capacity planning, diversified customer exposure, and clear positioning around extract formats and application fit.
For investors, the market signals a preference for capabilities rather than scale alone. Opportunity areas include producers with credible certification portfolios, stable quality systems, and demonstrated access to international buyer channels. Sector oversight should also weigh exposure to trade policy shifts, raw material sourcing concentration, and the pace at which demand expands beyond the largest application segments. A disciplined view of margin sustainability under different sourcing and tariff scenarios will help distinguish resilient business models from those vulnerable to cost shocks.
For procurement teams and formulators, the actionable focus is to treat ingredient selection as a multi-dimensional decision rather than a unit-price exercise. Evaluating supplier quality systems, extract format suitability, batch consistency, and documentation readiness can reduce downstream reformulation risk and improve product launch reliability. Diversifying sourcing where feasible and maintaining visibility into supply continuity will also help manage exposure to cost volatility and policy changes.
Keeping pace with specification evolution, certification expectations, and shifting sourcing economics requires timely, granular intelligence. Decision makers who want detailed segmentation data, competitive benchmarking, and customized strategic guidance will find additional value in the complete research report, which extends the analysis with deeper segmentation breakdowns and application-specific commercial implications.
For detailed analysis of this topic, please visit the official page: Worldwide Zhi Mu Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Special Category Semi-trailer Market: Why 5.48% CAGR Changes Everything
By pmarketresearch, 2026-09-18
Strategic Shifts and Commercial Opportunities in the Worldwide Special Category Semi-trailer Market
The worldwide special category semi-trailer market has entered a phase of structural expansion, driven by the need to move oversized, temperature-sensitive, and hazardous cargo across increasingly complex supply chains. Valued at approximately USD 20.96 billion in 2025, the market has grown consistently from a base of roughly USD 16.5 billion in 2020, reflecting a compound annual growth rate of 5.48 percent through 2032. By the end of the forecast period, revenue is projected to approach USD 30.45 billion, signaling durable demand rather than a cyclical upturn. This trajectory underscores a fundamental shift in how heavy and specialized freight is mobilized globally, with manufacturers and fleet operators alike recalibrating capacity, materials, and product architecture to meet evolving operational realities.
Behind the headline growth figures lies a landscape defined by uneven regional momentum and product-level divergence. North America, Europe, and Asia Pacific collectively anchor the largest revenue pools, each shaped by distinct infrastructure maturity, regulatory intensity, and industrial demand profiles. Product categories spanning lowboy, refrigerated, tanker, car carrier, and logging configurations continue to coexist, but their growth trajectories are increasingly decoupled. The market is not growing uniformly; instead, it is being reshaped by application-specific requirements, where logistics and transportation, construction and infrastructure, oil and gas, and food and beverage sectors each impose different payload, durability, and compliance expectations.
Several critical challenges and inflection points define the current market environment. First, the industry is navigating a tightening regulatory perimeter around emissions and safety standards, forcing manufacturers to reconsider powertrain-adjacent design choices and component selection even for non-propelled trailer assets. Second, raw material economics have become a persistent source of margin pressure and strategic trade-offs, as producers balance weight reduction benefits against cost premiums and embedded carbon considerations. Third, the market is experiencing a gradual bifurcation between standardized volume production and highly customized special-category solutions, creating operational complexity for OEMs that must serve both segments without diluting expertise or scale advantages. These dynamics are not temporary friction points; they are reshaping competitive positioning and investment priorities across the value chain.
Core Drivers Reshaping Market Trajectory
Technological innovation is moving beyond incremental improvements and beginning to redefine what special category semi-trailers can deliver in terms of payload efficiency, safety, and operational visibility. Advancements in high-strength steel alloys and engineered aluminum formulations are enabling lighter yet structurally robust configurations, allowing operators to maximize legal payloads without compromising durability. At the same time, integration of telematics, load-sensing systems, and modular coupling architectures is transforming trailers from passive cargo carriers into data-enabled components of smarter freight networks. These capabilities are particularly valuable in special category applications, where load stability, route constraints, and configuration flexibility directly influence utilization rates and total cost of ownership.
The regulatory environment is exerting a parallel and equally powerful influence. Environmental mandates targeting heavy-duty transport are increasingly extending their reach into trailer design and material choices, even when the trailer itself does not generate propulsion emissions. Standards governing braking performance, lighting, structural integrity, and safe operation continue to raise the baseline for market entry, while emissions-related frameworks are nudging manufacturers toward materials and designs that support broader fleet efficiency goals. Compliance is no longer a checkbox exercise; it is becoming a design constraint that rewards early adopters of lighter, more efficient, and easier-to-integrate special category platforms.
PW Consulting
Demand-side behavior is shifting as freight networks prioritize reliability, speed, and cargo integrity across longer and more fragmented routes. Logistics and transportation operators are expanding their reliance on specialized equipment to handle complex multimodal movements, while construction and infrastructure activity is sustaining demand for heavy-lift and low-clearance configurations. Simultaneously, temperature-sensitive and high-value cargo flows are reinforcing the role of refrigerated and secure carrier formats. Buyers are increasingly evaluating trailers not just on acquisition cost but on lifecycle performance, downtime risk, and compatibility with evolving fleet management practices. This evaluation shift is pushing manufacturers to articulate value through durability, configurability, and service support rather than price alone.
Specialty Tire Market
Supply chain and cost structure dynamics complete the driver set. Material availability, energy costs, and production localization decisions are reshaping manufacturing economics, particularly for high-specification special category units that require specialized fabrication and quality control. The relative cost of aluminum versus steel remains a recurring strategic consideration, with aluminum offering measurable weight and payload advantages while carrying a higher upfront price and a materially larger carbon footprint per kilogram produced. In parallel, regional production footprints are being revisited as OEMs seek to reduce lead times, respond to local compliance requirements, and better serve fragmented demand pockets. These supply-side pressures are encouraging more modular design approaches, selective material substitution, and closer alignment between manufacturing capacity and end-market demand clusters.
Competitive Landscape and Leading Strategies
The competitive field in the special category semi-trailer market is defined by a mix of large-scale multinational OEMs and specialized manufacturers with deep application expertise. Companies such as CIMC Vehicles, Schmitz Cargobull AG, Krone Commercial Vehicle Group, Wabash National Corporation, Great Dane LLC, Hyundai Translead, and Kässbohrer occupy prominent positions by combining broad product portfolios with regional manufacturing strength and established aftermarket support. Their scale enables them to serve high-volume logistics segments while maintaining dedicated lines for heavy haul, temperature-controlled, and custom configurations. At the same time, a second tier of specialist producers—including Miller Industries, Cottrell, Faymonville/MAX Trailer, Nooteboom Trailers, Goldhofer, Landoll, Boydstun, and Heil Trailer International—competes on niche proficiency, often winning demand in vehicle transport, car hauling, extendible lowbed, and liquid or dry bulk applications where engineering specificity and operational familiarity carry outsized weight.
Leading players are differentiating through a combination of product breadth, regional responsiveness, and capability depth rather than through price competition alone. Global-scale OEMs lean on standardized platforms, broad service networks, and the ability to offer multiple special category variants from shared manufacturing logic, which helps manage cost while preserving configuration flexibility. Specialist manufacturers, by contrast, often compete by tailoring structural layouts, axle arrangements, and coupling systems to very specific load profiles and route conditions. This dual structure creates a market where scale and specialization coexist, and where the most resilient brands are those that can move between volume-oriented production and highly engineered custom builds without losing quality control or delivery predictability.
Recent market developments point to a landscape that is becoming more transparent, more regionally nuanced, and more responsive to near-term demand signals. Global OEM rankings based on confirmed production output have drawn sharper attention to relative scale and capacity utilization, giving buyers and investors a clearer reference point for manufacturing leadership. At the same time, regional manufacturers are reinforcing their positioning by emphasizing durability, compliance, and service availability for both domestic and export markets. New model-year listings for specialized variants, including paver and heavy-duty configurations, indicate that product refresh cycles and application-specific availability remain key tools for capturing demand in segmented verticals. These signals suggest that competitive advantage is increasingly tied to the ability to align production readiness with localized demand timing.
The market structure is evolving along two intersecting paths: consolidation at the scale end and persistent fragmentation at the specialist end. Larger groups are well placed to absorb compliance costs, invest in material and design innovation, and expand service coverage across regions, which can pressure smaller competitors that lack capital flexibility or geographic reach. Yet the long tail of specialized demand continues to support smaller, highly focused manufacturers that can iterate quickly on custom configurations and build deep relationships in narrow application segments. New entrants are most likely to succeed where they can combine a clear application focus with reliable compliance, cost-competitive material strategies, and credible after-sales support. For incumbents, the strategic question is not whether to pursue scale or specialization, but how to organize both within a single operating model that can switch efficiently between standardized output and custom engineering.
Forward Outlook: Trends Shaping the Next Three to Five Years
One of the most consequential trends ahead is the continued integration of material and design innovation with regulatory and efficiency pressures. As emissions-related standards for heavy-duty transport tighten and fleet operators look for every available lever to improve utilization and reduce operating cost, lighter and more structurally efficient special category trailers will gain preference in many applications. Expect greater experimentation with mixed-material architectures, higher-strength steel grades, and selective aluminum use where payload or fuel-efficiency gains justify the cost premium. The commercial opportunity lies in offering modular, application-tuned platforms that let buyers balance weight, durability, and total cost of ownership without committing to a single material philosophy across the entire fleet.
Semitrailer (Semi-Trailer) Market
A second trend is the growing importance of configuration agility and regional production alignment. Demand for special category equipment is unlikely to homogenize; instead, it will continue to cluster around specific industrial corridors, resource projects, and logistics hubs. Manufacturers that can tailor axle layouts, deck heights, tank formats, and carrier adaptations to local requirements—while maintaining repeatable quality and reasonable lead times—will capture disproportionate share in high-value segments. This creates an opening for producers that invest in flexible fabrication, regional service presence, and rapid customization workflows, especially in markets where infrastructure projects, energy activity, or temperature-controlled freight are expanding faster than the broader fleet base.
A third trend is the gradual shift from equipment purchase decisions to lifecycle and compliance-aware procurement. Buyers are increasingly weighing safety standards, emissions-linked material implications, maintenance access, and integration with fleet data systems when selecting special category semi-trailers. This creates room for manufacturers and suppliers that can demonstrate transparent performance characteristics, predictable service intervals, and compatibility with broader operational management tools. The associated risk is that misalignment between product design and future compliance expectations could erode competitiveness, particularly if standards converge in ways that favor lighter, more efficient, and more easily certified configurations. Uncertainty around material costs, regional demand pacing, and the exact timing of regulatory effects will require scenario-based planning rather than fixed long-term commitments.
Actionable Priorities for Decision-Makers
For manufacturers, the immediate priority is to strengthen the balance between scale efficiency and application-specific engineering. That means investing in modular platforms, clarifying material strategies in light of both cost and carbon considerations, and building production flexibility that can absorb regional demand swings without sacrificing delivery reliability. Firms that can demonstrate credible compliance readiness, predictable customization lead times, and strong service coverage will be better positioned to defend margins as competition intensifies around differentiated capability rather than base pricing.
For investors, the most relevant signal is that growth is concentrated in specific product and application pockets rather than distributed evenly across the market. Capital allocation should favor producers with clear positioning in high-demand special categories, durable regional manufacturing footprints, and the operational discipline to manage material cost volatility. Diversification into adjacent service, aftermarket, and configuration-support capabilities can also provide resilience when new equipment cycles slow or when procurement shifts toward lifecycle value.
For procurement teams and fleet operators, the strategic imperative is to evaluate special category semi-trailers as long-term operational assets rather than short-term cost items. Decisions should incorporate payload efficiency, compliance trajectory, material trade-offs, and service accessibility alongside acquisition price, with particular attention to how equipment choices align with anticipated cargo mix and route complexity. Given the pace of regulatory, material, and demand-side change, access to granular segmentation data and scenario-based market intelligence is increasingly valuable for reducing procurement risk and timing capacity decisions more effectively. For organizations seeking a deeper dive into segment-level dynamics, regional comparisons, and tailored strategic implications, the full research report provides the detailed breakdown needed to translate these trends into operational and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Special Category Semi-trailer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com