

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global Pharmaceutical Grade Taurine Market: 5.24% CAGR Signals Next Growth Phase

Strategic Horizons: Navigating Growth and Complexity in the Global Pharmaceutical-Grade Taurine Market
Market Landscape: Sizing the Opportunity, Recognizing the Fault Lines
The global pharmaceutical-grade taurine market has entered a phase of measured, structurally reinforced expansion. Between 2020 and 2025, the market value progressed from approximately USD 194.5 million to an estimated USD 245.5 million, reflecting a compound annual growth rate of 5.24 percent over the historical period. Looking ahead to 2032, the trajectory points toward a valuation exceeding USD 351 million, with growth gradually stabilizing as the market matures. This expansion is not merely a reflection of incremental demand; it signals a broader integration of taurine into standardized clinical nutrition protocols, essential ophthalmic formulations, and standardized parenteral support systems. Despite the steady growth profile, the market operates within a tightly structured ecosystem. The top three players command more than two-thirds of global commercial volume, while the leading five entities collectively represent over 84 percent of total revenue generation. Such concentration shapes pricing dynamics, supply reliability, and regulatory responsiveness across downstream buyers. It also creates structural dependencies that become increasingly visible when external shocks emerge. Several critical challenges and turning points define the current operating environment. First, the transition from commodity-grade to pharmaceutical-grade material requires stringent purity thresholds, rigorous impurity controls, and batch-level traceability. Manufacturers face mounting pressure to align chemical synthesis workflows, energy-intensive purification cycles, and documentation practices with increasingly demanding pharmacopeial expectations. Second, raw material and operational cost volatility introduces margin compression risks. Periods of sharp price escalation, driven by feedstock availability, energy expenditures, and logistical bottlenecks, have forced procurement teams and manufacturers to rethink contractual frameworks and inventory buffering strategies. Third, regulatory scrutiny continues to deepen as taurine moves deeper into clinical nutrition, hospital-based formulations, and specialized pediatric applications. Compliance expectations now extend beyond basic certification toward continuous audit readiness, pharmacopeial alignment, and demonstrable supply chain transparency. These overlapping pressures are not merely operational friction points; they represent structural filters that will determine which organizations capture sustainable value in the coming years.
Market Structure and Concentration Dynamics
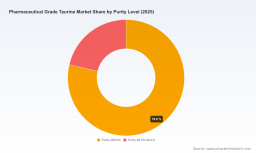
The geographic and application distribution of demand reveals a market shaped by regional manufacturing ecosystems, clinical practice patterns, and regulatory traditions. Asia Pacific anchors a substantial share of global volume, reflecting integrated production capacity, expanding nutraceutical and pharmaceutical demand, and established export-oriented manufacturing networks. North American and European markets contribute a combined share that underscores mature clinical nutrition frameworks, established ophthalmic product pipelines, and strong pharmacopeial compliance expectations. More emerging demand regions, while currently smaller in absolute scale, are gradually institutionalizing procurement standards that favor documented quality systems over purely cost-driven purchasing. Purity segmentation further clarifies market evolution. High-purity segments exceeding 99.5 percent purity capture the majority of value, a pattern that highlights the premium placed on clinical reliability and regulatory acceptability. Mid-tier purity ranges, while still commercially relevant, increasingly serve applications where formulation requirements or cost structures allow slightly broader specification windows. This bifurcation illustrates how buyers are progressively aligning specification requirements with clinical risk profiles, rather than applying uniform quality thresholds across all use cases.
Core Drivers Reshaping the Market Trajectory
Several interconnected forces are steering the market’s evolution. Understanding these drivers is essential for organizations evaluating capacity expansion, procurement strategy, or partnership positioning.
Technological Innovation and Manufacturing Precision
The shift toward pharmaceutical-grade taurine has elevated the importance of controlled synthesis pathways, purification efficiency, and impurity management. Traditional production relies on chemical synthesis from petrochemical-derived intermediates, followed by multi-stage purification to meet pharmacopeial thresholds. Achieving consistent purity above 99.0 percent requires careful control over energy consumption, reagent quality, crystallization conditions, and analytical verification. Recent operational developments illustrate how manufacturers are responding. Several leading producers have reaffirmed or expanded international quality certifications, reinforcing capabilities that span food, pharmaceutical, and nutraceutical channels. Such certification portfolios do more than satisfy audit requirements; they signal operating discipline that enables participation in regulated supply chains where documentation, traceability, and process consistency carry commercial weight. In parallel, certain international producers have invested in biologically derived or fermentation-based pathways to differentiate in quality perception and sourcing narrative. While synthetic routes remain dominant in terms of volume, alternative production approaches are gaining attention in specialized pediatric and clinical nutrition segments, where source transparency and refinement standards influence procurement decisions. The broader implication is that technology strategy is no longer limited to yield optimization. It now encompasses qualification readiness, batch-to-batch consistency, and alignment with region-specific pharmacopeial expectations.
Regulatory and Compliance Evolution
Regulatory environments continue to shape product specifications, documentation requirements, and market access pathways. Pharmaceutical-grade taurine is expected to align with major pharmacopeial monographs and associated impurity limits, particularly when used as an active pharmaceutical ingredient or functional excipient in hospital formulations, clinical nutrition, and ophthalmic products. Compliance is increasingly understood as a continuous operating state rather than a periodic certification event. Audit readiness, quality management integration, environmental controls, and food-safety-aligned systems have become baseline expectations for suppliers targeting regulated applications. This regulatory tightening is also changing how buyers assess risk. Procurement teams are placing greater emphasis on documented GMP compliance, standardized testing protocols, and transparent chain-of-custody arrangements. In ophthalmic and infant nutrition segments, where clinical stakes are higher and formulation tolerances are narrower, the cost of quality lapses exceeds the cost of prevention by a wide margin. Regulatory alignment therefore functions as both a market entry requirement and a strategic differentiator that supports premium positioning and long-term customer retention.
Demand-Side Shifts Across Clinical and Nutritional Applications
Demand growth is being reinforced by continued use of taurine in established clinical applications, including infant formula, ophthalmic solutions, parenteral nutrition, and selected oral pharmaceutical preparations. In infant nutrition, taurine remains relevant because of its functional role in early development formulations and its historical integration into specialized pediatric nutrition frameworks. In ophthalmology, taurine continues to appear in eye strain relief and supportive eye care formulations, a usage pattern reinforced by recent product introductions that incorporate taurine into pediatric and general eye drop platforms. These product developments illustrate that taurine’s clinical relevance is not static; it is being adapted into contemporary formulation strategies that address consumer expectations, pediatric safety considerations, and supportive care positioning. Parenteral nutrition and oral pharmaceutical use add further demand layers, particularly where standardized amino acid support and metabolic stabilization are required. In these settings, pharmaceutical-grade assurance is a prerequisite, not an optional enhancement. As hospital formularies and clinical nutrition protocols become more standardized across regions, taurine’s inclusion in approved preparation lists and institutional supply specifications creates a recurring demand base that is less sensitive to short-term consumer trends and more dependent on consistent supply performance.
Supply Chain Stress, Cost Volatility, and Strategic Sourcing
Cost volatility remains a defining market theme. Periods of sharp price movement have been linked to raw material constraints, energy-intensive purification demands, and shifting supply-demand balance across regions. A notable surge pattern observed in recent sector assessments underscores how quickly input costs can affect downstream pricing and contracting behavior. For manufacturers, this environment rewards operating flexibility, forward sourcing discipline, and cost transparency. For buyers, it underscores the importance of multi-source strategies, specification-aligned supplier qualification, and contractual structures that balance stability with responsiveness. The concentration of production among a limited set of large-scale manufacturers amplifies these dynamics. While scale and export readiness provide supply reliability advantages, they also create dependency risks. Organizations that rely heavily on single-source relationships may face greater exposure to production disruptions, certification changes, or regional logistics interruptions. As a result, supply chain strategy is shifting from purely cost-based buying toward resilience-based sourcing, where quality documentation, production redundancy, and geographic diversification receive greater weight in supplier selection.
Competitive Landscape: Strategic Positioning and Emerging Shifts
The competitive field is characterized by a mix of large-scale producers, quality-differentiated manufacturers, and region-specific API suppliers. Rather than competing solely on price, leading participants increasingly align their positioning with certification breadth, purity consistency, pharmacopeial compliance, and channel specialization. Several Chinese manufacturers dominate global output and export volumes, building commercial strength through scale, established international certifications, and broad application coverage across pharmaceutical and nutraceutical segments. Their competitive advantage lies in capacity, cost efficiency, and the ability to serve multiple regulated and semi-regulated markets simultaneously. Certification reaffirmation and expansion across quality, environmental, and food-safety standards further reinforce their ability to operate in demanding supply chains. International players introduce differentiation through production approach, sourcing narrative, and quality systems. A New Zealand-based manufacturer has carved out a position around naturally derived taurine, particularly for infant formula and pharmaceutical applications, using source origin and refinement standards as part of its commercial identity. Japanese producers emphasize fermentation-based manufacturing, rigorous testing, and traceability frameworks that support clinical nutrition and pharmaceutical use cases. Indian manufacturers have established presence through pharmacopeial-aligned offerings with defined purity levels, while United States-based suppliers position themselves around GMP-listed API supply and documented regulatory filings. These differing strategic postures illustrate that the market is not converging toward a single business model. Instead, it is fragmenting around distinct value propositions tied to sourcing, compliance narrative, and application focus.
Differentiation Levers and Strategic Positioning
Across the landscape, several differentiation levers consistently shape competitive outcomes. Purity assurance and impurity control remain foundational, with ≥99.5 percent purity attracting premium positioning in higher-risk clinical applications. Certification breadth functions as a commercial enabler, supporting access to multiple regulatory and customer environments. Traceability and quality documentation increasingly determine whether suppliers can participate in hospital procurement, clinical nutrition programs, and specialized ophthalmic supply channels. Geographic and sourcing narratives matter as well, particularly where buyers associate natural origin, fermentation pathways, or region-specific manufacturing standards with reduced perceived risk. These levers are becoming more important as the market matures. Buyers are no longer choosing suppliers based on unit price alone. They are evaluating total qualification cost, supply reliability, regulatory resilience, and alignment with application-specific risk profiles. In this environment, differentiation is less about claiming broad capability and more about demonstrating consistent performance in the segments that matter most to a given customer base.
Evolution Toward Consolidation, Specialization, and Selective Entry
Market concentration suggests further consolidation pressure, particularly as regulatory expectations rise and qualification costs increase. Smaller or less-documented producers may find it harder to access tightly controlled procurement channels unless they secure partnerships, niche application focus, or regional distribution alignment. At the same time, specialization is creating room for targeted entrants that can serve specific clinical or nutraceutical niches with strong documentation and purity consistency. New entrants are therefore more likely to succeed by addressing distinct specification requirements, regional compliance preferences, or sourcing narratives rather than attempting to compete broadly across all applications. This dual dynamic — consolidation among scale players and specialization among targeted suppliers — is likely to define the next phase of competitive evolution. Organizations that can combine operational reliability with clear application focus will be best positioned to capture value without entering an undifferentiated price competition.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The market’s next stage will be influenced by a combination of quality-driven procurement, formulation evolution, and supply chain restructuring. These trends are interdependent and will shape both opportunity and risk.
Quality, Compliance, and Specification Premiumization
One of the clearest forward signals is the continued premium on high-purity, well-documented material. As pharmacopeial alignment and GMP expectations become more embedded in procurement decisions, buyers will increasingly reward suppliers who can demonstrate consistent purity, impurity control, and traceability. This does not mean lower-tier specifications will disappear, but their commercial role will increasingly be defined by cost structure and application risk tolerance rather than by default purchasing. Suppliers that can reliably meet the highest specification tiers are likely to see stronger retention in regulated channels, while margin opportunities in commodity-adjacent segments will remain sensitive to input cost cycles.
Application Diversification and Formulation Refresh
Demand will likely be reinforced by continued use in infant nutrition, ophthalmic care, parenteral support, and specialized oral formulations, but the distribution of growth will depend on how manufacturers refresh product portfolios and adapt to regional clinical preferences. The recent introduction of taurine-containing eye care products for pediatric use reflects a broader pattern: taurine is not only maintaining its place in established applications but also being incorporated into contemporary formulations that address specific consumer and clinical needs. Over the next few years, suppliers that can provide formulation-ready quality, stable batch consistency, and application-specific documentation will have an advantage in supporting product pipeline development.
Supply Chain Reconfiguration and Resilience-Driven Sourcing
The combination of production concentration, cost volatility, and regulatory sensitivity is likely to encourage more deliberate supply chain redesign. Buyers may diversify sourcing bases, qualify alternate suppliers, and negotiate contracts that account for energy, feedstock, and logistics variability. Manufacturers may invest more heavily in quality infrastructure, certification continuity, and customer-facing traceability systems to reduce qualification friction and strengthen long-term supply relationships. In this environment, resilience will become a commercial asset, and the ability to demonstrate uninterrupted compliance will matter as much as baseline cost competitiveness. Potential risks include continued raw material and energy price fluctuations, regulatory shifts that alter specification expectations, and geopolitical or logistics disruptions affecting export-heavy supply chains. For high-concentration markets, any production interruption among leading suppliers can have disproportionate downstream effects. Organizations should therefore treat volatility not as a temporary anomaly but as a structural condition that requires planning, flexibility, and documented backup options.
Strategic Actions for Decision Makers
For manufacturers and suppliers, the priority is to reinforce differentiation through certification continuity, purity consistency, and application-focused documentation. Investing in quality systems that support audit readiness and pharmacopeial alignment will reduce commercial friction with regulated buyers. Suppliers should also evaluate whether their positioning is broad enough to serve multiple channels or focused enough to defend premium segments where consistency and traceability are valued more than unit cost. For investors, the most relevant signals are concentration patterns, certification momentum, pricing volatility cycles, and application-specific demand resilience. Markets with strong regulatory alignment and recurring institutional demand tend to reward operators with documented quality systems and stable supply performance. Investment evaluation should therefore weigh not only volume orientation but also qualification capability, geographic exposure, and sensitivity to input cost fluctuations. For procurement and sourcing leaders, the strategic imperative is to balance cost efficiency with resilience. Qualifying multiple suppliers, establishing specification-aligned acceptance criteria, and monitoring certification status can reduce exposure to single-source dependency and price shock. Procurement strategy should also account for application risk: higher-stakes clinical or pediatric use cases warrant stronger documentation and stability requirements than lower-risk formulations. Understanding these dynamics at a segment and supplier level is essential for making informed decisions in a concentrated and specification-sensitive market. Detailed segmentation data, regional breakdowns, and company-level competitive signals can sharpen planning and reduce the uncertainty that often accompanies procurement, capacity, or investment decisions in pharmaceutical-grade ingredient markets.
Taurine Market
Worldwide Pharmaceutical Grade L-Carnitine Market
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade Taurine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com