

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
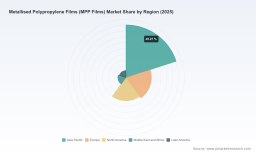
How Asia Pacific Dominates the Global MPP Films Market's 5.72% CAGR Path

Navigating Strategic Shifts in the Global Metallised Polypropylene Films Market
Market Status and Core Challenges
The global metallised polypropylene films (MPP films) market has transitioned into a phase of steady expansion, underpinned by consistent demand across electrical, packaging, and industrial applications. Revenue grew from approximately $2.75 billion in 2020 to around $3.65 billion by 2025, with a compound annual growth rate of 5.72 percent projected through 2032. This trajectory reflects a market that has successfully navigated recent macroeconomic turbulence while maintaining structural momentum. The expansion is not uniform across all pathways, however, as growth is increasingly shaped by how different industrial sectors absorb cost pressures, adapt to regulatory expectations, and integrate newer manufacturing technologies.
Polypropylene Pp Synthetic Paper Market
Understanding the market today requires acknowledging that scale alone no longer guarantees advantage. The industry operates with a moderately concentrated structure, where a handful of established players command significant share, yet regional manufacturing footprints and application-specific expertise create meaningful differentiation. This concentration presents both stability and vulnerability: established supply relationships and brand recognition provide resilience, but they also raise the bar for new entrants seeking to compete on price or performance alone. At the same time, the market’s breadth spans highly technical capacitor-grade films and broader packaging-grade variants, meaning that competitive positioning depends heavily on which segment a manufacturer prioritizes and how well it aligns with downstream demand patterns.
MCPP Film for Packaging Market
Several converging challenges define the current inflection point. First, raw material volatility has become a persistent operational reality. Polypropylene feedstock pricing has exhibited sharp regional swings, with certain markets experiencing double-digit year-over-year increases driven by tighter supply conditions and fluctuating monomer costs. These movements compress margins for film producers who cannot easily pass costs downstream, particularly in price-sensitive packaging applications. Second, the gap between high-performance technical films and commodity packaging films is widening in terms of required investment. Manufacturers pursuing capacitor-grade or specialized industrial films face higher qualification standards, tighter tolerances, and longer customer validation cycles, while those focused on packaging must contend with intensifying competition from alternative barrier materials and converter-level integration. Third, regulatory and sustainability expectations are reshaping procurement criteria across end-use sectors. Electrical and automotive buyers increasingly prioritize components that support energy efficiency, thermal durability, and extended service life, while food and beverage packaging customers face mounting pressure to balance barrier performance with recyclability and reduced material complexity. These forces are not isolated; they interact to create a market where strategic clarity matters more than ever.
For executives and investors, the core question is no longer whether the market will grow, but where value will accrue as these challenges reshape cost structures, qualification pathways, and competitive dynamics. The companies that navigate this environment most effectively will be those that treat raw material exposure, application specialization, and regulatory alignment as integrated strategic variables rather than separate operational concerns.
Key Drivers of Market Change
The trajectory of the MPP films market is being shaped by a combination of technological advancement, regulatory pressure, demand-side evolution, and shifting supply chain economics. Each driver reinforces the others in ways that create both operational challenges and structural opportunities for well-positioned players.
Innovation in film architecture and metallisation techniques continues to raise the performance ceiling for both capacitor-grade and packaging-grade applications. Advances in vacuum deposition control, layer uniformity, and precision etching have improved dielectric consistency, insulation resistance, and breakdown voltage characteristics, enabling films to meet increasingly demanding specifications in power electronics, lighting, and motor control systems. In packaging, higher barrier uniformity and tighter thickness control support longer shelf life and reduce the need for multi-layer laminates, which appeals to brands seeking simpler material streams. These technical gains are not merely incremental; they expand the addressable use cases for MPP films into applications where alternatives previously held an advantage. The result is a market where performance differentiation is becoming a more reliable route to pricing power than volume alone.
Policy and regulatory environments are exerting a comparable influence, particularly in regions where energy efficiency standards, automotive qualification requirements, and packaging sustainability mandates are tightening in tandem. In the electrical and automotive sectors, stricter qualification frameworks and thermal durability expectations are filtering out lower-specification materials, favouring suppliers that can demonstrate consistent performance under elevated temperatures and prolonged electrical stress. At the same time, packaging regulations that encourage reduced waste, improved recyclability, and lower carbon intensity are pushing converters and brand owners to re-evaluate film choices. When MPP films can deliver required barrier properties with fewer composite layers or support closed-loop packaging design, they gain relevance in tenders and specification updates. Regulatory pressure therefore acts as a filter, rewarding manufacturers that can align product attributes with evolving compliance and procurement criteria.
Demand-side behaviour is shifting in ways that reinforce these technical and regulatory trends. In consumer electronics and automotive electrification, the push toward higher power density, smaller form factors, and more robust energy conversion systems is increasing reliance on reliable dielectric films that can operate reliably in challenging thermal and electrical environments. Renewable energy infrastructure and industrial power utilities are also expanding their requirement for capacitors and insulation materials that support grid stability and long-duration performance. On the packaging side, brand owners are balancing consumer expectations for convenience and shelf life with corporate sustainability commitments, creating demand for films that combine barrier functionality with material efficiency. These demand shifts are not uniform across regions or sectors, but they share a common direction: buyers are placing greater weight on reliability, efficiency, and material optimisation, and they are willing to qualify suppliers that can demonstrate those attributes credibly.
Supply chain and cost structure dynamics complete the picture. Feedstock pricing has become more regionally divergent, with some markets experiencing sharp upward movements while others see more moderate or even temporarily softening trends. These differences influence where production is competitive, how inventory is managed, and which customers face the greatest pressure to absorb cost increases. Manufacturers with integrated operations, flexible sourcing strategies, or the ability to pass through value-based pricing in high-specification applications are better positioned to manage this volatility. Conversely, companies dependent on single-region feedstock or heavily exposed to commodity packaging margins face a more difficult path. In this environment, cost management is increasingly tied to strategic decisions about product mix, geographic footprint, and customer segmentation rather than simple procurement optimization.
Taken together, these drivers suggest a market in which advantage is increasingly defined by the ability to combine technical credibility, regulatory alignment, and resilient cost positioning. Suppliers that treat these elements as interconnected are more likely to capture premium demand and sustain margins through cycles of raw material fluctuation and specification tightening.
Competitive Landscape and Leading Strategies
The competitive landscape in MPP films reflects a blend of regional manufacturing strength, application specialization, and varying degrees of vertical integration. Rather than competing on a single dimension, leading companies are building advantage through focused positioning, whether that means deep expertise in capacitor-grade dielectrics, scale in packaging-grade barrier films, or the ability to serve both high-performance and broader commercial applications with differentiated product lines.
In the capacitor and industrial electronics space, several manufacturers have established strong reputations by concentrating on metallised film quality, electrical consistency, and qualification support. Companies such as Cosmo Films, Anhui Saifu, Nantong Jiangsen Electronic Technology, Steiner Film GmbH, and Anhui Tongfeng Electronics illustrate different models within this segment. Some emphasise broad capacitor-grade portfolios that span lighting, motor run/start, and industrial power applications, while others focus on integrated production that links film manufacturing directly to capacitor assembly or specific bidirectional film outputs. This specialization allows them to respond to technical procurement requirements more effectively, offering variants such as aluminium-zinc, pure aluminium, and slope or RMF configurations that address insulation resistance and breakdown voltage needs. Their strategic value lies in reducing qualification friction for buyers who require predictable dielectric behaviour and documented performance under demanding conditions.
In packaging and broader industrial applications, a different set of players competes on barrier performance, capacity scale, and converter-oriented service. Jindal Films, Toray Plastics, Flex Films, Vibac, and Dunmore each bring distinct strengths, from vacuum-deposited aluminium barrier films designed for long-shelf-life food and beverage products to high-capacity BOPP portfolios and technical metallised substrates for diverse industrial uses. Their differentiation often centres on uniformity, coating and metallising control, and the ability to supply consistent material to downstream converters who require dependable runnability and barrier reliability. In this part of the market, scale and process reliability are critical, but so is the capacity to adapt film specifications to changing packaging architectures and brand-owner requirements.
The recent product activity from major component manufacturers further underscores how competitive advantage is increasingly tied to specification leadership. In 2025, Vishay Intertechnology introduced an AEC-Q200 qualified DC-link metallised polypropylene film capacitor rated for operation up to 125°C with enhanced robustness, targeting automotive, energy, and industrial use. Around the same period, TDK Corporation launched compact double-sided metallised polypropylene film capacitors suited for resonant topologies, and later updated technical specifications for additional series with detailed application and performance data. These moves highlight a broader dynamic: upstream film producers benefit when downstream component makers invest in higher-temperature, higher-voltage, and more tightly qualified solutions, because such products raise the performance baseline and expand demand for consistent, high-specification dielectric films.
Market concentration remains moderate, with the largest players holding meaningful but not dominant share. This structure leaves room for both consolidation and continued differentiation. Consolidation is likely where scale, feedstock access, or geographic reach can strengthen cost resilience, while fragmentation may persist where application-specific know-how, local qualification relationships, or specialised metallisation capabilities create defensible niches. New entrants face a challenging path unless they bring a clear technical or cost advantage, but regional expansion and targeted product launches remain viable strategies for established players seeking to deepen their footprint in high-growth demand areas. The overarching trend is toward a landscape where strategic positioning is defined less by total volume than by the ability to align product performance, qualification support, and supply reliability with the most valuable end-use segments.
Future Trends and Commercial Opportunities
Looking ahead three to five years, the MPP films market is likely to be defined by three interrelated trends. The first is the continued elevation of performance requirements in electrical and automotive applications. As power electronics become denser, operating temperatures rise, and qualification standards tighten, demand for capacitor-grade and DC-link films with proven thermal and electrical durability will expand. This creates opportunity for suppliers that can document high-temperature behaviour, long-term stability, and application-specific performance, particularly where downstream component makers are investing in qualified solutions for electrification and energy infrastructure.
The second trend is a gradual re-weighting of packaging demand toward material efficiency and simpler material streams. Brand owners and converters are under pressure to reduce multi-material complexity while preserving barrier performance and shelf life. Films that can deliver reliable moisture and gas barrier properties with fewer layers, or that integrate well into recycling-oriented design goals, are likely to gain preference in specification updates. This shift favours manufacturers that can balance metallised barrier consistency with flexible formatting and converter-friendly processing, especially in segments where shelf-life requirements remain stringent.
The third trend is regional cost divergence becoming a more persistent strategic variable. Because feedstock and monomer costs are moving differently across geographies, competitive positioning will increasingly depend on where capacity is located, how sourcing is managed, and which customer segments can absorb price movement through value-based differentiation. Manufacturers with diversified geographic exposure or the ability to shift product mix toward higher-specification, less price-elastic applications will be better insulated from regional volatility. At the same time, buyers in sensitive segments will continue to seek supply partners who offer predictable pricing frameworks and resilient availability.
These trends point to clear commercial opportunities, but they also carry risk. Overexposure to commodity packaging margins in a volatile cost environment can erode profitability, while over-concentration in a single application may leave a company vulnerable if qualification cycles lengthen or competing materials improve. There is also uncertainty around how quickly sustainability mandates translate into material substitution in packaging, and whether new capacitor technologies or alternative dielectrics eventually pressure certain MPP use cases. The most resilient strategies will be those that treat these uncertainties as inputs to portfolio design rather than as reasons to defer investment.
Strategic Recommendations for Decision-Makers
Manufacturers should use the current environment to sharpen product mix strategy. Prioritising segments where performance, qualification, and reliability command pricing power can reduce exposure to commodity margin pressure, while targeted investment in metallisation precision and high-temperature film consistency can strengthen position in electrical and automotive demand pools. Supply chain flexibility, including diversified feedstock sourcing and geographic balancing, remains essential to managing regional cost volatility without sacrificing service reliability.
PW Consulting
Investors should evaluate opportunities based on company positioning within application-specific value chains rather than headline scale alone. Assets and businesses that serve qualified capacitor, power electronics, or higher-barrier packaging applications are more likely to capture durable demand than undifferentiated commodity producers. It is equally important to assess whether a target’s cost structure and geographic footprint can withstand continued raw material divergence, and whether its product roadmap aligns with tightening qualification and sustainability expectations.
Procurement and supply chain leaders should treat film sourcing as a strategic specification decision, not just a cost exercise. Mapping suppliers by technical capability, qualification support, and regional cost resilience can improve both performance security and long-term pricing stability. Building multi-supplier strategies for critical applications, while consolidating volume where a single supplier offers clear technical or service advantage, can help balance risk and efficiency.
For organisations seeking a deeper view of segment-level demand patterns, regional dynamics, and company-specific positioning, the full PW Consulting market analysis provides a more granular foundation for planning. The complete report expands on the trends outlined here with detailed segmentation data, competitive profiles, and scenario-based insight designed to support investment, sourcing, and product strategy decisions across the MPP films value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Metallised Polypropylene Films (MPP Films) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com