

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Hands-Free Caddie Market: The 10.5% CAGR Reshaping Golf

Strategic Trends and Commercial Opportunities in the Worldwide Hands-Free Caddie Market
The global hands-free caddie market has entered a phase of accelerated expansion, transforming from a niche accessory into a strategic hardware category at the intersection of mobility automation and sports technology. Valued at approximately $165.15 million in 2020, the segment has grown consistently to reach $292.8 million by 2025. Projections indicate sustained momentum through the forecast horizon, with annual revenue expected to climb past $587 million by 2032. This trajectory reflects a compound annual growth rate of 10.45%, a pace that signals structural adoption rather than cyclical consumer spending. The growth is underpinned by shifting golfer preferences, mature autonomous navigation stacks, and increasing operator willingness to diffuse capital-intensive assets across higher-volume usage scenarios.
Golf GPS Market
Against this backdrop, three critical inflection points shape the current landscape. First, the technology stack is bifurcating between mature remote-control architectures and rapidly advancing autonomous follow systems that rely on sensor fusion and visual guidance. Second, course operators and equipment managers are reevaluating total cost of ownership as hands-free units begin to influence pace-of-play metrics, labor allocation, and customer retention. Third, safety and interoperability expectations are tightening. Think staggering incidents on inclines, and battery and navigation reliability standards that must hold across varied terrain and weather conditions. These pressure points are not merely compliance hurdles; they are becoming core design parameters that separate durable product lines from short-lived feature experiments.
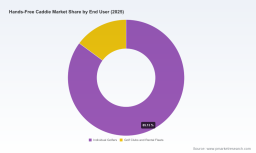
For executives and investors, the implication is clear: the market is large enough to attract serious engineering investment, yet fragmented enough that strategic positioning, reliability engineering, and go-to-market execution will determine which players capture lasting share. Volume leadership in individual consumer adoption continues to anchor baseline demand, while institutional buyers are increasingly evaluating hands-free assets as operational tools rather than premium add-ons. This dual demand structure creates both scale potential and segmentation complexity, requiring product roadmaps that can serve recreational users and fleet operators without compromising either value proposition.
Key Drivers Reshaping the Hands-Free Caddie Market
Technology Innovation and Autonomous Navigation Maturation
The most consequential driver is the rapid maturation of autonomous following technology. Early remote-control carts solved convenience but left the golfer tethered to a handheld interface. Today, sensor-based follow systems combine radio frequency, ultrasound, visual tracking, and increasingly LiDAR or time-of-flight sensing to maintain a stable hands-free walking experience across uneven terrain and moderate slopes. The practical effect is a shift from reactive remote operation to proactive caddie behavior: obstacle detection, terrain adaptation, reverse-follow modes, and gesture-based control are moving from marketing differentiators to baseline expectations. This evolution lowers the cognitive load for the golfer, improves consistency on hilly layouts, and expands the addressable experience beyond flat, predictable courses.
PW Consulting
From a product strategy perspective, the innovation curve is creating clear trade-offs. High-end autonomous stacks increase unit cost and introduce greater software maintenance, calibration, and sensor lifecycle considerations. Meanwhile, simpler remote-control and assisted-walking configurations remain attractive for price-sensitive segments and fleet deployments where simplicity and durability outweigh advanced autonomy. The competitive question is no longer whether hands-free features exist, but how reliably they perform in edge cases: wet conditions, narrow cart paths, dense tree cover, and steep descents where braking and stability become decisive. Manufacturers that solve these real-world reliability issues are gaining a defensible position in a market where reputation for ruggedness directly influences referral velocity and repeat purchase.
Policy, Safety Standards, and Operational Regulation
Regulatory and safety frameworks are increasingly shaping product architecture. Automatic downhill braking and stability controls are now central design requirements to prevent runaway incidents, particularly on courses with significant elevation changes. This is not only a liability issue; it affects insurance considerations for courses, fleet operators, and rental programs that deploy hands-free units at scale. In parallel, broader occupational safety concerns in the golf sector highlight the value of reducing human exposure to hazards on the course. The industry is witnessing a subtle but meaningful shift: hands-free equipment is being evaluated not only for golfer convenience but also as part of a broader risk-reduction and operational efficiency narrative.
For commercial strategy, this creates an opening for brands that can document safety performance with transparent engineering specifications and consistent testing protocols. It also raises the importance of service and assurance. A hands-free caddie is increasingly treated like a light autonomous asset rather than a simple mobility accessory, which means buyers look for durability certifications, clear maintenance pathways, and product documentation that supports fleet deployment. Companies that proactively align product development with these expectations can convert safety requirements into trust capital, particularly in markets where institutional procurement and course operator adoption are gaining momentum.
Demand-Side Shifts in Golfer Behavior and Course Economics
On the demand side, the market is being reshaped by changing expectations around the walking golf experience. A growing segment of golfers seeks ways to preserve the physical and experiential benefits of walking while minimizing burden and improving pace. Hands-free caddies address this by offering assistance without removing the golfer from a mobile, course-immersive experience. This demand is reinforced by a broader interest in lightweight, foldable, and quick-deploy designs that simplify transport, storage, and daily use. At the same time, individual buyers are increasingly sensitive to battery runtime, terrain performance, and multi-mode flexibility, which means product value is judged across an experience arc rather than a single feature.
Institutional demand is following a different but complementary logic. Golf clubs, resort operators, and rental fleets are evaluating hands-free units as tools that can enhance the guest experience while supporting operational flexibility. For high-traffic properties, the ability to offer a walking option that feels modern and supportive can improve perceived quality, widen appeal to fitness-oriented players, and reduce friction in cart allocation during peak periods. However, fleet adoption introduces distinct buying criteria: robustness, serviceability, theft resistance, battery management, and predictable maintenance costs. This divergence means the market is being pulled in two directions at once, by consumer experience demands and by operator economics, and the winners will be those who design for both without forcing a compromise that weakens either segment.
Cost Structure, Battery Systems, and Supply Chain Realities
Cost dynamics remain a foundational driver. Lithium battery systems, lightweight frames, compact actuation, and integrated electronics have improved the value equation for hands-free caddies, but they also tie product economics to component availability, manufacturing consistency, and after-sales support. As demand scales, manufacturers must manage the tension between performance differentiation and cost discipline. A premium autonomous model may win on capability, but margin sustainability depends on BOM control, service parts availability, and the ability to scale without introducing quality variance. Conversely, value-oriented product lines must avoid the trap of under-specifying critical safety and terrain features in pursuit of lower price points, since poor reliability can damage adoption more quickly than a higher sticker price.
Supply chain considerations are increasingly strategic. Product lines that can modularize core components, standardize battery platforms, and reduce assembly complexity are better positioned to manage cost volatility and accelerate refreshes. At the same time, distribution and service networks matter more as the category grows. A hands-free caddie that performs well in demonstrations but lacks local support can lose momentum quickly in mature golf markets. The commercial opportunity is therefore not only in building a better product, but in building a repeatable delivery model that includes warranty handling, battery replacement pathways, and regional support infrastructure.
Competitive Landscape and Leading Strategies
Differentiated Positioning Across the Value Chain
The competitive field shows clear strategic clusters rather than a single race to the top. MGI Golf has emphasized intelligent navigation and autonomous capability, pairing patented gyroscope and AI-based navigation with rugged terrain performance and expanding its innovation pipeline with new launches at major industry gatherings. Its positioning centers on combining hands-free autonomy with the practical durability expected from a mass-market electric caddie brand. Stewart Golf has leaned into premium engineering and stability on hilly courses, using advanced follow technology to reinforce the walking experience and pace-of-play benefits. CaddyTrek has built recognition around robotic follow models that span ultrasound or RF-based tracking and Smart Vision AI with gesture control, emphasizing terrain capability and flexible operating modes. Robera has focused on gesture-based autonomous following with visual guidance, precision ranging technologies for obstacle avoidance, reverse follow, and remote options, distinguishing its product narrative through high-precision hands-free operation.
Beyond these autonomous-oriented players, other leaders have taken different routes. Kangaroo Golf has emphasized remote-control electric caddies with ergonomic interfaces, lithium batteries, autobrake, and quick-fold designs, prioritizing assisted walking performance and usability. Motocaddy has integrated GPS and remote control into its electric lineup, supporting directional control and an enhanced golfer experience. Club Car has signaled interest in fully autonomous hands-free robotic caddies designed to replicate a caddie-like following experience for walking golfers through wireless integration. PowaKaddy has continued to build electric trolley options that combine GPS and remote features for assisted hands-free walking. Alphard Golf has offered remote electric carts and systems that convert push carts into motorized hands-free operation with strong terrain performance. QOD Golf USA has targeted compact remote and electric caddies with stability features for both hands-free and hands-on walking. This diversity shows a market where autonomy, remote control, and hybrid assisted designs all remain commercially relevant, each serving different price points, user expectations, and deployment contexts.
Market Structure, Concentration, and Strategic Drift
Market concentration provides useful context for competitive strategy. A relatively small group of leading players accounts for a meaningful portion of revenue, with the top three holding around 42.5% and the top five approaching 58.2%. This level of concentration suggests that scale, brand recognition, distribution reach, and product reliability have given established players a structural advantage. At the same time, the share held by the broader field indicates room for specialized entrants, regional differentiation, and technology-led disruption. The market is not yet locked into a winner-take-most pattern, but it is moving toward clearer category leadership in both premium autonomy and value-focused remote-control segments.
The strategic implications are threefold. First, incumbents gain from repeat trust, service ecosystems, and course-level relationships that reduce buyer risk in fleet adoption. Second, specialized players can compete by owning a niche with exceptional execution, whether that means superior hill stability, richer sensor-based autonomy, lighter weight, or better ergonomics. Third, new entrants and adjacent brands can gain traction by bridging gaps between consumer convenience and operator practicality, especially where current offerings are either too premium or too utilitarian for a growing middle segment. The likely evolution is a combination of consolidation among complementary assets and continued fragmentation in feature sets, as brands differentiate around autonomy level, terrain capability, design language, and service economics rather than competing on a single dimension.
Future Trends and Commercial Implications
Over the next three to five years, the hands-free caddie market is likely to be shaped by three interconnected trends. The first is deeper autonomy with more robust perception. Follow systems will continue to integrate visual and ranging sensors, improving consistency in cluttered environments and on challenging terrain. This will raise customer expectations for hands-free behavior and push the category closer to light robotics in terms of reliability, calibration, and user interaction design. Commercially, this favors manufacturers that can pair advanced sensing with practical safety engineering, because the value of autonomy is only realized when it works predictably in real course conditions.
The second trend is broader institutional diffusion. As course operators and rental businesses gain more experience with hands-free units, adoption will increasingly be driven by operational considerations: guest experience, labor optimization, equipment utilization, and service predictability. That shift expands the addressable market beyond individual golfers and encourages product designs that support fleet management, battery logistics, and consistent handling across multiple units. The opportunity lies in offering platforms that can be configured for both retail and institutional use without fragmenting the supply base or sacrificing reliability.
Hand Trucks Market
The third trend is tighter integration with the broader golf technology ecosystem. GPS integration, connectivity features, and software-driven modes will become more common, enabling richer user experiences and better usage visibility for operators. This creates opportunities for services around data-informed maintenance, usage analytics, and upgrades, but it also introduces dependency on software lifecycle management and interoperability. The uncertainty here is not whether connectivity will expand, but whether manufacturers can sustain software support, manage cybersecurity expectations, and avoid fragmented ecosystems that frustrate buyers. Companies that treat the hands-free caddie as a connected mobility product rather than a static accessory will be better positioned to capture recurring value, provided they can deliver dependable support over time.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Prioritize reliability where it affects trust most: braking and stability on inclines, terrain adaptability, battery consistency, and intuitive mode switching. Differentiate through engineering substance rather than feature claims alone. Build modular architectures that allow cost control while preserving the ability to introduce advanced autonomous capabilities selectively. Equally important, invest in regional service capacity and parts availability, because post-purchase support increasingly determines long-term reputation in a category where hands-free performance must be proven over repeated use.
For Investors and Strategic Allocators
Focus on companies that combine defensible product differentiation with scalable distribution and clear service economics. The strongest opportunities are likely to emerge where autonomy, durability, and operational support intersect, especially in firms that can address both consumer and institutional demand without forcing an either-or strategy. Assess whether product roadmaps are aligned with sensor maturation, safety expectations, and fleet-ready design, since these factors will shape margin resilience and competitive durability as the market expands.
For Procurement Teams and Course Operators
Evaluate hands-free caddies as operational assets, not just consumer conveniences. Weight total cost of ownership, terrain performance, service response, and battery management alongside user experience. Pilot deployments should test real-course scenarios, not only showroom demonstrations, with particular attention to slope handling, obstacle response, and maintenance turnaround. A disciplined procurement approach reduces downtime risk and improves the likelihood of consistent guest satisfaction.
The market trajectory points to continued growth, but durable advantage will come from execution discipline: safety-led engineering, practical autonomy, cost-aware product design, and support infrastructure that matches commercial ambition. For decision-makers seeking segment-level sizing, regional breakdowns, pricing dynamics, and customized strategy scenarios, the full research report provides the detailed data and scenario analysis needed to translate these trends into precise operating plans.
For detailed analysis of this topic, please visit the official page: Worldwide Hands-Free Caddie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com