

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Zhi Mu Extract Market: 6.74% CAGR Transforming Asia Pacific Growth

Strategic Trends and Commercial Opportunities in the Global Zhi Mu Extract Market
Market Overview and Critical Challenges
The global market for Zhi Mu extract, derived from the rhizome of Anemarrhena asphodeloides , has demonstrated steady growth over the past five years, expanding from approximately 37.85 million USD in 2020 to an estimated 52.48 million USD in 2025. Looking ahead, the market is projected to continue its upward trajectory, reaching roughly 82.86 million USD by 2032. This expansion translates to a compound annual growth rate of 6.74 percent between 2026 and 2032, signaling sustained commercial momentum across multiple downstream sectors.
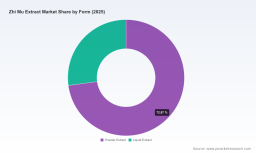
Geographically, the Asia Pacific region accounts for the largest share of total market activity, reflecting both Deep-rooted traditional usage patterns and growing domestic demand for standardized botanical ingredients. North America and Europe represent substantial secondary markets, driven largely by the incorporation of herbal extracts into dietary supplements, personal care formulations, and functional foods. Latin America and the Middle East and Africa collectively represent a smaller but gradually expanding footprint as awareness of botanical ingredients broadens across emerging consumer bases. In terms of physical form, powder extracts command the majority of market activity, while liquid extracts maintain a meaningful but secondary position. Application-wise, cosmetics and personal care represent the largest end-use segment, followed by pharmaceuticals and nutraceuticals, with food and beverages accounting for a more modest share of total demand.
PW Consulting
Despite this favorable growth trajectory, the industry is navigating several structural challenges that will define competitive outcomes over the next decade. First, supply chain concentration and raw material sourcing remain critical vulnerabilities. The primary botanical source for Zhi Mu is cultivated under controlled conditions in China, where extraction processes involve cleaning, drying, and specialized isolation techniques to capture active compounds such as timosaponins. Any disruption in cultivation cycles, quality variability across harvests, or shifts in agricultural input costs can quickly cascade through downstream pricing and availability.
Second, regulatory divergence across key markets is creating compliance complexity for manufacturers and buyers alike. In the United States, herbal products including Zhi Mu extracts are regulated as dietary supplements under DSHEA 1994, which mandates testing for pesticides, heavy metals, and microbial contamination but does not require full pharmaceutical-grade good manufacturing practices. This framework provides operational flexibility but also introduces quality assurance variability that sophisticated buyers increasingly scrutinize. Meanwhile, import dynamics have intensified cost pressures. As of April 2025, US tariffs on China-sourced botanicals reached a minimum rate of 145 percent, significantly altering the cost structure for herbal ingredients entering one of the largest consumer markets globally. This policy shift is forcing supply chain actors to reconsider sourcing strategies, formulation economics, and margin expectations.
Third, market fragmentation presents both a challenge and an opportunity. The competitive landscape remains relatively dispersed, with no single entity commanding dominant market share. This dispersion creates price competition, inconsistent quality standards across smaller producers, and limited brand differentiation in commoditized segments. Companies that can institutionalize quality control, traceability, and application-specific formulation expertise will be best positioned to capture premium positioning as buyers move beyond basic ingredient procurement toward partnership-driven supply models.
Worldwide Picrorhiza Extract Market
Key Drivers Shaping Market Trajectory
Several interlocking forces are accelerating structural change within the Zhi Mu extract market. Understanding these drivers is essential for anticipating where value will concentrate and which capabilities will separate outperforming players from the rest of the field.
Technological innovation and extraction methodology advancement represent the first major driver. The isolation of active botanical compounds, particularly timosaponins, requires precise processing to maintain potency, consistency, and stability across batches. Producers that have invested in standardized extraction protocols, controlled drying stages, and purification methods are better equipped to deliver repeatable specifications demanded by pharmaceutical, nutraceutical, and cosmetic formulators. The ability to offer extracts at defined concentration ratios, maintain low variability in active marker compounds, and document process controls has become a baseline expectation rather than a differentiator. Over time, technological maturity in extraction efficiency will also influence cost structures, enabling producers to manage input volatility while preserving margin integrity.
Policy and regulatory evolution forms the second driver, with direct implications for market access and operating costs. The US tariff environment for China-sourced botanicals has introduced a sharp cost adjustment for importers reliant on Zhi Mu materials. In response, market participants are evaluating diversified sourcing arrangements, inventory planning adjustments, and formulation cost rebalancing. Simultaneously, the regulatory framework governing herbal supplements continues to shape buyer expectations around testing, documentation, and quality assurance. While the current supplement pathway does not mandate pharmaceutical GMP, large buyers in cosmetics and nutraceuticals increasingly impose their own supplier qualification standards that exceed minimum regulatory thresholds. This dynamic rewards manufacturers with robust certification portfolios and documented process controls.
Demand-side shifts in consumer and corporate behavior constitute the third driver. Interest in botanical ingredients continues to grow across personal care, wellness, and functional nutrition categories. Consumers are increasingly attentive to ingredient provenance, clean-label positioning, and transparent sourcing narratives. For Zhi Mu specifically, its traditional usage background and expanding application in modern formulations create a bridge between heritage appeal and contemporary product development. On the corporate side, formulators are seeking botanical ingredients that can be integrated into stable, scalable production processes without compromising product claims or sensory profiles. This has elevated the importance of technical support, specification reliability, and application guidance from ingredient suppliers.
Supply chain and cost structure dynamics represent the fourth driver. Raw material cultivation, extraction processing, certification maintenance, and logistics all influence total delivered cost. As tariff pressures and input variability affect landed costs, companies are reweighting the importance of supply resilience. This includes evaluating supplier geographic concentration, understanding seasonal raw material availability, and assessing the financial impact of certification requirements such as HACCP, ISO22000, ISO9001, BRC, and organic certifications. Producers that can combine cost discipline with verifiable quality credentials are gaining negotiating leverage with downstream buyers who face their own margin and compliance pressures.
Recent commercial activity illustrates how these drivers are already playing out. Several manufacturers have increased visibility at international trade platforms, showcasing botanical ingredients to procurement teams and product developers in Europe and North America. At the same time, certain US-based producers have continued to emphasize organic-certified powder and liquid formats aimed at clean-label applications, reflecting the market's shift toward transparency and specification clarity. These developments suggest that competitive advantage is increasingly tied to market access strategy, certification depth, and the ability to serve application-specific buyer needs rather than price alone.
Competitive Landscape and Leading Strategies
The competitive environment in the Zhi Mu extract market is characterized by a mix of established botanical ingredient manufacturers, specialized extract producers, and regional suppliers with distinct strategic postures. No single company currently dominates the market, which keeps competition dynamic and creates room for differentiation through quality, certifications, and application focus.
Chinese-based manufacturers form the backbone of global supply, reflecting the concentration of raw material cultivation and extraction infrastructure in the region. Several producers have built profiles around standardized herbal extracts for global distribution, backed by certifications such as HACCP, ISO22000, and ISO9001. These credentials support export-oriented business models by signaling process reliability to international buyers. Other manufacturers emphasize customized botanical extracts tailored for human health applications, positioning themselves as flexible suppliers capable of serving bulk demand across pharmaceutical and nutraceutical channels.
A subset of producers is differentiating through organic and sustainable production emphasis. These companies pursue certifications such as BRC, organic approvals, and ISO9001 to serve buyers in pharmaceutical, nutraceutical, and cosmetic applications where ingredient integrity and documentation are especially valued. This orientation aligns with growing buyer interest in traceability and environmentally conscious sourcing narratives. Another group of manufacturers specializes in defined extract ratios for pharmaceutical-focused applications, leveraging long operating histories in botanical extracts and natural ingredients to serve formulators that require consistent specification ranges.
Outside China, US-based production represents a strategically distinct segment. One Honolulu-based manufacturer has maintained a focus on alcohol-free and alcohol-based liquid extracts and tinctures produced in small batches under GMP standards within an FDA-registered facility. This positioning appeals to buyers seeking domestically manufactured options, smaller lot flexibility, and formulation formats suited to tincture and liquid-based product development. Such offerings also respond indirectly to import cost and sourcing risk concerns by providing an alternative supply path, albeit at a different cost profile and scale.
Regional specialists also play important roles. Some suppliers concentrate on natural medical herbs and rhizoma Anemarrhenae for traditional Chinese medicine applications, servicing demand that remains closely tied to heritage usage and specific formulation traditions. Others focus on high-purity extract lines for pharmaceutical and nutraceutical applications, emphasizing product specificity and application-targeted production. The presence of multiple specialized players indicates a market that is not yet fully consolidated and where niche expertise can command meaningful buyer interest.
Leading companies are pursuing differentiation along several axes. One is certification and quality documentation. Manufacturers with multiple recognized certifications are better positioned to pass supplier qualification processes and enter regulated or semi-regulated supply chains. Another axis is application breadth. Companies that can support cosmetics, personal care, pharmaceutical, nutraceutical, and food and beverage buyers with appropriate extract formats and technical support gain cross-market optionality and reduce dependence on a single demand cycle. A third axis is market access and visibility. Participation in major trade shows and regional industry events allows producers to engage directly with international procurement teams, showcase specification capabilities, and gather market feedback that informs product and certification strategy.
The market structure appears likely to evolve through a combination of consolidation, specialization, and new entry. Consolidation may accelerate as larger botanical ingredient groups seek to secure reliable supply, expand certification portfolios, and reduce supplier fragmentation in their own value chains. Specialization will continue to reward producers that commit to specific extract formats, purity thresholds, or application segments. New entrants may emerge where import cost dynamics, domestic manufacturing incentives, or certification advantages create viable niches. Overall, the strategic imperative is moving from volume-based competition toward capability-based competition, where quality consistency, documentation depth, and buyer-facing technical support determine commercial outcomes.
Future Trends and Risk Outlook
Over the next three to five years, several trends are likely to shape how value is created and captured in the Zhi Mu extract market. The first trend is the elevation of specification and traceability as commercial defaults. As downstream buyers in cosmetics, nutraceuticals, and functional foods face greater scrutiny from retailers, regulators, and consumers, ingredient suppliers will be expected to provide more granular documentation, batch-to-batch consistency, and clearer sourcing narratives. This will reward manufacturers that invest in process control and transparent quality systems, while pressuring those that compete primarily on price without supporting documentation.
The second trend is supply chain reconfiguration in response to cost and access pressures. The current tariff environment for China-sourced botanicals is already prompting buyers to reexamine sourcing mix, inventory timing, and formulation economics. While China will likely remain a central source of raw material supply for the foreseeable future, market participants may pursue diversified sourcing strategies, regional manufacturing options, or reformulated product economics to manage cost volatility. This trend creates opportunities for producers with strong certifications, stable supply continuity, and flexible export capabilities, but it also raises the importance of risk planning for buyers dependent on single-source procurement.
The third trend is application expansion beyond traditional use cases. While cosmetics and personal care currently represent the largest demand segment, interest in nutraceuticals, functional food and beverage formats, and specialized liquid extract applications continues to broaden the commercial canvas. Companies that can translate raw botanical material into application-ready ingredients with appropriate stability, sensory compatibility, and claim-supportable specifications will be best positioned to capture growth across these emerging demand pockets.
Worldwide Houttuynia Extract Market
Potential risks and uncertainties should not be overlooked. Regulatory requirements may tighten in key markets, changing testing expectations or documentation thresholds and increasing compliance costs. Trade policy volatility could continue to affect landed costs and disrupt established procurement patterns. Raw material supply remains exposed to agricultural variability, climate influences, and cultivation scale limitations, which could affect availability and pricing at times. Finally, quality inconsistency across smaller producers may trigger buyer consolidation toward fewer, more credible suppliers, intensifying competitive pressure on manufacturers without differentiated credentials or technical capabilities.
Strategic Recommendations for Decision Makers
For manufacturers and ingredient producers, the priority is to strengthen specification reliability, certification depth, and application-specific support. Investing in process controls, documentation, and recognized quality credentials will improve access to downstream buyers with stricter supplier qualification standards. At the same time, producers should evaluate how supply chain risks, including raw material variability and import cost pressures, can be mitigated through capacity planning, diversified customer exposure, and clear positioning around extract formats and application fit.
For investors, the market signals a preference for capabilities rather than scale alone. Opportunity areas include producers with credible certification portfolios, stable quality systems, and demonstrated access to international buyer channels. Sector oversight should also weigh exposure to trade policy shifts, raw material sourcing concentration, and the pace at which demand expands beyond the largest application segments. A disciplined view of margin sustainability under different sourcing and tariff scenarios will help distinguish resilient business models from those vulnerable to cost shocks.
For procurement teams and formulators, the actionable focus is to treat ingredient selection as a multi-dimensional decision rather than a unit-price exercise. Evaluating supplier quality systems, extract format suitability, batch consistency, and documentation readiness can reduce downstream reformulation risk and improve product launch reliability. Diversifying sourcing where feasible and maintaining visibility into supply continuity will also help manage exposure to cost volatility and policy changes.
Keeping pace with specification evolution, certification expectations, and shifting sourcing economics requires timely, granular intelligence. Decision makers who want detailed segmentation data, competitive benchmarking, and customized strategic guidance will find additional value in the complete research report, which extends the analysis with deeper segmentation breakdowns and application-specific commercial implications.
For detailed analysis of this topic, please visit the official page: Worldwide Zhi Mu Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com